ESG standards · by type, setter and legal weight
ESG standards: what binds in the UK
Disclosure, measurement, assurance and management standards do different jobs. Their publication does not itself make every UK organisation comply.
Identify the reporting rule first, then the standards it uses. This guide separates legal duties, comply-or-explain obligations and voluntary choices.
Definitions
Standard, framework, regulation: three words, three weights
A standard sets requirements precise enough that compliance can be claimed and checked: UK SRS S2, ISO 14001 and ISSA (UK) 5000 are all standards in that sense.
A framework sets principles and a structure: the TCFD’s four recommendations provided a foundation for the ISSB’s sustainability disclosure standards.
Read the detailed guidance and references
Regulation is what turns either into a duty, and in the UK the routes shown here are an Act or statutory instrument, a regulator’s rulebook, or a code applied through a reporting requirement. Government endorsement alone does not create a reporting duty.
Most of what is called an ESG standard is voluntary until an applicable law, rule or contract adopts its requirements.
UK SRS is the clearest case: the standards bind nobody, and the FCA’s rule makes a listed company in scope report against them or explain why not.
The frameworks compared by reader and purpose are on ESG frameworks in the UK, and the regulatory duties by instrument on ESG reporting requirements in the UK.
How a company runs those duties as one programme is on ESG reporting in practice.
Can a report, a system or an engagement be said to comply with it?
If yes, it is a standard.
If it sets principles without that test, it is a framework.
If Parliament or a regulator imposes it, it is regulation, whatever its name.
Three different questions
Standard
Three different questions
Framework
Three different questions
Regulation
Three different questions
Scope
The register · 1 October 2026
Twenty-two standards, filtered by type or by weight
Choose a type (disclosure, measurement, assurance, management system, claims, governance, conduct) or a legal weight (law, comply or explain, voluntary, withdrawn).
Every row is cited in the sections below.
Read the detailed guidance and references
Filter
Showing 22 of 22
| Standard | Set by | Status in the UK |
|---|---|---|
| UK SRS S1 and S2 | DBT (standards); FCA (the duty) | Voluntary; comply or explain for five listing categories, periods from 1 Jan 2027 |
| Companies Act 2006 ss.414CA–414CB (climate) | Parliament, via SI 2022/31 | Law since 6 April 2022 for named categories with more than 500 employees |
| SECR (SI 2008/410 Sch 7) | Parliament, via SI 2018/1155 | Law since 1 April 2019 for quoted and large unquoted companies and LLPs |
| Section 172(1) statement (s.414CZA) | Parliament | Law for companies above the medium-sized test |
| Modern Slavery Act 2015 s.54 | Parliament; Home Office | Law for suppliers with total turnover of £36m or more |
| Gender pay gap regulations (SI 2017/172) | Parliament | Law for employers with 250 or more employees on 5 April |
| IFRS S1 and S2 | ISSB | Global baseline; not UK law |
| SASB Standards | ISSB | Voluntary; “may” in UK SRS |
| GRI Standards | GRI (GSSB) | Voluntary; no UK instrument requires them |
| ESRS (DR (EU) 2026/1563) | European Commission | EU law where the CSRD reaches a group; FY2027 on |
| GHG Protocol Corporate, Scope 2 and Scope 3 Standards | WRI and WBCSD | Voluntary; named as the basis in UK SRS S2 |
| UK Government conversion factors | DESNZ | Guidance; the factor set for SECR practice |
| ISO 14064-1:2018 | ISO | Voluntary GHG quantification at organisation level |
| ISSA (UK) 5000 | FRC | Voluntary use; periods beginning on or after 15 Dec 2026 |
| ISO 14064-3:2019 | ISO | Verification and validation of GHG statements |
| ISO 14001:2026 | ISO | Published 15 April 2026; the 2015 edition is withdrawn |
| ISO 50001 | ISO | Voluntary; an ESOS compliance route where it covers total or significant energy |
| ISO 14068 (carbon neutrality) | ISO | ISO 14068-1:2023 withdrawn 11 Sep 2026; ISO 14068:2026 under publication |
| PAS 2060 | BSI | Withdrawn; verification stopped 1 January 2025 |
| UK Corporate Governance Code 2024 | FRC | Comply or explain for two listing categories; Provision 29 from 2026 |
| FCA anti-greenwashing rule (ESG 4.3.1R) | FCA | Binding on every authorised firm since 31 May 2024 |
| ESG Ratings Order 2025 (SI 2025/1349) | HM Treasury; FCA | Made; authorisation needed from 29 June 2028 |
Statuses as at 1 October 2026, each from the owner’s own instrument; nothing you choose is stored.
Choose a type (disclosure, measurement, assurance, management system, claims, governance, conduct) or a legal weight (law, comply or explain, voluntary, withdrawn).
Every row is cited in the sections below.
Read a standard by its job
Assurance
Read a standard by its job
Management and conduct
Legal weight
Three public routes from standard to duty
Three routes create the obligations shown here: statute, regulator rules and a code applied through a reporting requirement. Endorsement alone does not create an organisation’s reporting duty.
Read the detailed guidance and references
| Route | How it binds | Examples | Who enforces |
|---|---|---|---|
| Statute | An Act or statutory instrument writes the duty | SECR, s.414CB, MSA 2015, gender pay gap | Courts, the FRC, the EHRC, the Environment Agency |
| Regulator’s rule | A rule in the FCA Handbook | UK SRS via PS26/19; the anti-greenwashing rule | The FCA |
| Code on comply or explain | A listing rule requires a statement of compliance or an explanation | The UK Corporate Governance Code | Shareholders read the explanation; the FCA polices the statement |
| Endorsement | The government adopts an international standard for UK use | UK SRS from IFRS S1 and S2, under the endorsement framework | Nobody, until a rule refers to it |
| None | Adopted by choice, contract or customer demand | GRI, SASB, ISO 14001, ISSA (UK) 5000, CDP | Certification bodies, customers, contracts |
The route decides who is bound, what happens on breach and whether an explanation is enough.
An in-scope entity must meet the applicable statutory disclosure requirements, including any exemptions, reliefs and permitted omissions. SECR has its own scope and exemptions.
A regulator’s rule binds the regulated population: the anti-greenwashing rule reaches every FCA-authorised firm and nobody else.
A comply-or-explain code accepts a reasoned departure as compliance, which is why an explanation under the listing rules is a real answer and not a failure.
Endorsement makes a standard available for UK use. The applicable reporting requirement determines whether an organisation must report against it, as the FCA’s listing rules do for UK SRS.
- 1
Publication
A standard is available for use.
- 2
Adoption or endorsement
A jurisdiction or organisation selects it.
- 3
Applicable duty
Read the statute, regulator rule or contractual requirement.
- 4
Reporting decision
Apply scope, dates, reliefs and permitted explanations.
Type 1
Disclosure standards: what you report
The UK’s disclosure standards split into what company law requires and what UK SRS describes.
Company law requires SECR energy and carbon in the directors’ report and eight climate disclosures in the strategic report under section 414CB, each for its own population.
Read the detailed guidance and references
It also requires a section 172(1) statement under section 414CZA, describing how directors had regard to matters including the community and the environment, from every company that does not qualify as medium-sized.
UK SRS S1 and S2 set out sustainability and climate disclosures for investors, built on the ISSB’s IFRS S1 and S2.
The final FCA rules apply them to companies in UKLR 6, 14, 15, 16 and 22 on comply or explain, with a one-year Scope 3 relief and a two-year relief for non-climate matters under S1.
The FCA’s rules finalise CP26/5, which had proposed mandatory climate reporting; the final rules do not make any part of UK SRS mandatory.
The GRI Standards and the EU’s ESRS sit beside them: GRI voluntary in the UK, the ESRS binding only where the CSRD reaches a group.
The standards themselves are read paragraph by paragraph on UK SRS S1 and UK SRS S1 and S2, the FCA rule on the FCA and UK SRS, and the climate duty on TCFD in the UK.
- 1 Apr 2019SECR applies
Financial years beginning on or after.
- 6 Apr 2022Companies Act climate disclosures apply
- Jun 2023IFRS S1 and S2 issued
- 25 Feb 2026UK SRS S1 and S2 published
- 30 Sep 2026FCA PS26/19 published
- 1 Jan 2027UK SRS listing rules apply; revised ESRS apply
- 2028First UK SRS reports by listed companies
Start with the reporting route
Company law
Start with the reporting route
Listed issuers
Start with the reporting route
EU connection
Start with the reporting route
Voluntary use
Type 2
Measurement standards: how the numbers are made
A disclosure standard says what to report; a measurement standard says how the figure is calculated.
The GHG Protocol is the measurement basis almost every disclosure standard points to: its Corporate Standard defines Scopes 1 and 2, and its Scope 3 Standard the value chain.
Read the detailed guidance and references
UK SRS S2 names the GHG Protocol Corporate Standard as the basis for measuring emissions, subject to reliefs.
SECR names no single method, and the government’s Environmental Reporting Guidelines describe how to apply it, with the government conversion factors supplying the UK emission factors each year.
ISO 14064-1:2018 is the ISO route to organisation-level greenhouse gas quantification and is programme-neutral.
None of these is law in itself; each becomes binding only where a disclosure duty or a contract adopts it.
How SECR figures are built in practice is on the SECR reporting guide.
Keep the calculation visible
Boundary
Keep the calculation visible
Method
Keep the calculation visible
Factors
Keep the calculation visible
Reconciliation
Type 3
Assurance standards: how someone checks the numbers
The FRC issued ISSA (UK) 5000 on 12 November 2025, adopting the IAASB’s ISSA 5000.
It is effective for engagements on periods beginning on or after 15 December 2026, or as at a date on or after that day, and earlier application is permitted.
Read the detailed guidance and references
It is for voluntary use: it governs how an engagement is performed if one is commissioned, not whether one must be.
Published UK reports also cite ISAE (UK) 3000, with ISAE 3410 for greenhouse gas statements, and ISO 14064-3 is the ISO route for verifying a GHG statement; examples are on ESG reporting examples.
The FCA’s UK SRS listing rules require an assurance statement but do not require a company to commission assurance. Separate overseas obligations and contractual requirements must be checked on their own terms.
The FRC lists the standards it issues on its assurance standards page.
What a listed company must say
Under the made rule, UKLR 6.6.6R(8)(d), whether third-party assurance was obtained over the disclosures and, if so, the provider, what was assured, the level of assurance and the standards used.
The rule asks for the statement, not the assurance.
Source: PS26/19, Appendix 1
An engagement is a separate choice
Reporting duty
An engagement is a separate choice
Assurance decision
An engagement is a separate choice
Engagement standard
An engagement is a separate choice
Public statement
Types 4 and 5
Management system and claims standards: ISO and BSI
There is no single ISO ESG standard, despite the question being asked often.
ISO 14001 sets requirements for an environmental management system; ISO 14001:2026 was published on 15 April 2026 and the 2015 edition is withdrawn, so a certificate should name the edition.
Read the detailed guidance and references
ISO 50001 does the same for energy management, and under the ESOS Regulations, as amended, a certified system that covers a participant’s total or significant energy consumption is a route to ESOS compliance for that energy.
ISO 45001 covers occupational health and safety management.
Claims standards are the fastest-moving group: ISO 14068-1:2023 on carbon neutrality was withdrawn on 11 September 2026 and replaced by ISO 14068:2026, which is under publication.
PAS 2060, the BSI carbon neutrality specification, is withdrawn: verification stopped on 1 January 2025, so no organisation can newly claim it.
These standards have different subjects. ISO 14001 and ISO 50001 concern management systems; ISO 14064-3 concerns verification and validation of GHG statements; ISO 14068 concerns carbon-neutrality claims. Check the exact subject and edition before describing certification or verification.
Do not confuse the outputs
Management system
Do not confuse the outputs
GHG statement
Do not confuse the outputs
Neutrality claim
Do not confuse the outputs
Certificate scope
Types 6 and 7
Governance and conduct standards: the G, and the claims police
The UK Corporate Governance Code 2024 applies to companies in the commercial companies and closed-ended investment funds categories, on comply or explain.
The FRC deliberately added no sustainability reporting requirement to it.
Read the detailed guidance and references
Provision 29, for financial years beginning on or after 1 January 2026, asks the board to declare the effectiveness of material controls, and the FRC includes narrative and ESG reporting controls within that.
For conduct, the FCA’s anti-greenwashing rule, ESG 4.3.1R, has required every authorised firm since 31 May 2024 to make sure sustainability references are consistent with a product’s characteristics and are fair, clear and not misleading.
The SDR regime adds four investment labels and naming and marketing rules for fund managers, set out on FCA SDR and anti-greenwashing.
The newest conduct standard regulates the raters: the ESG Ratings Order 2025, made on 15 December 2025, requires providers of certain ESG ratings to be authorised by the FCA from 29 June 2028.
It places no duty on the companies being rated.
The criteria raters and investors apply are on ESG criteria, and what each of the three letters covers on the ESG pillars.
Governance and claims differ
Board controls
Governance and claims differ
Investment products
Governance and claims differ
Greenwashing
Governance and claims differ
Ratings providers
Test yourself
Seven statements about UK ESG standards
The statements beside this text are the claims most often made about who sets which standard and what binds.
Each answer names the instrument it rests on.
Read the detailed guidance and references
Two are the commonest errors on this subject: that UK SRS came from the FCA, and that ISSA (UK) 5000 made assurance compulsory.
The global landscape of standard-setters is mapped on the global standards map, and a standards editorial reading sits on our sister reference, sustainabilityreportingstandards.co.uk.
What ESG means in the first place is on what is ESG.
ESG standards · true or false
UK SRS S1 and S2 were issued by the FCA.
Reporting against UK SRS is a listing rule from accounting periods beginning on or after 1 January 2027.
ISSA (UK) 5000 makes sustainability assurance compulsory.
PAS 2060 is the current BSI standard for a new carbon-neutrality claim.
The UK Corporate Governance Code contains a sustainability reporting requirement.
The ESG Ratings Order regulates the companies that receive ESG ratings.
SECR’s own thresholds did not move when the Companies Act size limits rose in April 2025.
0 of 7 answered.
Nothing you choose is stored or sent.
Check the proposed claim
Issuer
Check the proposed claim
Status
Check the proposed claim
Period
Check the proposed claim
Evidence
Publication and application
The dates have different meanings
Use the relevant financial-year start and legal route. A publication date is not automatically a company deadline.
- 1 April 201901
- 6 April 202202
Statutory climate disclosures begin
Read the company or LLP scope and reporting requirements. - 25 February 202603
- 15 December 202604
ISSA (UK) 5000 effective date
The engagement standard does not itself compel assurance. - Periods from 1 January 202705
UK SRS listing-rule application
Five categories report against the standards or explain. - 29 June 202806
ESG ratings provider authorisation
Read the ratings order’s scope, rather than applying it to rated companies.
A practical selection sequence
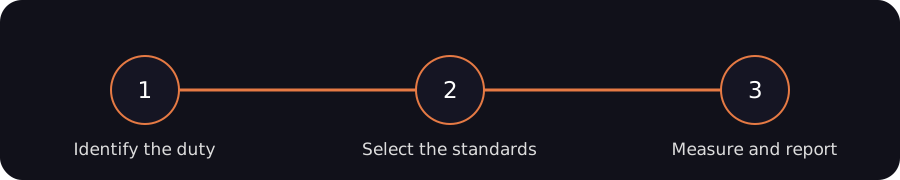
Build the stack around your duty
Keep a short evidence record for every selection. The ESG reporting requirements UK guide gives the fuller duty map.
- 01 / Scope01
Identify the entity and rule
Record the legal route, reporting boundary and first period. - 02 / Disclosure02
Select the applicable reporting requirements
Keep final standards, drafts and voluntary additions separate. - 03 / Measurement03
Define methods and data controls
Retain factors, calculation records and comparative policies. - 04 / Review04
Decide the assurance approach
Check separate requirements, contracts and engagement scope. - 05 / Publish05
Connect the evidence and statement
Check reporting locations, explanations and required confirmations.
Frequently asked
ESG standards, answered
What are ESG standards?
ESG standards are published documents that set specific requirements for measuring, reporting, assuring or managing environmental, social and governance matters, specific enough that a company can comply with them.
They range from disclosure standards such as UK SRS and the GRI Standards, to measurement standards such as the GHG Protocol, to assurance standards such as ISSA (UK) 5000 and management system standards such as ISO 14001.
What are the main ESG standards in the UK?
For disclosure: UK SRS S1 and S2, the Companies Act climate disclosures, SECR and the FCA’s listing rules.
For measurement: the GHG Protocol and the government’s conversion factors.
For assurance: ISSA (UK) 5000 and ISAE (UK) 3000.
For governance: the UK Corporate Governance Code.
For conduct: the FCA’s anti-greenwashing rule.
Only some of these bind, and each binds a different set of organisations.
Which UK ESG standards are mandatory?
SECR, the Companies Act climate disclosures, the section 172(1) statement, the Modern Slavery Act statement and gender pay gap reporting are law for the organisations each reaches.
The FCA’s anti-greenwashing rule binds every authorised firm.
UK SRS is voluntary, except that listed companies in five categories must report against it or explain from accounting periods beginning on or after 1 January 2027.
ISSA (UK) 5000, ISO 14001 and the GRI Standards are voluntary.
What is the difference between an ESG standard and a framework?
A standard sets requirements precise enough that a report or a system can be said to comply with it, such as UK SRS S2 or ISO 14001.
A framework gives principles and a structure without a compliance test of its own, such as the TCFD’s four recommendations.
Standards are what regulators point to; frameworks are what standards are often built on.
Is UK SRS a standard or a framework?
UK SRS S1 and S2 are standards: specific disclosure requirements published by the Department for Business and Trade on 25 February 2026, built on the ISSB’s IFRS S1 and S2.
They are voluntary in themselves, and the FCA’s PS26/19 makes reporting against them, or explaining why not, a listing rule for five categories of listed company.
What are the ISO ESG standards?
There is no single ISO ESG standard.
The ISO standards most used in ESG reporting are ISO 14001 (environmental management systems, now in its 2026 edition), ISO 50001 (energy management), ISO 45001 (occupational health and safety), the ISO 14064 family for greenhouse gas quantification and verification, and ISO 14068 on carbon neutrality, whose 2023 first part was withdrawn on 11 September 2026.
All are voluntary.
What was the UK ESG regulation of 2022?
The Companies (Strategic Report) (Climate-related Financial Disclosure) Regulations 2022, SI 2022/31, which apply for financial years beginning on or after 6 April 2022.
They amended the Companies Act 2006 to require eight climate-related disclosures in the strategic report from the categories of company in section 414CA with more than 500 employees.
Who regulates ESG ratings in the UK?
From 29 June 2028, the FCA.
The Financial Services and Markets Act 2000 (Regulated Activities) (ESG Ratings) Order 2025, made on 15 December 2025, brings the provision of certain ESG ratings into the FCA’s perimeter.
It regulates the firms that provide ratings, not the companies they rate.
Is assurance of ESG reporting mandatory in the UK?
The FCA’s UK SRS listing rules do not require a company to commission assurance.
Separate overseas or contractual requirements may apply.
ISSA (UK) 5000, issued by the FRC on 12 November 2025, is effective for engagements on periods beginning on or after 15 December 2026 and is for voluntary use.
Under the FCA’s final rules, a listed company states whether it obtained assurance and, if so, from whom, over what, to what level and on which standard; obtaining it is not required.
Sources
Primary sources
Every figure, date and status on this page traces to the instrument’s owner.
Secondary commentary is never the source for a number.
- Department for Business and TradeUK Sustainability Reporting Standards: UK SRS S1 and UK SRS S2
Issued 25 February 2026 for voluntary use.
- Department for Business and TradeFramework for developing UK Sustainability Reporting Standards
How an ISSB standard is assessed and endorsed for the UK.
- Financial Conduct AuthorityPS26/19: Aligning listed issuers’ sustainability disclosures with international standards
UK SRS on comply or explain for UKLR 6, 14, 15, 16 and 22, periods from 1 January 2027.
- Financial Conduct AuthorityPS26/19 (PDF), ¶¶1.2, 1.7, 3.6, 3.12, 3.14
The basis, scope, start date and reliefs.
- Financial Conduct AuthorityCP26/5 — the consultation PS26/19 finalises
The proposals the final rules changed.
- legislation.gov.ukSI 2008/410 Schedule 7 (SECR)
Energy and carbon in the directors’ report.
- legislation.gov.ukThe Companies (Directors’ Report) and LLP (Energy and Carbon Report) Regulations 2018 (SI 2018/1155)
The instrument that inserted SECR from 1 April 2019.
- legislation.gov.ukThe Companies (Strategic Report) (Climate-related Financial Disclosure) Regulations 2022 (SI 2022/31)
The amending instrument for the 2022 climate duty.
- legislation.gov.ukCompanies Act 2006, sections 414CB and 414CZA
The eight climate disclosures; the section 172(1) statement is at s.414CZA.
- legislation.gov.ukCompanies Act 2006, section 414CZA
The section 172(1) statement and its medium-sized exemption.
- legislation.gov.ukModern Slavery Act 2015
Section 54 transparency in supply chains.
- legislation.gov.ukThe Equality Act 2010 (Gender Pay Gap Information) Regulations 2017
The 250-employee reporting duty.
- legislation.gov.ukThe Energy Savings Opportunity Scheme Regulations 2014, Schedule 1
The large-undertaking test; ISO 50001 as a compliance route.
- Financial Reporting CouncilUK Corporate Governance Code 2024
Comply or explain; Provision 29 from years beginning 1 January 2026.
- Financial Reporting CouncilISSA (UK) 5000
Effective for periods beginning on or after 15 December 2026; voluntary use.
- Financial Reporting CouncilAssurance standards
The FRC’s list of UK assurance standards.
- Financial Conduct AuthoritySustainability Disclosure Requirements (SDR) regime
Investment labels and the anti-greenwashing rule.
- FCA HandbookESG sourcebook, chapter 4
ESG 4.3.1R, the anti-greenwashing rule.
- legislation.gov.ukThe FSMA 2000 (Regulated Activities) (ESG Ratings) Order 2025 (SI 2025/1349)
Made 15 December 2025; authorisation required from 29 June 2028.
- IFRS FoundationInternational Sustainability Standards Board
Issuer of IFRS S1 and S2 and owner of the SASB Standards.
- Global Reporting InitiativeGRI Standards
Universal, Sector and Topic Standards.
- EUR-LexDelegated Regulation (EU) 2026/1563 (revised ESRS)
Applies to financial years from 1 January 2027.
- Greenhouse Gas ProtocolStandards
The corporate, Scope 2 and Scope 3 standards.
- ISOISO 14064-1:2018
Organisation-level GHG quantification and reporting.
- ISOISO 14001:2015 catalogue record (withdrawn; ISO 14001:2026 published)
The environmental management system standard and its 2026 edition.
- ISOISO 14068-1:2023 catalogue record (withdrawn 11 September 2026)
Replaced by ISO 14068:2026.
- BSIPAS 2060 carbon neutrality (withdrawn)
Verification stopped on 1 January 2025.
- Department for Energy Security and Net ZeroEnvironmental Reporting Guidelines, including SECR guidance
The government’s method guidance for SECR.
- Department for Energy Security and Net ZeroGovernment conversion factors for company reporting
The UK emission factor set.