Global sustainability standards — how the systems relate
The ISSB baseline, the EU regime and GRI — and where alignment stops.
Two systems, and a third mistaken for one
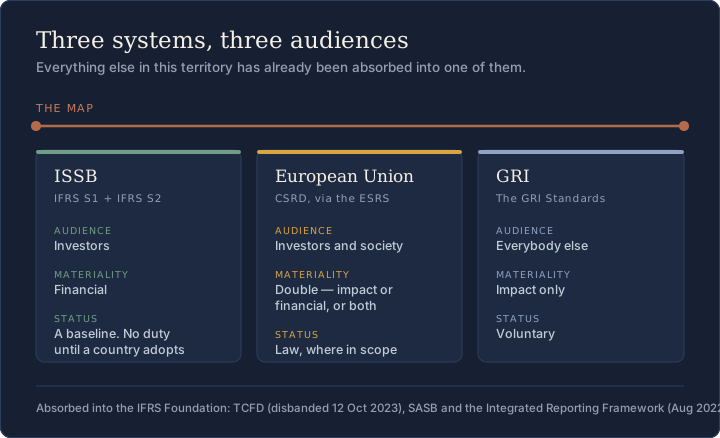
There are not a dozen global sustainability standards. There are two systems that create reporting duties, one voluntary standard-setter that is routinely confused with them, and a long tail of frameworks that have already been absorbed into one of the three.
The ISSB publishes a global baseline for investors. The European Union runs a broader statutory regime. GRI reports impacts to everybody else.
Everything else you are likely to be shown — TCFD, SASB, CDSB, the Integrated Reporting Framework — is inside one of those, and has been since 2022 or 2023. That consolidation is the single biggest thing to have happened in this territory, and most comparison tables have not caught up with it.
This page is about how the three relate, and more usefully about where they stop relating. Each system is covered in depth on its own page: the ISSB’s standards on the ISSB framework, the European regime on CSRD and the ESRS.
The question worth asking of any two of them is not “are they aligned?” but “does the alignment change a single line of what I file?”
The ISSB side — a baseline, adopted country by country
The International Sustainability Standards Board issued IFRS S1 and IFRS S2 in June 2023. S1 carries the general requirements for every sustainability topic; S2 carries climate in detail. Both are written for investors, and both are organised around the four pillars inherited from the TCFD.
The ISSB is a standard-setter, not a regulator. Its standards create no duty anywhere until a jurisdiction writes them into law or rules — which is the whole reason the adoption numbers and the mandate numbers differ so sharply.
Underneath sits the industry layer: the SASB Standards, 77 industries across eleven sectors, which the ISSB has owned since the Value Reporting Foundation consolidated into the IFRS Foundation in August 2022.
More than 45 jurisdictions have decided to use or are taking steps to introduce the standards, on the IFRS Foundation Trustees’ own count of 18 August 2026. Requirements had come into effect in 19 of them as at 24 February 2026. Those two numbers answer different questions and neither substitutes for the other.
The European side — a regime, just narrowed
The European Union does not adopt the ISSB standards. It runs its own regime: the Corporate Sustainability Reporting Directive, reported against the European Sustainability Reporting Standards, and it is law rather than a baseline anyone may choose.
It was also cut back hard in 2026. Directive (EU) 2026/470 — Omnibus I — was published in the Official Journal on 26 February 2026 and entered into force on 18 March 2026.
The scope test is now cumulative: an undertaking is caught where it exceeds a net turnover of €450 million and an average of 1,000 employees during the financial year. Both, not either.
For a UK group the question is usually the third-country limb. Under Article 40a as replaced, a non-EU parent is caught on more than €450 million of EU net turnover for each of the last two consecutive financial years, plus an EU subsidiary or branch above €200 million.
That two-year persistence test is a real filter, and the older €150 million / €40 million figures are still on the Commission’s own 2024 material and in most commentary.
The one difference every other difference follows from
Materiality. It decides what goes in the report, and the two systems answer it differently.
The ISSB applies financial materiality: information is in scope where it could reasonably be expected to affect the entity’s prospects — its cash flows, its access to finance, its cost of capital.
The ESRS apply double materiality: a matter is material where it meets the criteria for impact materiality or financial materiality, or both.
Read those twice and the practical consequence falls out. Every ISSB disclosure has an EU analogue, because financial materiality is one of the EU’s two lenses. The reverse is not true: the EU asks for a body of impact reporting that the ISSB standards never require, because no investor would price it.
This is also where the most common error in the whole territory lives, and it is worth stating flatly: GRI does not use double materiality either. The next chapter is about why.
GRI reports impacts, and not double materiality
GRI is the oldest of the three and the most widely used voluntarily. It exists to report an organisation’s most significant impacts on the economy, the environment and people, to a general audience rather than to investors.
And it applies impact materiality only. GRI says so itself, and attributes the other term to Brussels: “The European Union dubbed this concept ‘Double Materiality’”, and its own standards “represent the impact side of double materiality”.
So neither GRI nor the ISSB is a double-materiality standard on its own. The EU regime is the one that asks both questions of the same topic. A comparison table that puts “double materiality” in the GRI column is describing something that does not exist.
One more thing about GRI that summaries flatten: using the standards is not the same as reporting in accordance with them. An organisation reporting in accordance with GRI takes on nine requirements; one reporting with reference to takes on three. Both are legitimate and they are not the same claim.
GRI is also mid-renumbering, which is its own trap: since 2024 the labels GRI 101, 102 and 103 mean Biodiversity, Climate Change and Energy — not the Foundation, General Disclosures and Management Approach standards they meant before.
So much for the three systems.
What is actually aligned between the ISSB and the ESRS
There is one document that settles this, and almost nobody quotes it: the ESRS–ISSB Standards Interoperability Guidance, published jointly on 2 May 2024. Read in full it says something more precise, and more useful, than either “they are aligned” or “they are different”.
The definition is aligned. The regime is not.
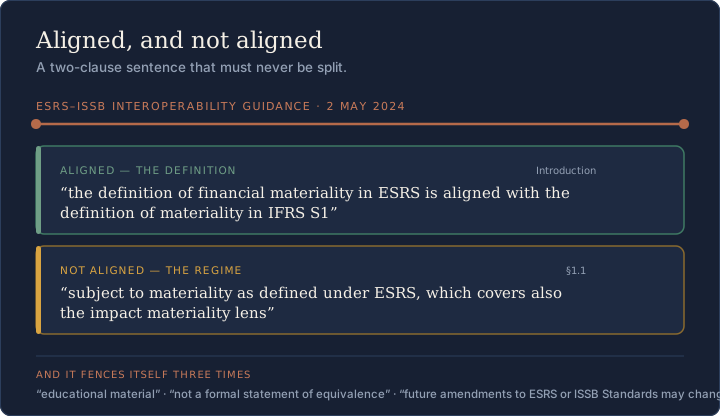
On the definition, the guidance is unambiguous. Its Introduction opens with it: “the definition of financial materiality in ESRS is aligned with the definition of materiality in IFRS S1”. And § 1.1 repeats it: “The definition of information that is considered material for users of general purpose financial reports is therefore aligned between the two sets of standards.”
On the regime, the same section is equally explicit the other way: disclosures under ESRS “are subject to materiality as defined under ESRS, which covers also the impact materiality lens” — a matter is material where it meets the criteria for “impact materiality or financial materiality, or both”.
So the sentence that survives contact with the source is a two-clause one, and it must never be split: the financial-materiality definition is aligned; the materiality regimes are not, because ESRS keeps the impact lens on top.
What that guidance does not do, in its own words
Before the fences, one correction that is repeated everywhere: the alignment was not achieved by this document, and not by EFRAG alone. It is attributed to “The International Sustainability Standards Board (ISSB) and the European Commission services, together with EFRAG”, working together during the development of both sets of standards. The guidance describes the alignment; it did not create it.
And it fences itself three times, with every fence mattering to anyone relying on it.
It is “provided as educational material”, and “does not override or adjust the requirements as set out in ESRS or ISSB Standards”.
It “is not a formal statement of equivalence. The latter is in the remit of public authorities.”
And it dates itself: “this document was published on 2 May 2024. Future amendments to ESRS or ISSB Standards may change the analysis within.”
Those three sentences are the difference between a mapping table and a legal position. An entity cannot satisfy an ESRS obligation by pointing at this guidance; it can only use it to understand why the two sets of requirements produce overlapping answers.
There is also something the guidance is routinely credited with saying and does not. “Both are built on the TCFD architecture” is a common gloss. The string TCFD appears zero times in the complete text. The claim may well be true — IFRS S2 says so about itself — but it is not evidenced by this document, and it should be sourced where it is actually stated.
The mapping expires, on a known date
This is the part with practical consequences, and it follows directly from the guidance’s own third fence.
The mapping tables cite ESRS (2023) paragraph numbers — ¶28, ¶48 and ¶131(b) of ESRS 1. On 3 July 2026 the Commission adopted a revised set of standards, and the delegated regulation does not amend Annex I: it replaces it.
A total replacement means the paragraph numbers do not survive. Every “ESRS 1 ¶n” citation needs a version qualifier from FY2027 onwards — including the ones inside the interoperability guidance.
So on the Commission’s own timetable the guidance’s tables become stale for reporting years beginning on or after 1 January 2027, unless EFRAG reissues them. EFRAG has itself named the 2 May 2024 document as the baseline it is revising against, in its cover letter to the Commission of 3 December 2025.
No reissued version has been located as at 10 September 2026 — checked against both owner mirrors and EFRAG’s own interoperability page, which still links only the 2024 version. That is a negative finding about what could be found, not a statement that none exists.
The honest planning assumption: the only published ISSB–ESRS mapping expires with the standards it maps, and a replacement has not appeared yet.
One operative mechanism, and it covers greenhouse gases
The GRI–ISSB relationship is described as interoperability far more often than it is described accurately. What exists, in full: a memorandum of understanding from 2022, a joint statement on interoperability from May 2024, a greenhouse-gas equivalence statement from June 2025, and a joint framing statement from May 2026.
Exactly one of those changes what a preparer files.
Organisations reporting under both may use the equivalent IFRS S2 disclosures for Scope 1, Scope 2 and Scope 3 to meet the corresponding GRI 102 requirements — conditional on measuring under the GHG Protocol Corporate Standard (2004) and cross-referencing in the content index. It does not bite until GRI 102 takes effect on 1 January 2027, or on early adoption.
No disclosure-level correspondence table between the two has been published by either owner as at 10 September 2026. And the two boards are explicit that they do not bind each other: they “make decisions separately in accordance with their established standard-setting due processes”.
What “report once, use many” can and cannot mean
Every standard-setter in this territory uses the word interoperability, and almost none of them define it. It is worth separating three quite different things that all travel under it.
Strong: one set of figures satisfies two requirements. The GRI greenhouse-gas equivalence is the only mechanism of that strength anywhere in this landscape.
Middle: a mapping table, which tells you which requirement corresponds to which. Useful until the standard it maps is replaced, and then a liability.
Weak: a statement of intent. Memoranda, joint framings, commitments to align. Real, and they change nothing you file.
Applied honestly, a company inside both the EU regime and an ISSB jurisdiction can build one data set and one governance process, and will still file two reports with different boundaries. The climate numbers travel. The impact reporting does not, because the ISSB standards never asked for it.
The practical test is one question: does the claimed interoperability change a single line of what you file? If it does not, it is a relationship rather than a mechanism — which is worth knowing, and worth not planning around.
What was absorbed, and what is still a live framework
Most comparison tables in this territory still list frameworks that stopped being independent years ago. Four went into the IFRS Foundation, and they went in four different ways.
The TCFD was disbanded — the FSB’s own announcement of 12 October 2023 says the 2023 status report was its final task. What moved was a monitoring duty, from 2024. No body merged into another.
The Value Reporting Foundation, which held both the SASB Standards and the Integrated Reporting Framework, consolidated into the IFRS Foundation in August 2022. The Climate Disclosure Standards Board went the same way. Their material is still published and still maintained — consolidation is not withdrawal.
And in 2026 one more piece moved: the Integrated Reporting and Connectivity Council was wound up on 31 July 2026, its mandate transferred to the IFRS Advisory Council rather than terminated. The Integrated Reporting Framework itself is untouched.
Two opposite errors are in circulation about that last one, and both are wrong: the Framework was not withdrawn, and the Council was not abolished.
Aligned on paper. Now for who must file.
Adopting a standard is not mandating it
Three facts travel under one sentence, and through 2026 they stopped moving together: whether a jurisdiction has adopted a standard, whether anyone is required to use it, and which regulator does the requiring.
The standards question has been settled in the ISSB’s favour and is still consolidating. The mandate question is diverging — by jurisdiction, and by regulator within a jurisdiction.
Brazil is the sharpest illustration, because it diverged from itself inside a month. On 29 May 2026 the securities regulator removed the obligation it had imposed on public companies, replacing it with a comply-or-explain notice duty from 1 January 2027. A company that opts in must still apply the standards in full, with reasonable assurance — so “Brazil abandoned ISSB reporting” is wrong in the other direction.
South Korea moved the opposite way: on 8 July 2026 the Financial Services Commission cut its threshold from ₩30 trillion to ₩10 trillion for 2028 reporting, with ₩5 trillion following in 2029. That is a policy decision, not a statute — the enabling amendment was not confirmed as introduced or passed.
The United States is the most misreported item of all. The 2024 climate rules were proposed for rescission on 29 May 2026 — proposed, not repealed. There has been no ruling on the merits, and the rules remain on the books, stayed and never effective.
Canada paused its work on a mandatory climate rule — on 23 April 2025, not 2026, which several 2026 commentaries get wrong. Paused is not abandoned, and the Canadian standards remain available for voluntary use.
Which is why any sentence beginning “country X has adopted the ISSB standards” is almost always insufficient on its own. It answers the first of the three facts and leaves the other two open.
The European standards were rewritten in July 2026
On 3 July 2026 the Commission adopted a revised set of European standards and a voluntary standard for undertakings protected by the value-chain cap. The scale of the cut is the headline: mandatory datapoints down by 61%, from roughly 1,144 to about 500, and total datapoints down by over 70%.
⚠ They are adopted, subject to scrutiny — not in force. Both delegated acts sit in the Parliament and Council scrutiny period, and Official Journal publication was expected in the final quarter of 2026. Anything describing them as “in force” is ahead of the register.
The application date is firmer: CSRD-scope undertakings must apply the revised standards for financial years beginning on or after 1 January 2027, with reports due in 2028. Undertakings reporting for FY2026 may early-apply them instead of the 2023 set.
One change inside is sharper than the datapoint count and is being widely missed. Under the revised ESRS 1, an undertaking “shall not disclose information prescribed by an ESRS DR or datapoint if that information is not material”. The Commission made that change deliberately, against EFRAG’s advice, replacing “is not required to” with “shall not”.
Immaterial disclosure is now prohibited, not merely unnecessary. A report padded with immaterial datapoints is no longer over-compliant; it is non-compliant.
Two things that were coming are now not coming at all. The empowerment to adopt sector-specific standards was deleted, and so was the listed-SME standard. Anyone still planning against “sector ESRS due 30 June 2026” is planning against a power that no longer exists.
European assurance is limited, and the escalation was deleted
This is the most consequential thing to have been quietly removed from the European regime, and most planning material still describes the old position.
CSRD assurance is limited assurance, full stop. The empowerment to adopt reasonable-assurance standards has been repealed.
Directive (EU) 2026/470 gives the reason in its own recitals: to avoid an increase in assurance costs, “the requirement to adopt reasonable assurance standards should be removed”. The replacement provision contains no such empowerment. There is no legislated escalation to reasonable assurance in 2028 — that describes a power that no longer exists.
The limited-assurance deadline moved too: the Commission must adopt those standards no later than 1 July 2027, up from 1 October 2026. Any page still citing the 2026 date is stale.
And what is assured is wider than most summaries say: the opinion covers the sustainability reporting, the process the undertaking carried out to identify the information reported, and compliance with the EU Taxonomy’s Article 8 disclosures.
Who may give the opinion is a 27-way answer rather than one. The default is the statutory auditor of the financial statements; Member States may allow a different auditor or firm, and may allow an independent assurance services provider subject to equivalent requirements. Both are options, not rights, and a Member State opening the door to independent providers must also open the first one.
Where the UK sits between the two systems
The UK took the ISSB baseline and endorsed it. UK SRS S1 and UK SRS S2 were published on 25 February 2026 as the UK versions of IFRS S1 and IFRS S2, with a list of amendments recorded in Annex A of the government response.
⚠ That list has no total. The government consulted on a set of proposed amendments in June 2025; some did not survive to publication and others were added, and Annex A carries no count. Any page quoting a number of UK amendments is quoting something the government did not publish.
They were issued for voluntary use. As at 10 September 2026 no UK entity is legally required to apply them; a mandate is proposed by the Financial Conduct Authority under CP26/5 for accounting periods beginning on or after 1 January 2027, subject to a Policy Statement not yet published.
That is why the IFRS Foundation lists the United Kingdom as a snapshot rather than a profile — a snapshot is explicitly a preview of proposals, published where an approach is not finalised.
So the UK is on the ISSB side of the map, and is not inside the European regime — though a UK group can still be caught by CSRD through the third-country route, on turnover earned in the EU rather than on anything about its UK reporting.
That is the map. This is how to use it.
Which system answers which question
The choice is rarely yours in full. Jurisdiction decides most of it, and what is left is decided by who is asking.
If an investor is asking what could affect the company’s prospects, the answer is built on the ISSB standards, whatever the local endorsement is called.
If a regulator in the European Union is asking, the answer is the ESRS, and it will include impact reporting the ISSB standards never require.
If a customer, an employee, a community or an NGO is asking about the company’s effect on the world, that is GRI, and neither of the other two will produce it.
For a company inside more than one of those, the workable order is: build the greenhouse-gas inventory once, on the GHG Protocol, because every system reads it; document the materiality judgement once, but record both lenses separately, because the EU needs the impact lens and the ISSB does not accept it; then produce the reports each regime actually requires.
What does not work is planning to file one document. No mechanism published by any of the three standard-setters delivers that, and the one that comes closest covers greenhouse gas figures only.
Seven things said about these systems that are not true
Each of these is in wide circulation, and each is contradicted by an owner source.
“GRI uses double materiality.” It applies impact materiality, and attributes the term to the European Union in its own words.
“The ISSB and the ESRS are aligned.” The financial-materiality definition is aligned. The materiality regimes are not, because the ESRS keep the impact lens on top.
“The interoperability guidance makes them equivalent.” It says of itself that it “is not a formal statement of equivalence”, and that it is educational material.
“CSRD catches companies with 1,750 employees.” The adopted act says €450 million and 1,000 employees. The 1,750 figure came from a political agreement and never reached the text.
“The revised ESRS are in force.” They are adopted, subject to scrutiny, and apply from financial years beginning on or after 1 January 2027.
“CSRD assurance escalates to reasonable assurance in 2028.” That empowerment was deleted outright, to hold assurance costs down.
“The ISSB absorbed the TCFD.” No body merged into another. The Task Force was disbanded and a monitoring duty changed hands.
What is still moving, and what it will change
Writing about this landscape as settled is the fastest way to be out of date. Four things are moving and none of them is finished.
The revised European standards are through adoption but not through scrutiny, and had no Official Journal number when this page was last checked.
The ISSB’s December 2025 greenhouse-gas amendments to IFRS S2 are published and not yet in force — effective for reporting periods beginning on or after 1 January 2027. The digital taxonomy update that tracks them closed for comment on 28 September 2026, and introduces no new requirement.
The SASB Standards are being rewritten underneath the ISSB standards through a series of exposure drafts, effective between twelve and eighteen months after issuance. What exists today is not what applies today.
And a European standard for third-country groups — the route by which a UK parent can be caught — went to public consultation in July 2026, with Commission adoption expected in 2027.
None of it reaches a UK reporter automatically. New or amended ISSB standards do not apply in the UK without going through endorsement first, and the FRC says so in terms.
What is left is the record.

Three standard-setters, one measurement basis, and exactly one published mechanism that lets a figure count twice. Everything else described as interoperability is a relationship between boards rather than a saving for the company filing the report.
The bottom line · Photo: Unsplash / name_gravityGlobal sustainability standards — key facts
Every figure on this page in one place, each with the date it was published.
A number without its date is not a fact about the ISSB framework — it is a fact about some month in its history.
Global sustainability standards — frequently asked questions
Materiality, and everything else follows from it. The ISSB standards apply financial materiality: information is in scope where it could reasonably be expected to affect the entity’s prospects. The ESRS apply double materiality: a matter is material where it meets the criteria for impact materiality or financial materiality, or both.
So every ISSB disclosure has a European analogue, because financial materiality is one of the EU’s two lenses. The reverse is not true.
The other difference is status. The ISSB standards are a baseline that creates no duty until a jurisdiction adopts them; the ESRS are law for undertakings in CSRD scope.
Partly, and the precise answer matters. The joint ESRS–ISSB Interoperability Guidance of 2 May 2024 states that the definition of financial materiality in the ESRS is aligned with the definition of materiality in IFRS S1.
What is not aligned is the materiality regime. The same section says ESRS disclosures are subject to materiality as defined under the ESRS, “which covers also the impact materiality lens”.
The guidance also says of itself that it is educational material and “is not a formal statement of equivalence”. It describes an alignment engineered during standard-setting; it does not create one.
Not because they are UK companies. A UK group can be caught through the third-country route in Article 40a of the Accounting Directive: more than €450 million of EU net turnover for each of the last two consecutive financial years, plus an EU subsidiary or branch above €200 million.
The two-year persistence test is a real filter, and the older €150 million and €40 million figures still circulating are superseded.
UK-domestic sustainability reporting is a separate question, answered by UK SRS S1 and S2 — issued for voluntary use on 25 February 2026, with a mandate only proposed.
They are not the same kind of thing. CSRD is a directive that creates a reporting duty; IFRS S2 is a standard that says what climate disclosure should contain. The European counterpart of IFRS S2 is ESRS E1, not CSRD itself.
On content the two climate standards are closely related, and the interoperability guidance maps them. On scope they diverge: ESRS E1 sits inside a double-materiality regime, so it asks for impact reporting that IFRS S2 does not require.
No, and GRI says so itself. It applies impact materiality only, and attributes the other term to Brussels: “The European Union dubbed this concept ‘Double Materiality’”, with its own standards representing “the impact side” of it.
Neither GRI nor the ISSB is a double-materiality standard on its own. The EU regime is the one that asks both questions of the same topic.
None of them, in themselves. Standard-setters do not create duties; jurisdictions do.
In the European Union the ESRS are mandatory for undertakings in CSRD scope — net turnover above €450 million and an average of 1,000 employees, after Directive (EU) 2026/470.
For the ISSB standards, requirements had come into effect in 19 jurisdictions as at 24 February 2026, against more than 45 that have decided to use them or are taking steps towards them. Those two numbers answer different questions.
All three are inside the IFRS Foundation, and they went in different ways. The TCFD was disbanded on 12 October 2023 and a monitoring duty transferred from 2024 — no body merged into another.
The Value Reporting Foundation, which held the SASB Standards and the Integrated Reporting Framework, consolidated into the IFRS Foundation in August 2022, as did the Climate Disclosure Standards Board. Their material is still published and maintained.
The SASB Standards remain live and cover 77 industries across eleven sectors. IFRS S1 and S2 point at them directly.
Not as a single filing. No mechanism published by any of the standard-setters delivers that.
What is achievable is one data set and one governance process feeding two reports. The greenhouse-gas figures travel, because every system reads the GHG Protocol. The impact reporting does not, because the ISSB standards never asked for it.
The test worth applying to any interoperability claim: does it change a single line of what you file? If not, it is a relationship rather than a mechanism.
The Commission adopted a revised set on 3 July 2026. Mandatory datapoints fall by 61%, from roughly 1,144 to about 500, and total datapoints by over 70%.
⚠ They are adopted subject to scrutiny rather than in force, and apply for financial years beginning on or after 1 January 2027. Undertakings reporting for FY2026 may early-apply them.
One change inside is easy to miss: an undertaking now “shall not disclose” information that is not material, where the previous text said it was not required to. Immaterial disclosure is prohibited rather than merely unnecessary. Sector-specific standards and the listed-SME standard were both deleted.
On the ISSB side. UK SRS S1 and UK SRS S2 are the UK’s endorsed versions of IFRS S1 and IFRS S2, published on 25 February 2026 for voluntary use.
The differences are recorded in Annex A of the government response, which carries no total — so any count quoted for the UK amendments is not the government’s figure.
The IFRS Foundation lists the United Kingdom as a snapshot rather than a profile, because a snapshot is what it publishes where a jurisdiction’s approach is not yet final.
Global sustainability standards — primary sources
Every figure and legal statement on this page carries a citation.
These are the primary documents behind them, re-verified on 10 September 2026.
The interoperability question
The ISSB side
The European regime
GRI
The mandate question
The consolidated frameworks, and the UK
Go deeper on global sustainability standards
The ISSB Framework
IFRS S1 and S2, the four pillars, and who has actually adopted them.
The comparisonCSRD vs UK SRS
The two regimes set against each other, requirement by requirement.
The EU standardsThe ESRS
What the European Sustainability Reporting Standards ask for, and who they catch.
MaterialityDouble Materiality
The fork every other difference follows from, and who actually applies it.
The UK pairUK SRS S1 and S2
The UK’s endorsed standards, and what endorsement changed.
The climate standardIFRS S2
The climate standard the UK endorsed, requirement by requirement.
The landscapeESG Frameworks in the UK
Which framework answers which question, and for whom.
The inheritanceTCFD and UK SRS
The four pillars every later standard is built on.
NatureTNFD
The nature-related framework, and where the ISSB’s own work has reached.