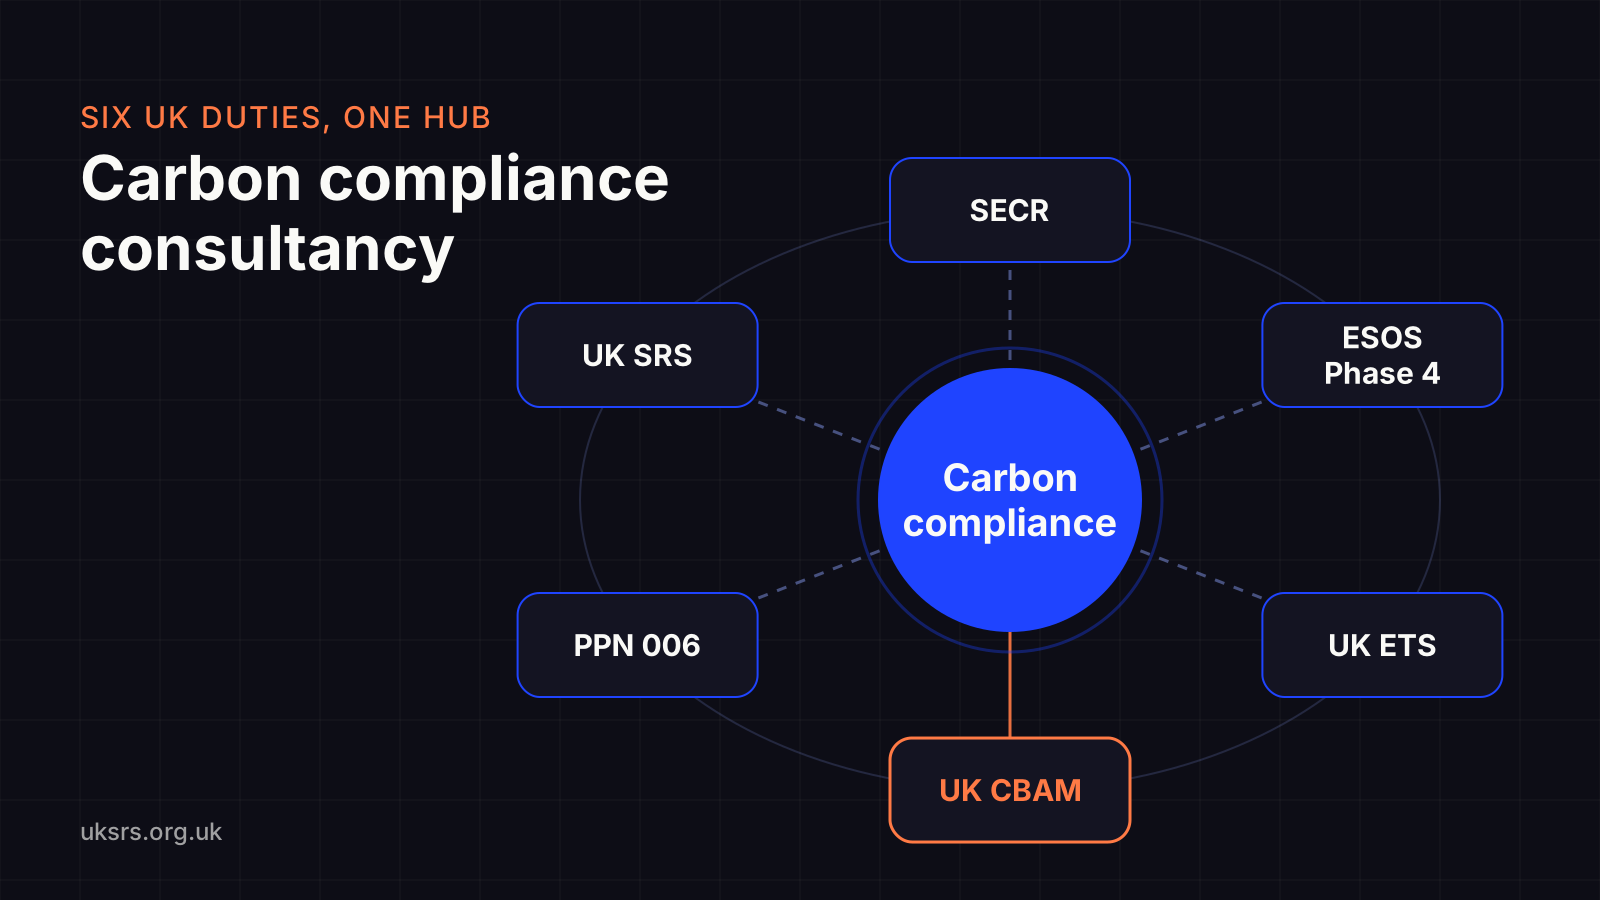
Carbon compliance · six UK duties
Carbon compliance consultancy UK
Identify the duty, responsible entity and required output. A consultant can support the work, but the organisation still owns its compliance decisions and evidence.
UK SRS is an independent reference site. We have assessed no consultancy and publish no consultancy prices or rankings.
- UK ETSships of 5,000 GT and above covered from1 Jul 2026
- ESOSlead assessor seven-day notice in force22 Jul 2026
- FCA PS26/19UK SRS final rules published30 Sep 2026
- ESOS Phase 4qualification date31 Dec 2026
- UK CBAMcharge begins1 Jan 2027
- UK SRScomply-or-explain periods begin1 Jan 2027
- ESOS Phase 4compliance notified by5 Dec 2027
- UK CBAMfirst returns and payment due31 May 2028
The map
What carbon compliance consultancy covers
SECR: Annual energy and carbon disclosure. ESOS: Assessment, notification and action reporting.
Read the detailed guidance and references
| Duty | Who it reaches | What it asks for | Who may do the work |
|---|---|---|---|
| SECR | Quoted companies at any size; unquoted companies and LLPs that fail the exemption | Energy use, emissions, an intensity ratio and efficiency measures in the annual report | Anyone; no credential or assurance required |
| ESOS Phase 4 | Large undertakings on 31 December 2026 | An energy assessment, notified by 5 December 2027 | A lead assessor on an approved register reviews it; directors sign off |
| UK ETS | Regulated installations, aircraft operators and ships of 5,000 GT and above | A monitoring plan, a verified annual emissions report and allowances surrendered | A verifier accredited by UKAS to ISO 14065 |
| UK CBAM | Importers of specified aluminium, cement, fertiliser, hydrogen, and iron and steel goods | Registration, returns and a charge on embodied emissions from 1 January 2027 | The importer is liable; a tax agent can file but cannot register |
| PPN 006 | Bidders for in-scope central government contracts above £5m a year | A Carbon Reduction Plan: Scope 1, 2 and five Scope 3 categories | Anyone; the board signs it off |
| UK SRS | Listed companies in UKLR 6, 14, 15, 16 and 22 | Climate and wider disclosures, or an explanation, for periods from 1 January 2027 | Anyone; assurance not required, and a provider is named if used |
A carbon compliance consultancy earns its fee on the first column and the last: deciding which duties bite, and making sure the right person checks and signs.
The calculations in the middle are often the easy part, and software can carry much of that load.
The wider market, including measurement and reduction work, is covered in the general carbon consultancy guide.
Each row is a different rule with a different trigger, and the last column is the one most proposals leave out.
Most organisations are under one or two of these duties; very few are under all six.
Module 01 / 04
SECR
Module 02 / 04
ESOS
Module 03 / 04
UK ETS
Module 04 / 04
Procurement
Run the tests
Which obligations apply to you?
Enter one year’s figures and tick what you do, and the panel runs all six tests together.
It reads each test as its instrument writes it: SECR’s exemption of “not more than” conditions, ESOS’s “at least 250 employees, or both money limbs exceeded”, and the FCA’s listing categories for UK SRS.
Read the detailed guidance and references
Every result names who may do the work, because that is what decides whether you need a carbon compliance consultant at all.
It cannot aggregate a group for SECR or check a commodity code, so treat a close result as a reason to check the provision.
The size tests for each regime are set out on who is in scope for UK SRS and the SECR overview.
Six UK duties · one set of answers
1 of 6 duties apply on these answers.
In scope: the figures meet only 1 of the three “not more than” conditions, so the exemption is lost.
Who can do it: No credential is required: finance, software or a consultant can prepare it, and the law does not require assurance.
SI 2008/410 Sch 7 ¶20B
Not large on these figures, but the test is taken on 31 December 2026 and across the whole UK group, so a parent or subsidiary can change the answer.
Who can do it: A lead assessor from one of the approved registers must review the assessment, unless total energy use is under 40,000 kWh or ISO 50001 covers it; directors sign off.
EA, How to comply with ESOS Phase 4
Only operators of regulated installations, aircraft and, since 1 July 2026, ships of 5,000 gross tonnage and above are in the scheme.
Who can do it: The verifier must be accredited by UKAS to ISO 14065 and the Verification Regulation, for the activity reported.
GOV.UK, UK ETS for installations: how to comply; SI 2026/392
UK CBAM reaches importers of specified aluminium, cement, fertiliser, hydrogen, and iron and steel goods.
Who can do it: The importer is liable; a tax agent can file returns but cannot register for you, and actual emissions data must be verified.
Finance Act 2026 (2026 chapter 11), Part 5 and Schedule 17 paragraph 2; SI 2026/830
No duty: a Carbon Reduction Plan is asked for only when you bid for an in-scope contract above £5 million a year.
Who can do it: Anyone may prepare it, and the board of directors or equivalent body signs it off.
Cabinet Office, PPN 006 and Technical Standard
Outside the FCA’s five categories UK SRS is voluntary.
Who can do it: No credential is required; assurance is not required, and if obtained the report names the provider.
FCA PS26/19 ¶¶1.2, 3.6, 3.12
A map of what the rules ask, not legal advice.
It does not aggregate a group for SECR or check commodity codes.
Nothing you enter leaves your browser.
Module 01 / 04
Entity
Module 02 / 04
Activity
Module 03 / 04
Scope
Module 04 / 04
Output
The thresholds
Five numbers that decide scope
More than: An exact boundary may be outside. Not more than: Equality can satisfy a condition.
Read the detailed guidance and references
ESOS’s own 40,000 kWh line is “less than”, not “or less”, so a participant at exactly 40,000 kWh still appoints a lead assessor (SI 2014/1643 reg 21(3)).
Module 01 / 04
More than
Module 02 / 04
Not more than
Module 03 / 04
Combination
Module 04 / 04
Period
SECR
SECR: no credential, no assurance duty
Streamlined Energy and Carbon Reporting puts energy and emissions figures in the directors’ report every year, so its deadline is the filing deadline.
A quoted company reports at any size, and a company traded only on AIM is not a quoted company under section 385.
Read the detailed guidance and references
No credential is needed to prepare it, and the government’s guidelines say there is no statutory requirement to have the figures assured.
The government’s 2026 evaluation counted 19,900 organisations in scope.
What to look for in outside help is on the SECR consultancy page.
An unquoted company is exempt if it meets two or more of: turnover not more than £36 million, balance sheet not more than £18 million, not more than 250 employees.
After the first year, status changes only when the new position holds for two consecutive years.
Source: SI 2008/410 Sch 7 ¶20B
Module 01 / 04
Scope
Module 02 / 04
Inputs
Module 03 / 04
Narrative
Module 04 / 04
Report
ESOS Phase 4
ESOS Phase 4: a register decides
A large undertaking employs at least 250 people, or has turnover over £44 million and a balance sheet over £38 million, and group aggregation applies.
Size is taken on 31 December 2026, and compliance is notified by 5 December 2027, according to the Environment Agency’s Phase 4 guidance.
Read the detailed guidance and references
The assessment must be reviewed by a lead assessor from one of the seven approved registers, and checking the register is the organisation’s job, not the assessor’s.
Since 22 July 2026 the 2026 amendment regulations also require the lead assessor to notify their approval body within seven days of finishing.
The assessors themselves are described on ESOS consultants and lead assessors.
Module 01 / 04
Qualification
Module 02 / 04
Assessment
Module 03 / 04
Notification
Module 04 / 04
Follow-up
UK ETS and UK CBAM
Traded and border regimes: emissions with a price
The UK ETS is the one regime here where verification is a legal duty: the compliance guidance requires a verifier accredited by UKAS to ISO 14065, with a scope covering the activity reported.
From 1 July 2026 it covers ships of 5,000 gross tonnage and above, under SI 2026/392.
Read the detailed guidance and references
UK CBAM is a tax, not a disclosure: Part 5 of the Finance Act 2026 charges specified imports in five sectors from 1 January 2027.
Registration is triggered at £50,000 or more of CBAM goods, and for anyone triggering it in 2027 the transitory regulations set 31 January 2028 to register and 31 May 2028 for the first return.
The charge rests on embodied emissions, using verified supplier data or a government default, according to HMRC’s policy summary.
The schemes are explained on the UK ETS guide and the UK CBAM page.
Module 01 / 04
UK ETS
Module 02 / 04
UK CBAM
Module 03 / 04
Evidence
Module 04 / 04
Advice
PPN 006 and UK SRS
Procurement and listing: policy, then comply or explain
PPN 006 binds in-scope contracting authorities, which ask bidders on contracts above £5 million a year for a Carbon Reduction Plan as a condition of participation.
The Technical Standard asks for Scope 1 and 2 in full and only five Scope 3 categories, and the board signs the plan off.
Read the detailed guidance and references
The plan itself is set out on Carbon Reduction Plans under PPN 006.
Under the FCA’s PS26/19, listed companies in UKLR 6, 14, 15, 16 and 22 report against UK SRS on a comply-or-explain basis for periods beginning on or after 1 January 2027.
The standards are voluntary for every other organisation, and the FCA rules are explained on UK SRS and the FCA.
Module 01 / 04
Reporting rule
Module 02 / 04
Listing rule
Module 03 / 04
Procurement
Module 04 / 04
Commitment
The calendar
The dates that drive the work
Two dates matter more than the rest for a buyer in 2026.
The ESOS snapshot on 31 December 2026 fixes who is in Phase 4, whatever happens to headcount afterwards.
Read the detailed guidance and references
The CBAM charge runs from 1 January 2027 even though nobody can register until 2028, so supplier data for 2027 imports is needed before the register opens.
The ESOS dates in full are on ESOS deadlines.
- 1 July 2026UK ETS reaches shippingShips of 5,000 gross tonnage and above, whatever their flag.SI 2026/392
- 22 July 2026ESOS amendments in forceLead assessors notify their approval body within seven days of an assessment.SI 2026/701
- 1 January 2027UK CBAM begins, and UK SRS periods startThe CBAM charge runs from this day; listed companies in scope report for periods beginning on or after it.Finance Act 2026 Part 5; FCA PS26/19 ¶3.12
- 5 December 2027ESOS Phase 4 compliance dateNotification of compliance to the Environment Agency.Environment Agency
- 31 January 2028CBAM registration deadlineFor anyone who triggers registration during 2027.SI 2026/830 reg 2(2)
- 31 May 2028First CBAM return and paymentFor the twelve-month accounting period ending 31 December 2027.SI 2026/830 reg 2(4)
Module 01 / 04
Qualification
Module 02 / 04
Period start
Module 03 / 04
Compliance
Module 04 / 04
Follow-up
How the work runs
How a carbon compliance consultant runs the work
Organisation: Own scope decisions and source records. Consultant: Prepare the agreed calculations or documents.
Read the detailed guidance and references
- figures
- activity data
- calculations
- checked figures
- signed document
Run each instrument’s own test on your figures and activities, because the six use different thresholds and dates.
The check stage is the only one where the law can rule a provider out, so a carbon compliance consultancy should say at the start who will do it.
The sign stage never moves to the consultant, because the duty and the signature stay with the organisation.
Where the job is cutting emissions rather than reporting them, the carbon reduction consultancy page is the better start.
One engagement can serve several duties, as long as each stage is done to the strictest of them.
Module 01 / 04
Organisation
Module 02 / 04
Consultant
Module 03 / 04
Specialist
Module 04 / 04
Approver
Before you call anyone
Buying carbon compliance consultancy well
Name the duties in the first line of the brief, with the figures the tests use.
Ask who will hold any credential the law names, and check the register or the UKAS schedule yourself.
Read the detailed guidance and references
Ask for days by grade for each duty, and for year two in the same proposal.
Ask who owns the calculation files at the end, so a different provider could repeat the work.
A carbon compliance consultancy that will not answer those questions in writing has not yet understood the brief.
This site publishes no prices, and the government’s SECR evaluation put the mean ongoing cost of SECR alone at £7,100 a year, internal and external together.
The selection process is in how to choose a sustainability consultant, or you can book a free 15-minute call.
Module 01 / 04
Provision
Module 02 / 04
Deliverable
Module 03 / 04
Dependencies
Module 04 / 04
Exclusions
Illustrative brief · no consultancy assessed
A worked brief: one organisation faces several carbon duties
Assume the separate scope tests establish SECR and ESOS applicability. Commission an annual-report workstream and a scheme-assessment workstream with distinct outputs and approvals.
For the detailed requirements, see SECR consultancy.
View the workflow diagram
- 1
SECR
Calculation working and annual-report disclosures.
- 2
ESOS
Assessment route, notification and follow-up information.
- 3
Coordination
Reuse inputs while preserving the different boundaries.
Each date has a different meaning
The relevant dates, in order
Check who the date applies to and whether it is publication, application, submission or a planned milestone.
- 22 July 202601
- 5 December 202602
- 31 December 202603
- 5 December 202704
- 5 December 202805
A suggested delivery sequence
From the brief to the handover
This is an editorial buying and preparation sequence, not a statutory timetable or a promise about how long the engagement takes.
- 01 / Scope01
Scope
Identify the obligation, assets and operating boundary. - 02 / Assessment02
Assessment
Collect evidence and assess the technical options. - 03 / Decision03
Decision
Compare feasibility, investment and dependencies. - 04 / Delivery04
Delivery
Assign owners and sequence the chosen actions. - 05 / Review05
Review
Monitor outcomes and complete applicable reporting.
Frequently asked
Carbon compliance, answered
What is carbon compliance consultancy?
Carbon compliance consultancy is help meeting the UK rules that put a carbon or energy duty on an organisation: SECR in the annual report, ESOS energy assessments, the UK ETS, UK CBAM on certain imports from 1 January 2027, Carbon Reduction Plans under PPN 006 and, for listed companies, UK SRS on a comply-or-explain basis.
Each has its own test and deliverable, and only two name a credential.
What does a carbon compliance consultant do?
A carbon compliance consultant works out which duties apply, gathers the energy and fuel data, calculates emissions to the method each duty requires, and prepares the disclosure, return or plan for the person who must sign it.
Where the law names a credential, as ESOS and the UK ETS do, the consultant either holds it or brings in someone who does.
Do I need a carbon compliance consultant for SECR?
Not by law.
No credential is required to prepare a SECR disclosure and the figures need not be assured.
Many companies prepare SECR in-house or with software, and use outside help in the first year, for a group, or where the method will be scrutinised.
Which UK carbon rules require an accredited verifier?
The UK ETS: the verifier must be accredited by UKAS to ISO 14065 and the Verification Regulation, for the activity reported.
ESOS needs a lead assessor from an approved register rather than a verifier.
SECR, PPN 006 and UK SRS require neither.
When does UK CBAM start and who pays it?
UK CBAM applies from 1 January 2027, under Part 5 of the Finance Act 2026, to specified aluminium, cement, fertiliser, hydrogen, and iron and steel goods.
The importer is liable.
A person who triggers registration in 2027 registers by 31 January 2028, and the first return and payment are due by 31 May 2028.
Is a Carbon Reduction Plan a legal requirement?
No. PPN 006 binds in-scope contracting authorities, which ask bidders for a Carbon Reduction Plan as a condition of participation on contracts above £5 million a year.
A company that does not bid for those contracts has no duty to hold one.
Do listed companies have to report under UK SRS?
On a comply-or-explain basis.
Under the FCA’s final rules in PS26/19, listed companies in UKLR 6, 14, 15, 16 and 22 report against UK SRS on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027.
For everyone else UK SRS is voluntary.
How much does carbon compliance consultancy cost?
This site publishes no prices and does not estimate fees.
Ask for a written scope with days by grade for each duty.
The government’s SECR evaluation measured a mean ongoing compliance cost of £7,100 a year, internal and external together.
What is the difference between carbon compliance and carbon consultancy?
Carbon consultancy is the wider market: measuring emissions, meeting the rules and reducing them.
Carbon compliance is the part with legal edges, meaning deadlines, prescribed content and in two regimes a named credential.
Sources
Primary sources
Every figure, date and status on this page traces to the instrument’s owner.
Secondary commentary is never the source for a number.
- legislation.gov.ukSI 2008/410 Schedule 7, Parts 7 and 7A (SECR)
What quoted companies and large unquoted companies report.
- legislation.gov.ukSI 2008/410 Schedule 7 paragraph 20B
The exemption: two or more of the “not more than” conditions, judged over two years after the first.
- legislation.gov.ukCompanies Act 2006, section 385
What a quoted company is.
- Defra / BEISEnvironmental Reporting Guidelines including SECR guidance (2019)
No statutory requirement to have SECR figures assured.
- Department for Energy Security and Net ZeroIndependent evaluation of SECR (2026)
19,900 organisations in scope; mean ongoing cost of £7,100 a year.
- Environment AgencyHow to comply with ESOS Phase 4
The size test, the dates and the lead assessor duty.
- GOV.UK (Environment Agency)ESOS: approved lead assessor registers
The seven professional bodies that keep approved registers.
- legislation.gov.ukSI 2014/1643 regulation 21
No lead assessor where total energy consumption is less than 40,000 kWh.
- legislation.gov.ukThe ESOS (Amendment) Regulations 2026 (SI 2026/701)
The lead assessor’s seven-day notice, from 22 July 2026.
- GOV.UKUK ETS for installations: how to comply
The verifier must be accredited by UKAS to ISO 14065 and the Verification Regulation.
- legislation.gov.ukSI 2026/392 — UK ETS extension to maritime activities
Ships of 5,000 gross tonnage and above from 1 July 2026.
- legislation.gov.ukFinance Act 2026 (2026 c. 11), Part 5
The charge to UK CBAM on goods in five sectors.
- legislation.gov.ukFinance Act 2026, Schedule 17 paragraph 2
Registration is triggered by £50,000 or more of CBAM goods.
- legislation.gov.ukThe CBAM (Transitory Provision) Regulations 2026 (SI 2026/830)
Registration by 31 January 2028; first return and payment by 31 May 2028.
- HM Revenue & CustomsCarbon border adjustment mechanism: policy summary
Commencement, the liable person and how liability is worked out.
- Cabinet OfficePPN 006 — Carbon Reduction Plans
A condition of participation for in-scope contracts above £5 million a year.
- Cabinet OfficePPN 006 Technical Standard for Carbon Reduction Plans
Scope 1 and 2 in full and five Scope 3 categories.
- Financial Conduct AuthorityPS26/19: Aligning listed issuers’ sustainability disclosures with international standards
Comply or explain across UK SRS for five listing categories.
- Financial Conduct AuthorityPS26/19 (PDF), ¶¶1.2, 3.6, 3.12, 3.14
The categories, the start date and the reliefs.
- Department for Business and TradeUK SRS S1 and UK SRS S2
Published 25 February 2026, available for voluntary use.
Continue reading
Read next
The general consultancy guide
Measurement, rules and reduction in one market.
SECR consultants
What outside help with SECR is worth.
ESOS lead assessors
The registers, the duties and the dates.
ISO 14001 consultant
What a consultant does, and what the certification body must not.
Sustainability consulting firms
Selection criteria tied to the law, and an unranked A–Z directory.