Net zero consultancy UK · consultants and consulting services
Net zero consultancy and consultants
A net zero consultancy measures an organisation’s emissions, sets targets to cut them and writes the plan that delivers the cuts.
Net zero consultants turn that baseline into targets, a sized pathway and a transition plan with owners, dates and costs.
Net zero consulting also covers what UK rules ask, from the FCA transition plan statement to PPN 006.
Net zero consultancy · definition
What a net zero consultancy does: a plan someone owns
A net zero consultancy measures emissions to the GHG Protocol standards, sets reduction targets, sizes the actions that meet them and writes a transition plan with owners, dates and costs.
Net zero consultants then support delivery and the annual check of progress against the plan.
Separate the measured baseline from the strategy and delivery work. A useful proposal names the output, owner and acceptance test for each stage.
Explore the delivers guidance and tools
Net zero consultancy decides how far and how fast to cut emissions.
Then it plans the cuts in enough detail that they happen.
“Net zero consultant”, “net zero consultancy” and “decarbonisation consultancy” describe the same market.
Baseline
A footprint looks back over one year.
Net zero work takes it as its input.
Price it separately
The baseline
Has an objective standard behind it.
Price it separately
The strategy
Does not.
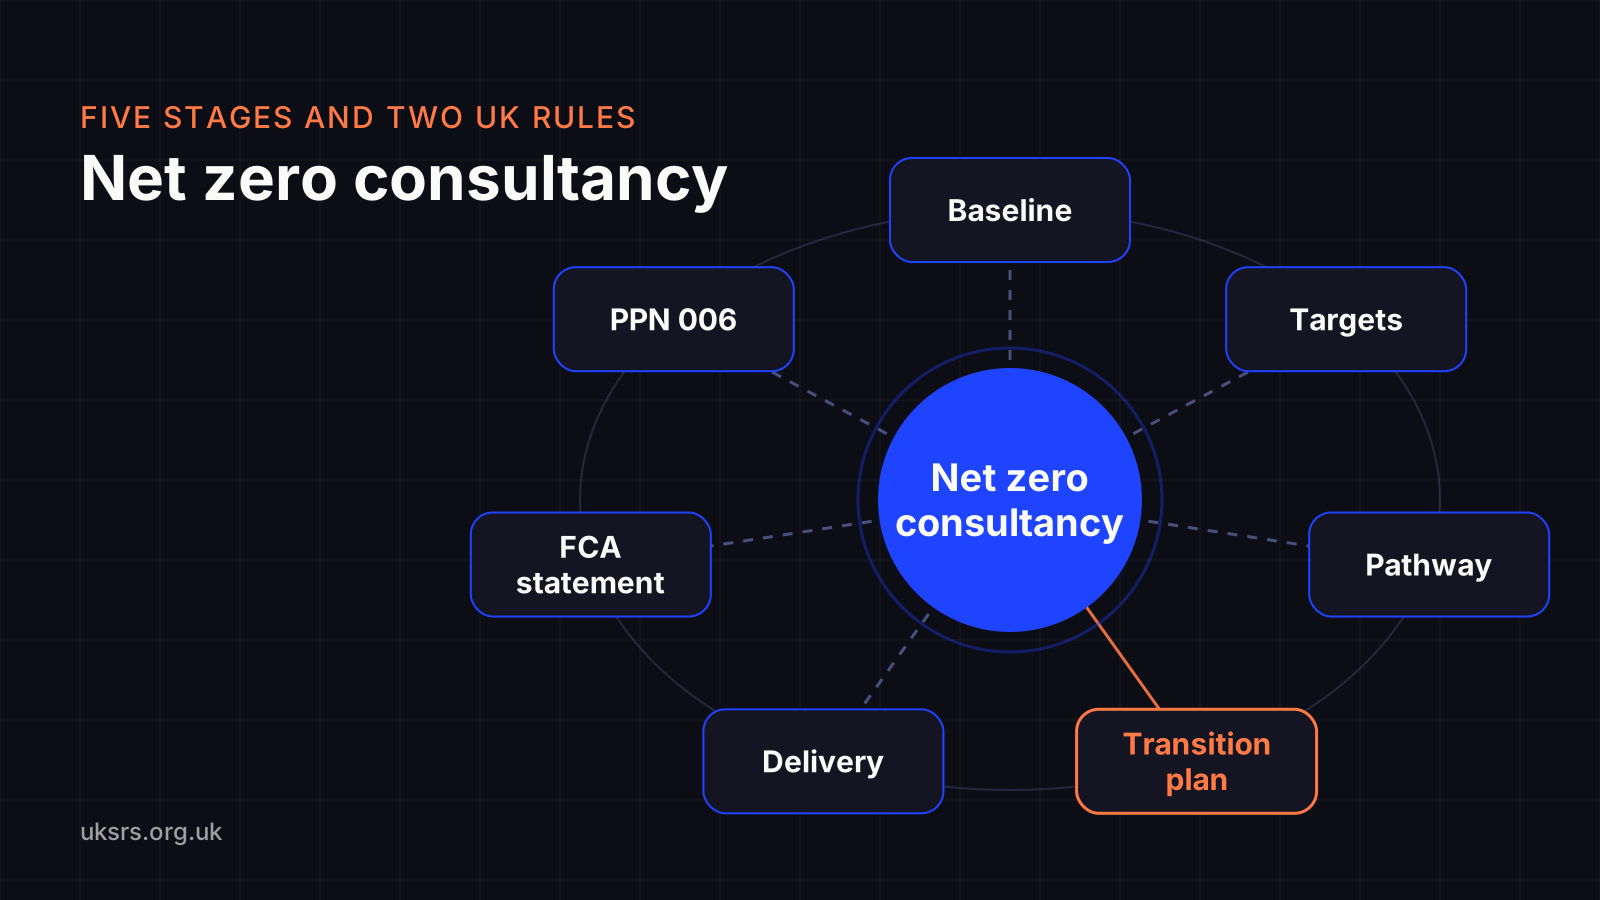
The work starts with the same inventory a carbon footprint consultant builds, and adds targets, a pathway, a written transition plan and support with delivery.
What distinguishes it from carbon consultancy is duration.
Many firms sell both, and the honest test of a proposal is whether the baseline and the strategy are scoped and priced separately.
Five outputs, one accountable plan
Baseline
Five outputs, one accountable plan
Targets
Five outputs, one accountable plan
Pathway and plan
Five outputs, one accountable plan
Delivery
Net zero consulting · services
Net zero consulting services and the standards behind them
Net zero consulting is six pieces of work: a carbon footprint, targets, a decarbonisation roadmap, a transition plan, compliance disclosures and, where wanted, verification.
Each has a published standard behind it, and only some of them answer a UK rule.
| Service | What you receive | The standard behind it | The UK rule that reaches it |
|---|---|---|---|
| Carbon footprint (baseline) | A Scope 1, 2 and 3 inventory with a stated boundary and base year | GHG Protocol: Scope 1 and 2 at minimum; the Scope 3 Standard’s 15 categories | SECR for quoted and large companies; UK SRS S2 asks for absolute gross Scope 1, 2 and 3; PPN 006 asks for Scope 1, 2 and five Scope 3 categories |
| Science-based targets | Near-term and long-term targets, prepared for submission | SBTi Corporate Net-Zero Standard V1.3.1; V2.0 validation opens 1 February 2027 | None: targets are voluntary and SBTi Services validates them |
| Decarbonisation roadmap | Reduction actions, sized and sequenced against the targets | SBTi near-term minimum of 4.2% a year for Scope 1 and 2, as a reference line | ESOS Phase 4 for large undertakings: an action plan due 5 December 2028 |
| Transition plan | Actions tied to owners, dates and capital | TPT materials, voluntary guidance now held by the IFRS Foundation | The FCA statement for UKLR 6, 16 and 22: whether a plan is published, where, or why not; UK SRS S2 ¶14 |
| Compliance and disclosure | UK SRS S2 climate disclosures, a Carbon Reduction Plan, an SECR report | UK SRS S2; the PPN 006 template; Schedule 7 of SI 2008/410 | FCA comply or explain across UK SRS for UKLR 6, 14, 15, 16 and 22, periods from 1 January 2027; PPN 006 above £5m a year |
| Verification | An independent statement on the inventory | ISO 14064-3, by a body accredited under ISO 14065 | Not required for SECR reporting |
Net zero consultants · by organisation
Net zero consultants by organisation type
What you need from net zero consultants depends on what kind of organisation you are, because different UK rules reach each one.
A reporting deadline, a procurement bid and an engineering programme need different briefs.
| Organisation | What it usually needs | The rule that applies |
|---|---|---|
| SME | A first carbon footprint, often because a customer or a public buyer asked for one | SECR and ESOS reach quoted, large and large-undertaking businesses, not most SMEs; the SBTi has a separate SME route for companies that meet its tests, including under 10,000 tCO2e across Scope 1 and location-based Scope 2 |
| Large or listed company | A full inventory, targets, a transition plan and the climate disclosures | SECR; ESOS Phase 4 at 250 or more employees, or turnover above £44m and a balance sheet above £38m, notified by 5 December 2027; for listed companies, FCA comply or explain across UK SRS from periods beginning 1 January 2027 |
| Public-sector supplier | A Carbon Reduction Plan for the bid, signed off by the board and published on its website | PPN 006: central government contracts above £5m a year including VAT, with a commitment to net zero by 2050 in the UK |
| Building developer | Operational energy and carbon sized per building, and often a whole-life carbon assessment | The Building Regulations: the Future Homes and Buildings Standard applies in England from 24 March 2027; embodied carbon is not regulated in England, and Part Z is a proposal |
Explore the intent guidance and tools
Different readers bring different decisions and deadlines.
Pick the role closest to yours.
They need
A credible pathway
Targets, a sized pathway and a plan the board will fund.
Searches like · net zero carbon pathway advice
See the five stages →Start with the decision
Board review
Net zero consulting · by goal
Net zero consulting by goal: measure, comply or cut energy cost
Start from the goal: measuring emissions, meeting a rule or cutting the energy bill each sends net zero consulting to a different first piece of work.
| Your goal | The first piece of work | The guide to read |
|---|---|---|
| Measure | A Scope 1, 2 and 3 inventory on the GHG Protocol | Carbon footprint consultancy, and the Scope 3 emissions categories |
| Comply | The disclosure the rule asks for: climate reporting, an energy and carbon report, or a Carbon Reduction Plan | UK SRS S2 for listed companies, and the SECR requirements for the directors’ report |
| Cut energy cost | An energy assessment that finds and sizes the savings | ESOS Phase 4 for large undertakings, and the ESOS energy audit itself |
Net zero consultancy · duty
Net zero consultancy and UK law: the national target and company duties
The Climate Change Act puts the 2050 target on the Secretary of State. Check the separate reporting rules, procurement conditions and commitments that reach your organisation.
Explore the duty guidance and tools
Section 1 of the Climate Change Act 2008 puts the 2050 duty on the Secretary of State.
The national target does not itself require a company transition plan.
The government’s 2025 consultation is a separate policy process; check its outcome and any resulting legislation separately.
Three narrower things do reach companies.
Test which reach yours.
2050 net zero: a duty on the Secretary of State
No duty to have a plan
1
of 3 reach you
Three separate routes
National target
Three separate routes
Listed company statement
Three separate routes
Procurement condition
Three separate routes
Voluntary commitment
Dates with different meanings
Publication, application and submission
Do not treat every date as the same kind of deadline. FCA rules use the financial-year start; SBTi’s transition guide governs corporate target submissions.
- 2008 / target amended in 201901
Climate Change Act
The national 2050 target is a duty on the Secretary of State. - 25 February 202602
UK SRS published
Available for voluntary use; application depends on the reporting route. - 30 September 202603
- Periods from 1 January 202704
FCA statement applies
UKLR 6, 16 and 22 state whether a transition plan is published, where, or why not. - 1 February 202705
V2.0 validation opens
General corporate submissions may use V1.3.1 or V2.0 during the transition. - 31 January 202806
V1.3.1 submissions close
From 1 February 2028, new corporate submissions use V2.0.
Explore the date tracker and detailed references
06 / The net zero timeline
Every date a net zero consultant should quote
2008 · passed
Law
Climate Change Act 2008
Net UK carbon account at least 100% below 1990 by 2050.
A duty on the Secretary of State.
25 Jun 2025 · passed
Government
Transition plan consultation opens
Ran to 17 September 2025.
Consultation proposals are separate from the applicable reporting rules.
25 Feb 2026 · passed
UK SRS
UK SRS S1 and S2 published
S2 ¶14(a)(iv) covers transition plan information.
11 Jun 2026 · passed
SBTi
Corporate Net-Zero Standard V2.0 published
V1.3.1 remains operative.
11 Sept 2026 · passed
Claims
ISO 14068-1:2023 withdrawn
Successor ISO 14068:2026 under publication as checked on 10 October 2026.
PAS 2060 already withdrawn.
24 Sept 2026 · passed
FCA
Final rules made, PS26/19
The transition plan statement for UKLR 6, 16 and 22.
Published 30 September.
1 Jan 2027 · in 76 days
FCA
Statement periods begin
Accounting periods beginning on or after this date.
1 Feb 2027 · in 107 days
SBTi
V2.0 corporate validation opens
General corporate submissions can use either version through 31 January 2028.
31 Jan 2028 · in 471 days
SBTi
Last V1.3.1 submissions
V2.0 only thereafter.
2050 · in 24 years
Law
The 2050 target
National, not corporate.
Free · 15 minutes · video or phone
Fifteen minutes, free.
Bring your baseline year and your deadline.
Net zero consultancy · statement
What the FCA statement actually says
The rule asks whether a climate transition plan has been published and where, or why not. It does not require these listed companies to publish a plan.
Explore the statement guidance and tools
Companies in UKLR 6, 16 and 22 say whether they have published a transition plan, and where.
Or why not.
From periods beginning on or after 1 January 2027, under PS26/19.
There is no duty to have a plan.
Plan
Where a reader finds it
A drafting aid in plain words, not FCA model wording.
Nothing is stored or sent.
Draft statement · UKLR 6
The Company has published a climate-related transition plan. It is set out in [section] of this annual financial report.
Rule · UKLR 6.6.6R(8)(e) and its UKLR 16 and 22 equivalents · PS26/19 ¶2.37
A company reporting against UK SRS S2 also discloses information about any transition plan it has, under ¶14(a)(iv).
The consultation behind the rules, CP26/5, said that mandating transition plans is a matter for government.
The disclosure in depth is on UK SRS transition plans.
The standards themselves are on UK SRS S1 and S2, published by DBT on 25 February 2026.
A statement, not a plan mandate
Not published
A statement, not a plan mandate
Other categories
A practical delivery sequence
Net zero consulting, stage by stage: evidence to delivery
Agree a handover and acceptance test at each stage. Dates and consultant days should come from the proposed scope, rather than an invented industry timetable.
- 01 / Baseline01
Fix the boundary
Document the year, entities, activities and sources. - 02 / Targets02
Select the criteria
Record the applicable SBTi route and submission version. - 03 / Pathway03
- 04 / Transition plan04
- 05 / Delivery05
Explore the stages guidance and tools
The baseline follows the GHG Protocol.
Targets, the SBTi’s criteria.
Plan content, the TPT materials as voluntary guidance.
The transition plan should connect proposed actions to capital allocation and accountable owners.
Stage 01
Baseline
A Scope 1, 2 and 3 inventory for a stated year, with a written boundary.
Goes wrong: A boundary that later moves drags every target with it.
Net zero consultancy · pathway
A net zero pathway is a sequence of actions
The chart below is an illustrative planning tool. Its linear reference line is not a universal SBTi pathway or a prediction of your organisation’s emissions.
Explore the pathway guidance and tools
A pathway is the actions that close the gap, sequenced and sized.
A list of ideas with no estimate of what each saves is not one.
Your pathway vs 4.2% a year
Below 4.2%
24%
Cut by 2030
After 2050
90% cut reached
Each lever · % of baseline it removes
Example values.
Replace them with your own estimates.
65%
Removed by these levers
25%
Gap to a 90% cut
These levers leave 25% to find before a 90% cut.
For a building portfolio or an industrial site, the levers are engineering decisions.
Brief a firm that sizes them, not one that lists them.
The reference line is the SBTi’s near-term minimum for Scope 1 and 2, drawn here as a visual benchmark.
Delivery work is covered on decarbonisation consultancy and carbon reduction consultancy.
- 1
Inventory
A controlled baseline and current position.
- 2
Actions
Sized reductions, dependencies and feasibility.
- 3
Investment
Owners, timing, costs and approvals.
- 4
Review
Actual results against the planned pathway.
Net zero consultancy · targets
What net zero consultants prepare for independent validation
A consultant supports preparation; SBTi Services validates targets. The publication of V2.0 does not make it the submission version for companies applying in 2026.
Explore the targets guidance and tools
A consultant prepares.
SBTi Services validates, for a fee.
SBTi Services says it does not offer consultation services.
You
Data, boundary and the baseline year.
A consultant prepares
The inventory and the targets for submission.
SBTi Services validates
For a fee. It does not consult.
When will you submit?
Either version
Under V2.0, market instruments such as credits are accounted for and reported separately from the physical inventory.
Ask any provider which version your targets will be prepared under.
The transition is on the V2.0 guide.
Preparation and validation differ
Inventory
Preparation and validation differ
Criteria
Preparation and validation differ
Submission date
Preparation and validation differ
Validation
Net zero consultancy · credits
Keep the inventory and the claim separate
UK SRS S2 asks for absolute gross emissions. Credits and a neutrality claim are separate disclosures and decisions; they do not erase the reported inventory.
Explore the credits guidance and tools
Reported emissions stay gross.
UK SRS S2 ¶29(a) asks for absolute gross emissions.
SECR has no netting-off provision.
A net target discloses its planned use of credits separately, under ¶36(e).
A neutrality claim is a separate thing: ISO 14068-1:2023 was withdrawn; its successor ISO 14068:2026 was still under publication when checked on 10 October 2026.
Buying credits well is its own discipline: carbon offset consultants.
Neutrality claim standards
- PAS 2060Withdrawn
- ISO 14068-1:2023Withdrawn 11 Sept 2026
- ISO 14068:2026Current
Three records, separate boundaries
Net target
Three records, separate boundaries
Target criteria
Three records, separate boundaries
Neutrality claim
Net zero consultancy · ppn
A procurement condition with a defined scope
PPN 006 concerns specified central government procurements above £5 million a year, including VAT and averaged over the contract. It is a distinct brief from a corporate transition plan.
Explore the ppn guidance and tools
Bidders for in-scope central government contracts above £5m a year provide a Carbon Reduction Plan under PPN 006.
It is a condition of participation for that procurement.
Not a legal duty on the company.
The plan confirms a commitment to net zero by 2050 in the UK.
The baseline usually starts from your SECR figures.
Template on carbon reduction plans.
Yes
CRP
A Carbon Reduction Plan is asked for
- Scope 11
- Scope 21
- Scope 3: five named categories5
The Carbon Reduction Plan brief
Procurement
The Carbon Reduction Plan brief
Emissions
The Carbon Reduction Plan brief
Commitment
Free · 15 minutes · video or phone
Fifteen minutes, free.
Bring the proposal and we will test it against the questions below.
Net zero consultancy · ask
Choosing net zero consultants: the questions to ask
Choose net zero consultants on their proposal: ask for the boundary, target criteria, scoped outputs, action owners, handovers and exclusions.
Separate baseline work from strategy and any independent verification.
Explore the ask guidance and tools
Six questions.
Tick each one the proposal in front of you answers.
For financial institutions, financed emissions are usually measured under the PCAF standard.
If the driver is ESOS, the work is an energy assessment with a registered lead assessor: ESOS consultants.
For specialist target-setting support, the SBTi consultancy guide helps you define the work and compare proposals.
The full buying process is in how to choose a sustainability consultant.
0
of 6
Too many gaps to compare this proposal yet.
Make the proposal reviewable
Scope
Make the proposal reviewable
Criteria
Make the proposal reviewable
Delivery
Make the proposal reviewable
Price
Net zero consultancy · firms
Net zero consultancy firms: an unranked directory
These are dated descriptions from firms’ own websites, not independent assessments. UK SRS recommends none and takes no fee for listing.
Explore the firms guidance and tools
Each described only from its own site, read on 1 October 2026.
This site has assessed none, recommends none, and takes no fee for listing.
12
firms
- Big Four4
- Specialist5
- Engineering2
- Energy services1
The same label covers audit firms, engineers, specialists and an energy services group.
Grouping is ours, not a ranking.
12 of 12 firms
Verdantix’s Green Quadrant ranks consultancies on its own criteria; not reproduced here.
Need a person rather than a programme?
See head of sustainability and chief sustainability officer.
To talk it through, you can book a free 15-minute call.
Compare the work, not a badge
Relevant scope
Compare the work, not a badge
Methods
Compare the work, not a badge
Responsibilities
Compare the work, not a badge
Evidence
Net zero consultancy · quiz
Test the claim against its provision
National targets, reporting duties and voluntary target criteria are different things. The short test gives the provision behind each answer.
Explore the quiz guidance and tools
The false ones read a national target or a disclosure as a company duty.
Each answer names its provision.
0
of 5
0 of 5 answered
01The Climate Change Act requires every large company to reach net zero by 2050.
02Under the FCA’s final rules, a commercial company must publish a transition plan.
03A consultant can validate a science-based target.
04SBTi Corporate Net-Zero Standard V2.0 is already the operative standard.
05A Carbon Reduction Plan under PPN 006 must commit to net zero by 2050 in the UK.
Check the claim before repeating it
Who
Check the claim before repeating it
What
Check the claim before repeating it
When
Check the claim before repeating it
Source
16 / Frequently asked
Net zero consultants, answered
What does a net zero consultant do?
A net zero consultant helps an organisation measure its baseline emissions, set reduction targets, design a pathway of actions, write a transition plan with owners, dates and costs, and support delivery.
The measurement step is the same as a carbon footprint; what is added is the forward-looking plan.
Is net zero a legal requirement for UK companies?
No. The Climate Change Act 2008 puts the 2050 net zero target on the Secretary of State, not on companies.
The national target does not itself impose a company transition-plan duty.
Listed companies in scope of the FCA’s rules must say whether they have published one, and government contracts above £5 million a year ask bidders to commit to net zero by 2050.
Is net zero being scrapped in the UK?
No. Section 1 of the Climate Change Act 2008 still requires the Secretary of State to ensure the net UK carbon account for 2050 is at least 100% lower than the 1990 baseline, and the seventh carbon budget was set in 2026.
Do listed companies need a transition plan under the FCA’s rules?
They need to say whether they have one.
Under PS26/19, companies in UKLR 6, 16 and 22 state in the annual financial report whether they have published a climate-related transition plan and where, or why not.
There is no duty to have one, and UKLR 14 and 15 companies do not make the statement.
Can a consultant validate our science-based targets?
No. Targets are validated by SBTi Services, which says it does not offer consultation services.
A consultant can help prepare the inventory and the targets for submission.
Which SBTi standard applies now?
Version 1.3.1 of the Corporate Net-Zero Standard governs today.
V2.0 was published on 11 June 2026 and opens for general corporate validation on 1 February 2027.
General corporate submissions may use V1.3.1 or V2.0 from that date through 31 January 2028; new submissions use V2.0 from 1 February 2028.
Check sector and SME routes separately.
Can carbon credits count towards net zero?
Not towards reported emissions, which stay gross under UK SRS S2 and SECR.
Under UK SRS S2 a company with a net target discloses its planned use of credits.
Under SBTi V2.0, market instruments are accounted for separately from the inventory.
What is the difference between net zero and carbon neutral?
Net zero is a long-term target to reduce emissions deeply and address the residual.
Carbon neutrality is a claim assessed under the applicable standard, with emissions reductions ahead of offsetting.
ISO 14068-1:2023 was withdrawn on 11 September 2026; the successor ISO 14068:2026 catalogue record was still under publication when checked on 10 October 2026.
PAS 2060 is withdrawn.
How much does a net zero consultancy cost?
This site does not estimate consultancy fees.
Confirm current pricing directly and ask each shortlisted firm for a written scope by stage, with days by grade, and price the baseline separately from the strategy work.
Which consultancies are recommended for net zero transition advice?
This site recommends none and has assessed none.
The directory lists firms alphabetically from their own descriptions; use the questions on this page to compare their proposals.
What do net zero strategy consultants in the UK deliver?
The strategy stages of the work: targets against a stated baseline, a pathway of sized actions and a transition plan with owners, dates and costs.
Ask for the baseline to be scoped and priced separately, because it has an objective standard behind it and the strategy does not.
Is a decarbonisation consultant different from a net zero consultant?
The phrases describe the same market.
Decarbonisation consultancy usually puts more weight on delivery: energy efficiency, heat, electrification, fleet and renewable power.
Do we need an ESOS consultant or a net zero consultant?
If the driver is ESOS, the work is an energy assessment reviewed by a lead assessor on an approved register.
ESOS opportunities often feed the pathway stage of a net zero plan, but the assessment itself is a separate, regulated piece of work.
How do we get an independent review of our net zero roadmap?
Commission it from an adviser who did not prepare the plan, and give them the baseline, targets and costed actions.
If the review covers the emissions figures themselves, verification to ISO 14064-3 by a body accredited under ISO 14065 is the recognised route.
What services does a net zero consultancy provide?
Six pieces of work: a carbon footprint on the GHG Protocol covering Scope 1, 2 and 3; science-based targets prepared for SBTi validation; a decarbonisation roadmap of sized actions; a transition plan with owners, dates and costs; the disclosures UK rules ask for, such as UK SRS S2, an SECR report or a PPN 006 Carbon Reduction Plan; and, if wanted, verification to ISO 14064-3.
Does a small business need a net zero consultant?
Usually not for a legal duty.
SECR reaches quoted companies and large unquoted companies, and ESOS reaches undertakings with at least 250 employees or above both its turnover and balance sheet limits.
A small business more often needs a first carbon footprint because a customer or a public buyer asked for one; a bid for a central government contract above £5 million a year needs a Carbon Reduction Plan under PPN 006.
The SBTi runs a separate SME route for companies that meet its tests.
Net zero software or a net zero consultant?
Software produces and tracks the numbers.
Choosing the boundary, the targets and the actions is judgement.
Many organisations use a consultant to set up the baseline and plan, then software to run the annual tracking.
Free · video or phone
A short call on your net zero plan.
Fifteen minutes, video or phone.
Which stage you are at, and what to ask a net zero consultant before you sign.
- 0115 minutes, video or phone
- 02Which stage you are at
- 03What the rules ask of you
- 04A plain next step
Pick a time on the calendar
Book a free 15-minute call →Opens the booking calendar to choose a live slot.
Continue reading
Read next
UK SRS transition plans
What S2 and the FCA ask a listed company to say.
SBTi Corporate Net-Zero Standard V2.0
What changes and when.
Decarbonisation consultancy
Energy efficiency, heat, electrification, fleet and renewable power.
Carbon offset strategy consultancy
Whether, when and how much to offset.
Carbon reduction consultancy
From PPN 006 plans to SBTi targets.
Sustainability consulting firms
Selection criteria tied to the law, and an unranked A to Z.
Sources
Primary sources
Every figure traces to the instrument’s owner.
Last verified 11 October 2026.
- SBTi ServicesGuide to the transition to Corporate Net-Zero Standard V2.0
General corporate validation opens 1 February 2027; V1.3.1 submissions close 31 January 2028; V2.0 for new corporate submissions from 1 February 2028.
- ISOISO 14068:2026 successor catalogue record
Under publication when checked on 10 October 2026; do not describe it as a completed publication.
- legislation.gov.ukClimate Change Act 2008, section 1
The 2050 net zero target, a duty on the Secretary of State.
- Financial Conduct AuthorityPS26/19
Comply or explain across UK SRS from 2027; the transition plan statement.
- Financial Conduct AuthorityPS26/19 (PDF), ¶2.37
Whether a climate transition plan exists and where it can be found.
- Financial Conduct AuthorityCP26/5, the consultation PS26/19 finalised
The proposals the final rules replaced.
- Department for Business and TradeUK SRS S1 and UK SRS S2
Published 25 February 2026.
- Department for Business and TradeUK SRS S2 (PDF), ¶¶14, 29, 36
Transition plan information, gross emissions and planned use of carbon credits.
- Department for Energy Security and Net ZeroClimate-related transition plan requirements, consultation
Ran 25 June to 17 September 2025; Consultation proposals are separate from the applicable reporting rules.
- IFRS FoundationTransition Plan Taskforce resources
The TPT materials, now held by the IFRS Foundation.
- Science Based Targets initiativeScience Based Targets initiative
Target criteria; validation by SBTi Services.
- Science Based Targets initiativeCorporate Net-Zero Standard V1.3.1 (PDF)
Near-term minimum of a linear 4.2% a year for Scope 1 and 2; long-term targets of at least a 90% absolute cut for many companies.
- Science Based Targets initiativeHow to set science-based targets
SBTi Services validates targets and does not offer consultation services.
- Science Based Targets initiativeCorporate Net-Zero Standard V2.0 release
Published 11 June 2026; general corporate validation opens 1 February 2027.
- Greenhouse Gas ProtocolCorporate Value Chain (Scope 3) Standard
The baseline’s value chain categories.
- Cabinet OfficePPN 006, Carbon Reduction Plans
Above £5m a year including VAT; Scope 1, 2 and five Scope 3 categories; net zero by 2050 in the UK.
- GOV.UKStreamlined energy and carbon reporting
The annual emissions disclosure a baseline often starts from.
- legislation.gov.ukSI 2008/410 Schedule 7 (SECR)
The directors’ report energy and carbon disclosure; it has no netting-off provision.
- ISOISO 14068-1:2023 catalogue record
Withdrawn 11 September 2026; successor ISO 14068:2026 still under publication when checked on 10 October 2026.
- ISOISO 14064-3:2019 catalogue record
Verification and validation of greenhouse gas statements.
- ISOISO 14065:2020 catalogue record
Requirements for bodies that validate and verify environmental information.
- PCAFPartnership for Carbon Accounting Financials
Financed emissions for financial institutions.
- Greenhouse Gas ProtocolCorporate Accounting and Reporting Standard
Scope 1 and Scope 2 are the minimum a corporate inventory reports.
- legislation.gov.ukESOS Regulations 2014, Schedule 1
A large undertaking: at least 250 employees, or turnover above £44m and a balance sheet above £38m.
- legislation.gov.ukESOS Regulations 2014, regulation 4
Phase 4: qualification date 31 December 2026, compliance date 5 December 2027.
- legislation.gov.ukESOS Regulations 2014, Part 6A
The action plan, due 5 December 2028, and the progress updates after it.
- legislation.gov.ukSI 2026/335, the Building Regulations amendments
The Future Homes and Buildings Standard for England, in force 24 March 2027.
- SBTi ServicesFAQs for SMEs (PDF)
The SME route’s eligibility tests, including under 10,000 tCO2e across Scope 1 and location-based Scope 2.
Related questions
Follow the question to its dedicated guide
For a hiring brief, read about net zero consultant recruitment and distinguish the role from a consultancy contract.