Carbon consultancy · the compliance map
Carbon consultancy: the duties mapped
Carbon consultancy is help with the UK rules that put a carbon or energy duty on a business, and there are more of them than most proposals mention.
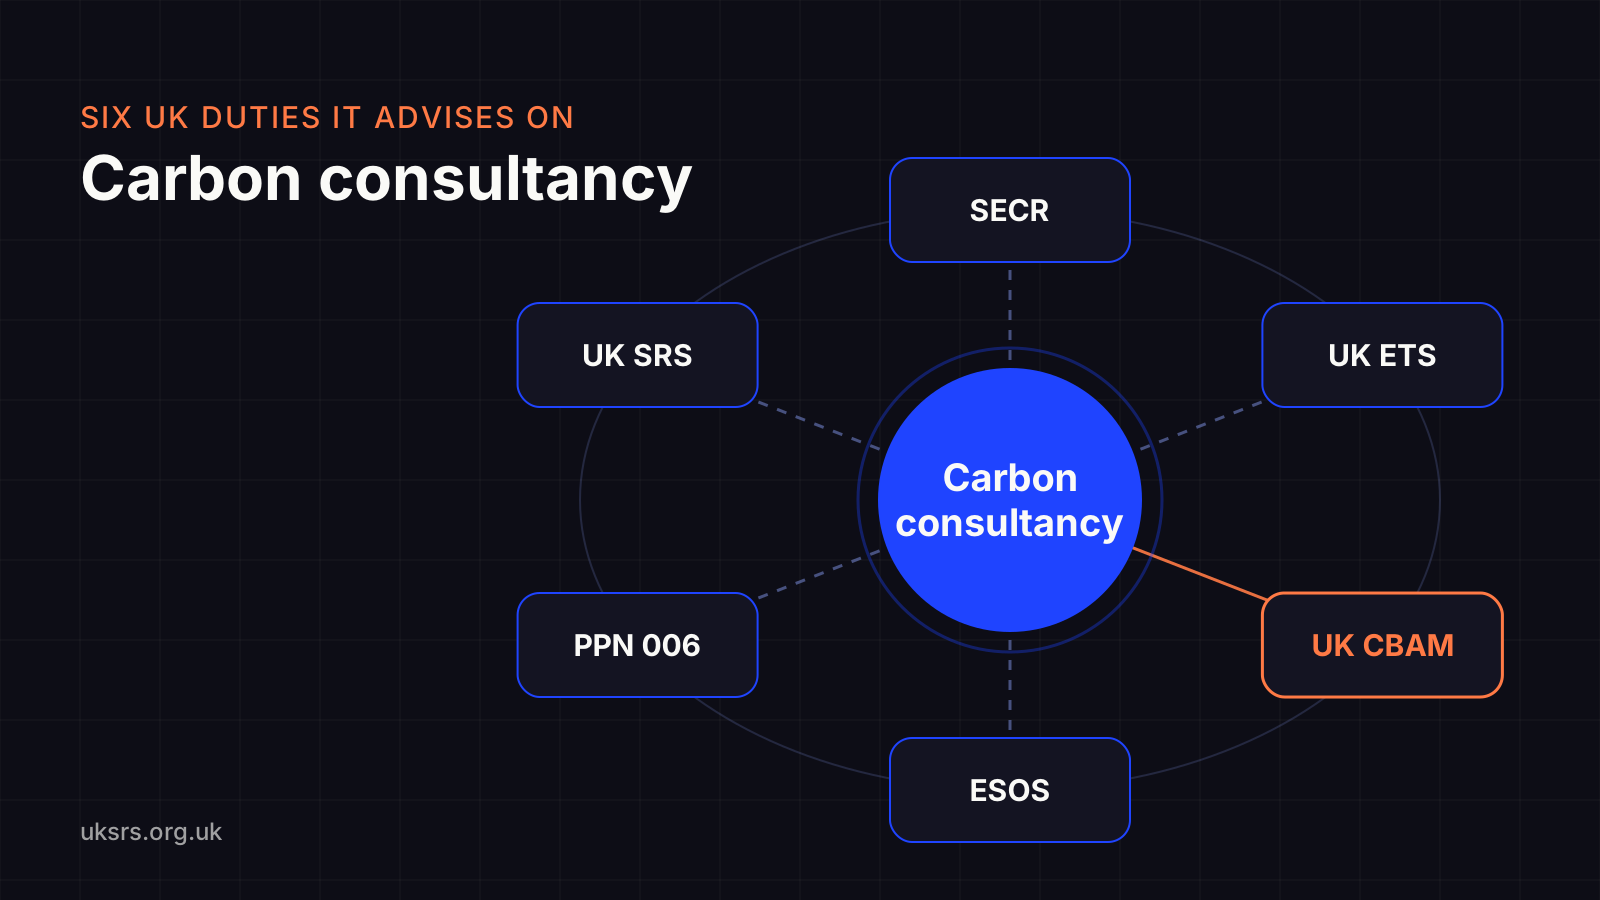
SECR, the UK ETS, UK CBAM from 1 January 2027, ESOS and, for listed companies, UK SRS each ask for something different, and only one requires an accredited verifier.
This guide maps those duties, explains what a carbon consultant does with each, and lists firms alphabetically from their own descriptions — it ranks none.
What the work is
What carbon consultancy covers
Carbon consultancy works on a business’s greenhouse gas emissions: measuring them, meeting the rules that apply to them, and reducing them.
“Carbon consultant”, “carbon consulting” and “carbon consultancy” describe the same market; what varies is which of those three jobs a firm leads with.
The compliance job is the one this page is about, because it is the one with legal edges: deadlines, prescribed content, and in one regime a verifier who must be accredited.
The regimes are taken one by one, with the questions to ask, on the page about carbon compliance consultancy.
The measurement underneath it follows the GHG Protocol; the GHG Protocol guide covers the standards, and carbon accounting the method.
Many companies measure in-house on a platform; the carbon reporting software guide compares the tools.
Measure: build the inventory.
See carbon footprint consultants.
Comply: meet the specific regimes that apply.
Reduce: targets, plans and delivery.
See net zero consultants.
The duties
The UK duties, side by side
Each row is a different rule with a different trigger.
Most businesses are under one or two of them; very few are under all.
| Duty | Who it reaches | What it asks for | Verifier? |
|---|---|---|---|
| SECR | Quoted companies; large unquoted companies and LLPs | Energy use, Scope 1 and 2 (and transport fuel Scope 3 for unquoted), an intensity ratio and an efficiency narrative, in the annual report | No |
| UK ETS | Regulated installations, aircraft operators and, from 1 July 2026, ships of 5,000 GT and above | A monitoring plan, an annual emissions report and allowances surrendered | Yes — UKAS-accredited |
| UK CBAM | Importers of specified aluminium, cement, fertiliser, hydrogen, iron and steel goods | A charge on embedded emissions from 1 January 2027, using verified actual data or default values | Where actual data is used |
| ESOS Phase 4 | Large undertakings on 31 December 2026 | An energy assessment covering at least 95% of total energy consumption; notification by 5 December 2027 | Lead assessor review |
| PPN 006 | Bidders for in-scope government contracts above £5m a year | A Carbon Reduction Plan: Scope 1, 2 and five Scope 3 categories | No |
| UK SRS (FCA rules) | Listed companies in UKLR 6, 14, 15, 16 and 22 | UK SRS S2 climate disclosures, Scope 1–3 included, or an explanation, from periods beginning 1 January 2027 | No; name the provider if obtained |
Climate Change Agreements are not on the list because they are not a duty: they are a voluntary scheme giving eligible sites a Climate Change Levy discount in return for targets.
The Companies Act climate disclosure duty in sections 414CA and 414CB sits alongside these for larger companies, and is covered on climate-related financial disclosures.
SECR
SECR is the duty most companies meet first
Streamlined Energy and Carbon Reporting puts energy and emissions figures in the annual report every year.
A quoted company reports at any size; an unquoted company or LLP is exempt if it meets two or more of turnover not more than £36 million, balance sheet not more than £18 million and not more than 250 employees (paragraph 20B).
That table is SECR’s own and did not move when the Companies Act size limits rose in April 2025.
No credential is required to prepare a SECR disclosure, and the government’s guidelines say the figures need not be assured, though they recommend it.
The government’s SECR guidance is the entry point, and the SECR reporting guide covers the disclosure in detail.
Offsets play no part in a SECR figure: there is no netting-off provision, so reported emissions stay gross.
Traded and border carbon
UK ETS and UK CBAM: emissions with a price attached
The UK ETS is the one carbon regime where verification is a legal requirement: the compliance guidance says the verifier must be accredited by UKAS to ISO 14065 and the Verification Regulation, with a scope covering the activity reported.
From 1 July 2026 the scheme reaches ships of 5,000 gross tonnage and above, whatever their flag, under SI 2026/392, and the maritime monitoring covers carbon dioxide, methane and nitrous oxide.
UK CBAM is newer: Part 5 of the Finance Act 2026 charges specified imported goods in five sectors from 1 January 2027.
The charge rests on the goods’ embedded emissions, either verified actual data or a government default, according to HMRC’s policy summary.
For an importer, the consultancy question is whether to obtain supplier emissions data good enough to use instead of the defaults.
These are specialist regimes, and a firm that is strong on corporate reporting is not automatically equipped for monitoring plans or customs data.
Energy, procurement and listing
ESOS, PPN 006 and UK SRS, briefly
ESOS is about energy, but it runs on the same meter data as a carbon inventory; a large undertaking on 31 December 2026 notifies compliance by 5 December 2027, with a lead assessor’s review, according to the Phase 4 guidance.
PPN 006 asks bidders for in-scope government contracts above £5 million a year for a Carbon Reduction Plan; it is a condition of participation, not a law about companies.
For listed companies, the FCA’s final rules require reporting against UK SRS on a comply-or-explain basis from periods beginning on or after 1 January 2027.
The consultation behind them, CP26/5, proposed mandatory S2; the final rules did not adopt that.
For any other company, UK SRS is available for voluntary use; the standards are explained on UK SRS S1 and S2, and plans on UK SRS transition plans.
Map it
Which inventory do your duties need?
Tick the duties and requests that apply to you, and the panel lists what each asks the inventory to cover and whether anyone must verify it.
Most companies need one inventory with several cuts, not several inventories.
Write the boundary for the widest duty and record how the others are cut from it.
For financial institutions, financed emissions are a separate exercise, usually under the PCAF standard.
Which footprint do you need?
UK energy use and the related Scope 1 and 2 emissions, plus the transport-fuel element of Scope 3, an intensity ratio and an efficiency narrative.
The 40,000 kWh-or-less relief applies to UK energy and only if the report states it.
Verification: No legal assurance requirement.
SI 2008/410 Sch 7 Part 7A, ¶20D(7)(a)
A map of what the rules ask, not legal advice.
Nothing you tick is stored or sent.
Scope 3
Scope 3 is where carbon consultancy earns its fee
The Scope 3 Standard defines fifteen categories, and a good consultant identifies which are material, builds a credible estimate and designs how supplier data will replace estimates over time.
For a listed company in scope of the FCA’s rules, UK SRS S2 asks for Scope 3 too, on a comply-or-explain basis, with a one-year relief that must be stated if used.
PPN 006 asks for only five Scope 3 categories, and SECR for none beyond transport fuel for unquoted companies.
The full category list, with notes, is on carbon footprint consultants.
Targets and offsets
Targets, credits and the claims you can make
Target setting usually follows the criteria of the Science Based Targets initiative, whose subsidiary SBTi Services validates targets and does not offer consultancy.
Its Corporate Net-Zero Standard V2.0 was published on 11 June 2026 and takes effect on 1 February 2027.
Carbon credits are a separate purchase with their own diligence and claim rules, covered on carbon offset consultants.
Credits never reduce reported emissions under SECR or UK SRS, which ask for gross figures.
Who offers the work
Carbon consultancy firms, listed A to Z
The panel lists carbon consultancy firms alphabetically, each described only from its own site as read on 1 October 2026.
This site has assessed none of them and takes no fee for listing.
Read each description against the duties above: a firm that describes engineering or project delivery may suit a UK ETS or CBAM question better than a reporting question, and the reverse.
Commercial rankings such as Verdantix’s Green Quadrant assess firms on their own criteria and are not reproduced here.
The wider market is in the sustainability consultancy guide, and governance and social work with an ESG consultant.
To talk through which duty applies, you can book a free 15-minute call.
Firms, in alphabetical order
11 of 11 firms shown.
Alphabetical; the order means nothing.
- Anthesis Group
In its own words, summarised: A sustainability consulting group that describes guiding clients through an end-to-end sustainability journey.
- Carbon Trust
In its own words, summarised: Climate transition work with businesses, governments, financial institutions and philanthropies, across and within sectors.
- Deloitte UK
In its own words, summarised: ESG advisory services: working with businesses on innovation, emissions reduction, resilience and trust.
- EcoAct (now SE Advisory Services)
In its own words, summarised: EcoAct’s site says it is now SE Advisory Services, Schneider Electric’s global consulting practice, covering climate strategy and decarbonisation.
- ERM
In its own words, summarised: Sustainability consulting and advisory: corporate sustainability, net zero and climate change, and renewable energy.
- EY UK
In its own words, summarised: EY-Parthenon sustainability and ESG strategy consulting: strategy, M&A, capital allocation and portfolio work.
- Inspired
In its own words, summarised: Energy buying and management alongside sustainability reporting and compliance support.
- PwC UK
In its own words, summarised: A sustainability services page within its UK advisory offer.
- Ramboll UK
In its own words, summarised: An engineering, architecture and consultancy company working on sustainable solutions for governments and companies.
- Ricardo
In its own words, summarised: Engineering consultancy in propulsion, driveline and energy systems.
- South Pole
In its own words, summarised: Climate consulting, carbon credits and project development: reporting, net zero planning, renewable procurement and Scope 3 work.
Each description was read on the firm’s own site on 1 October 2026.
This site has assessed none of these firms, has no commercial relationship with any of them, and lists them in no order of merit.
Test yourself
Six compliance claims, true or false
Each statement is one a buyer is likely to hear, and each answer names its provision.
The false ones overstate a duty — verification for SECR, a legal Carbon Reduction Plan, mandatory UK SRS — or understate what a credit is.
The true ones are the two newest regimes: maritime in the UK ETS and UK CBAM.
Carbon compliance: true or false?
SECR requires a company’s emissions figures to be independently verified.
A carbon offset purchase can be deducted from the emissions reported under SECR.
UK CBAM applies from 1 January 2027.
From 1 July 2026 the UK ETS covers large ships.
A Carbon Reduction Plan is a legal duty for every large company.
Listed companies must report against UK SRS S2 in full from 2027, with no option to explain.
0 of 6 answered.
Nothing you choose is stored or sent.
Frequently asked
Carbon consultants, answered
What does carbon compliance mean?
Meeting the UK rules that put a carbon or energy duty on a business: SECR reporting in the annual report, UK ETS monitoring and verification for regulated installations, ships and flights, UK CBAM on certain imports from 1 January 2027, ESOS energy assessments, and, for listed companies, UK SRS reporting on a comply-or-explain basis from 2027.
A Carbon Reduction Plan under PPN 006 is a procurement condition rather than a legal duty.
What does a carbon consultant do?
A carbon consultant measures emissions, works out which carbon rules apply and what they ask for, prepares the disclosures or returns, and plans reductions.
The work ranges from a single-entity SECR inventory to UK ETS monitoring plans, CBAM embedded-emissions data and target setting.
Is a carbon consultant the same as a carbon footprint consultant?
Overlapping, not the same.
A footprint consultant measures; a carbon consultant also covers compliance with specific regimes and reduction programmes.
Many firms do both, but the footprint is worth scoping and pricing separately because it has an objective standard behind it.
Do I need a carbon consultant for SECR?
No credential is required to prepare a SECR disclosure, and the law does not require the figures to be assured.
Many companies prepare SECR in-house or with software; outside help is most useful in the first year, for groups, or where the methodology will be scrutinised.
Which UK carbon rules need an accredited verifier?
The UK ETS: the verifier must be accredited by UKAS to ISO 14065 and the Verification Regulation, for the activity reported.
SECR, UK SRS and PPN 006 do not require verification.
What is UK CBAM and when does it start?
The UK carbon border adjustment mechanism, legislated in Part 5 of the Finance Act 2026, applies from 1 January 2027 to specified goods imported into the UK in five sectors: aluminium, cement, fertiliser, hydrogen, and iron and steel.
How much does carbon consultancy cost?
No firm listed here publishes a price, and this site does not estimate one.
Ask for a written scope with days by grade.
The government’s SECR review found a mean ongoing compliance cost of £7,100 a year, internal and external together.
Are Climate Change Agreements a compliance duty?
No. Climate Change Agreements are a voluntary scheme that gives eligible energy-intensive sites a discount on the Climate Change Levy in return for meeting targets.
They are not a disclosure or audit duty and are not a substitute for SECR or ESOS.
What is the difference between a carbon consultant and a net zero consultant?
A carbon consultant tends to work on measurement and compliance, often in an annual cycle; a net zero consultant works on targets, transition plans and the multi-year programme that follows.
Most firms offer both under different engagements.
Sources
Primary sources
Every figure, date and status on this page traces to the instrument’s owner.
Secondary commentary is never the source for a number.
- legislation.gov.ukSI 2008/410 Schedule 7 (SECR)
What quoted and large unquoted companies report.
- legislation.gov.ukSI 2008/410 Schedule 7 paragraph 20B
The unquoted-company exemption test.
- GOV.UKStreamlined energy and carbon reporting
The government’s guidance entry point for SECR.
- Defra / BEISEnvironmental Reporting Guidelines including SECR guidance
No legislative requirement to assure SECR figures.
- GOV.UKUK ETS for installations: how to comply
Verified annual emissions; UKAS-accredited verifier.
- legislation.gov.ukSI 2026/392 — UK ETS extension to maritime activities
Ships of 5,000 gross tonnage and above from 1 July 2026.
- legislation.gov.ukFinance Act 2026, Part 5 (CBAM)
UK CBAM from 1 January 2027 on goods in five sectors.
- HM Revenue & CustomsCarbon border adjustment mechanism: policy summary
How the charge works.
- Environment AgencyHow to comply with ESOS Phase 4
Dates, the lead assessor and the routes.
- Cabinet OfficePPN 006 — Carbon Reduction Plans
A condition of participation above £5 million a year.
- Financial Conduct AuthorityPS26/19
Comply or explain across UK SRS from 2027.
- Financial Conduct AuthorityCP26/5 — the consultation PS26/19 finalised
Proposed mandatory S2; not adopted.
- Department for Business and TradeUK SRS S1 and UK SRS S2
Published 25 February 2026.
- Greenhouse Gas ProtocolCorporate Value Chain (Scope 3) Standard
The fifteen Scope 3 categories.
- Science Based Targets initiativeScience Based Targets initiative
Target criteria and validation.
- PCAFPartnership for Carbon Accounting Financials
The financed emissions standard-setter.
Continue reading
Read next
Carbon footprint consultants
The inventory, the scopes and the claims to check.
Net zero consultants
Targets, transition plans and delivery.
The SECR reporting guide
The disclosure, line by line.
Carbon compliance consultancy
Which carbon duties apply, and who may do each piece of work.
Carbon management consultancy
Carbon run as a yearly cycle, with an in-house handover.
Sustainability consulting firms
Selection criteria tied to the law, and an unranked A–Z directory.