ESG consultancy UK · choosing the right support
ESG consultancy UK
Start with the reporting duty or business decision. Match the consultant to the work, check the credentials that matter and retain evidence your team can use next year.
UK SRS is an independent reference site. We have assessed no consultancy and publish no consultancy prices or rankings.
ESG consultancy · label
ESG consultancy is four purchases wearing one job title
Reporting: Prepare the applicable disclosures. Strategy: Choose priorities and delivery actions.
Explore the detailed guidance and tools
Different buyers.
Different deliverables.
A credential in only one.
A ranking of “the best ESG consultancies” is built from the seller’s size, not your position.
ESG
consultancy
Carbon accounting and statutory reporting
- For
- SECR; the metrics half of UK SRS S2
- Deliverable
- An inventory and the figures in the annual report
- Credential
- None required by law
- Buyer
- Usually finance
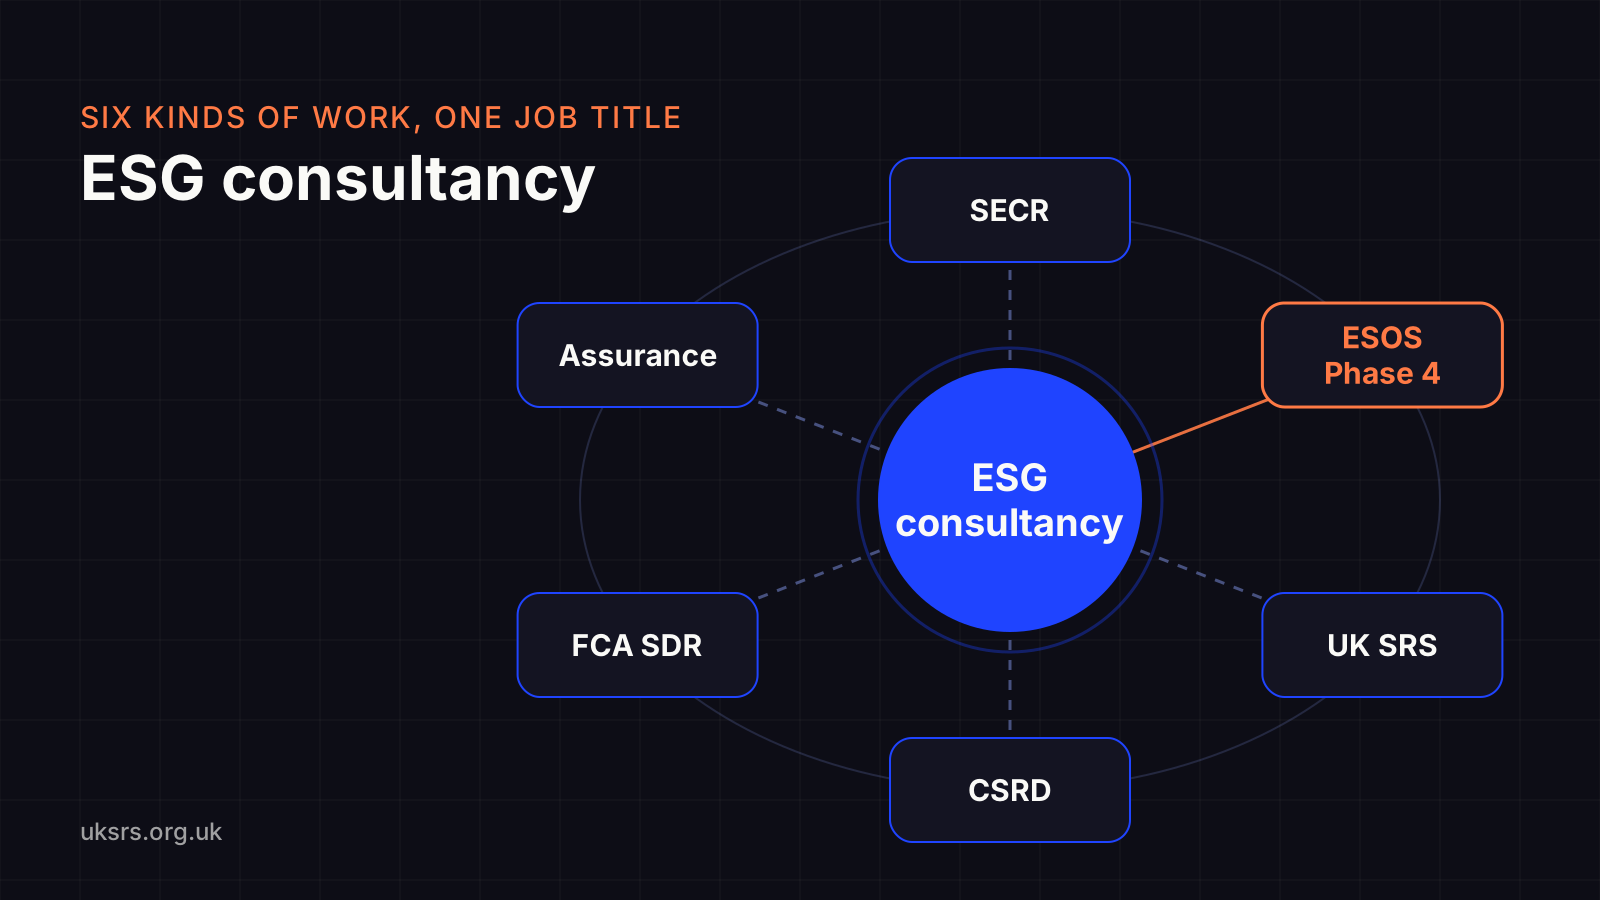
The thing that describes you is the obligation, which is where ESG consultancy should start.
The wider market is mapped in the sustainability consultancy guide, and the selection process in how to choose a sustainability consultant.
Module 01 / 04
Reporting
Module 02 / 04
Strategy
Module 03 / 04
Measurement
Module 04 / 04
Assurance
ESG consultancy · intent
Who needs an ESG consultant, and for what
Duty: Which legal or reporting requirement applies? Decision: What does your board or customer need?
Explore the detailed guidance and tools
The person searching usually owns one obligation.
Pick the role closest to yours.
They are buying for
SECR
Carbon accounting attached to the directors’ report.
Searches like · SECR reporting consultants
Go to SECR →Module 01 / 04
Duty
Module 02 / 04
Decision
Module 03 / 04
Output
Module 04 / 04
Owner
ESG consultancy · obligation
Which obligation applies to you?
Entity: Company, group, operator or financial firm? Rule: Check the actual provision and threshold.
Explore the detailed guidance and tools
One year’s figures through eight UK duties at once.
Most organisations are caught by more than one, and the overlap shapes the brief.
Each test is read as its instrument writes it.
Thresholds to the provision are on UK SRS thresholds.
Your figures · one entity, one year
Literal readings.
No group aggregation, two-year rules or ESOS snapshot date.
Nothing leaves your browser.
4
of 8
duties apply on these figures
UK SRS
Not on these figuresFCA PS26/19
Voluntary for this category.
SECR
AppliesSI 2008/410 Sch 7 ¶20B
Meets fewer than two conditions.
Climate disclosure
Not on these figuresCA 2006 s.414CA
At or under the 500-employee floor, or not caught.
ESOS
AppliesSI 2014/1643 Sch 1
Large undertaking.
Snapshot 31 December 2026.
Modern slavery
AppliesMSA 2015 s.54
Turnover £36m or more: annual statement.
Gender pay gap
AppliesSI 2017/172
250 or more employees on 5 April.
Section 172 statement
Not on these figuresCA 2006 s.414CZA
Medium-sized or smaller.
Governance Code
Not on these figuresUK CGC 2024
Not in a Code category.
Module 01 / 04
Entity
Module 02 / 04
Rule
Module 03 / 04
Period
Module 04 / 04
Output
ESG consultancy · timeline
Publication and application differ
Standard: Publication does not create a duty for every company. Rule: Check the category and reporting-period start.
Explore the detailed guidance and tools
04 / The obligations timeline
Every date an ESG consultant will quote
25 Feb 2026 · passed
UK SRS
UK SRS S1 and S2 published
Available for voluntary use.
DBT.
18 Mar 2026 · passed
CSRD
Omnibus I in force
1,000 employees and €450m, cumulative.
3 Jul 2026 · passed
CSRD
Revised ESRS adopted
Over 60% fewer mandatory datapoints.
22 Jul 2026 · passed
ESOS
Phase 4 amendments in force
Lead assessor’s seven-day notice.
30 Jul 2026 · passed
ESOS
Phase 4 guidance published
Environment Agency.
30 Sept 2026 · passed
UK SRS
FCA final rules, PS26/19
Comply or explain across UK SRS.
28 Oct 2026 · in 18 days
UK SRS
Draft TN 803.1 comments close
Proposed guidance, not final.
15 Dec 2026 · in 66 days
Assurance
ISSA (UK) 5000 effective date
For periods beginning on or after it.
Voluntary use.
31 Dec 2026 · in 82 days
ESOS
Phase 4 qualification date
Size on that day governs.
1 Jan 2027 · in 83 days
UK SRS
Comply or explain periods begin
Listed companies in scope.
5 Dec 2027 · in 421 days
ESOS
Phase 4 compliance date
Notification due.
1 Jan 2028 · in 448 days
UK SRS
First UK SRS reports
For 2027 periods.
Module 01 / 04
Standard
Module 02 / 04
Rule
Module 03 / 04
Relief
Module 04 / 04
Deadline
Free · 15 minutes · video or phone
Fifteen minutes on which kind of ESG consultant fits, before you brief anyone.
ESG consultancy · secr
SECR is a reporting job, tested by exemption
Scope: Apply the company and group tests. Working: Calculate energy and required emissions.
Explore the detailed guidance and tools
An annual disclosure in the directors’ report.
Its deadline is your filing deadline.
A quoted company reports at any size.
An unquoted company is caught unless it meets two of the three paragraph 20B conditions.
Grid electricity → Scope 2 · live
32.7
tCO₂e · location
0.82
tCO₂e per £m turnover
White line: 40,000 kWh, at or below which (in total energy) the figures may be omitted.
Factor 0.13096 kgCO₂e/kWh: the DESNZ 2026 UK electricity generated factor, for location-based Scope 2 (transmission and distribution losses are Scope 3).
Turnover from 03.
Paragraph 20B(2) · your figures from 03
Turnover · not more than £36m
£40m · over
Balance sheet total · not more than £18m
£15m · condition met
Employees · not more than 250
300 · over
White line: the limit.
Bars scale to twice the limit.
Result
SECR applies
Meets 1 of 3 conditions.
Two or more is exempt.
Status changes only when it holds two years running.
The Companies Act size limits rose in April 2025.
SECR’s own table did not move.
The instrument is SI 2018/1155, which inserted Part 7A from 1 April 2019.
This is carbon accounting attached to statutory reporting.
See SECR requirements and the SECR reporting guide.
Module 01 / 04
Scope
Module 02 / 04
Working
Module 03 / 04
Narrative
Module 04 / 04
Approval
ESG consultancy · esos
ESOS is a credential question before it is an energy one
Scope: Apply the Phase 4 qualification test. Route: Select the permitted assessment approach.
Explore the detailed guidance and tools
The one obligation where the law names who must review the work.
That shortens any list of firms before you make a call.
Phase 4 · the dates
22 Jul 2026
Amendments in force
Seven-day notice to the approval body.
30 Jul 2026
Guidance published
Environment Agency.
31 Dec 2026
Qualification date
Size on that day governs Phase 4.
5 Dec 2027
Compliance date
Notification of compliance due.
95%
Audit coverage
Areas making up at least 95% of total energy.
The Environment Agency’s guidance, §7.2, says you must appoint a lead assessor from an approved register.
Checking it is your responsibility.
Since 22 July 2026 the 2026 amendment regulations make the lead assessor notify their approval body within seven days.
Two ways out: under 40,000 kWh, or ISO 50001 covering significant consumption.
The route is on the Phase 4 compliance guide.
The dates are on ESOS deadlines, and the audit on the ESOS energy audit.
Module 01 / 04
Scope
Module 02 / 04
Route
Module 03 / 04
Assessor
Module 04 / 04
Follow-up
ESG consultancy · uksrs
UK SRS is comply or explain, and the explanation is the work
Category: Check the applicable listing category. Standards: Address S1 and S2 with available reliefs.
Explore the detailed guidance and tools
An explanation must say why a disclosure is not made and what steps are planned.
So “explain” is itself a deliverable a consultant can help draft.
UK SRS S1
Comply or explainUK SRS S2
Comply or explainFinal rules, 30 September 2026.
All of UK SRS on comply or explain.
Your listing, from 03
Not in scope.
UK SRS is voluntary for you.
From PS26/19 to first reports
S1 and S2 published
FCA final rules
Comply or explain periods
First reports
Scope 3 relief
Non-climate S1 relief
Reliefs: one year of Scope 3, two years of non-climate S1 matters, each stated if used.
Source: FCA PS26/19.
For a listed company, the useful work now is a gap analysis against UK SRS S1 and S2.
Governance and materiality take longest.
The two standards together are on UK SRS S1 and S2, and value-chain emissions on UK SRS Scope 3 reporting.
The FCA listing rule does not create a general UK SRS duty for private companies.
Check any separate reporting rule, overseas requirement or contractual request before pricing compliance work.
The standards were published on 25 February 2026, and the FCA’s draft Technical Note 803.1 on explanations is open for comment until 28 October 2026.
The consultation, CP26/5, had proposed mandatory S2; PS26/19 did not adopt it.
Module 01 / 04
Category
Module 02 / 04
Standards
Module 03 / 04
Explanation
Module 04 / 04
Evidence
ESG consultancy · csrd
CSRD reaches UK groups from the side
Entity: Identify the undertaking or group. Thresholds: Apply the relevant cumulative conditions.
Explore the detailed guidance and tools
Most UK organisations meet CSRD as a subsidiary, a supplier or a third-country group with EU turnover.
Not as a parent reporting directly.
Article 40a · third-country groups
Not passed
EU turnover over €450m
Not passed
EU subsidiary or branch over €200m
Not caught under Article 40a
Directive (EU) 2026/470, in force 18 March 2026.
Undertakings of 1,000 employees or fewer may decline value-chain requests beyond the voluntary standards.
Useful when a customer questionnaire overreaches.
ESRS uses double materiality; UK SRS does not.
Brief a firm with European reporting experience.
See CSRD versus UK SRS.
The third-country test is on Article 40a, the standards on ESRS, the directive on its own reference page and the simplification on the CSRD Omnibus page.
Module 01 / 04
Entity
Module 02 / 04
Thresholds
Module 03 / 04
Implementation
Module 04 / 04
Supplier
ESG consultancy · sdr
SDR is a regulated-firm regime, not a corporate one
Firm: Check authorisation and the regulated activity. Product: Assess the applicable label and disclosure rules.
Explore the detailed guidance and tools
The FCA’s Sustainability Disclosure Requirements apply to authorised firms, chiefly asset managers.
Financed emissions are Scope 3 category 15, usually measured with the PCAF standard.
The regime is on FCA sustainability disclosure requirements.
Is your organisation FCA-authorised?
Outside SDR
A proposal that opens with SDR was written for someone else.
Module 01 / 04
Firm
Module 02 / 04
Product
Module 03 / 04
Claims
Module 04 / 04
Scope
ESG consultancy · credentials
What a credential on a proposal actually tells you
Membership: Check the current body and grade. Assessment: Use an approved register where required.
Explore the detailed guidance and tools
Most ESG work has no legal entry requirement.
That makes the two named credentials the most useful filter you have.
2
in law
- Named in law2
- Describe a person2
- Not a competence credential2
Named in law
ESOS lead assessor
On one of seven approved registers.
Since 22 July 2026, notifies their body within seven days.
Named in law
UK ETS verifier
Accredited by UKAS.
Describes a person
ISEP professional grades
AISEP, PISEP, MISEP, FISEP since 17 July 2025.
Assessed grades.
Formerly IEMA.
Not a competence credential
ISEP affiliate
An online sign-up, by ISEP’s own description.
Describes a person
Chartered Environmentalist
Awarded by the Society for the Environment.
No master’s degree required.
Not the consultant’s
ISO 14001 certified
Certifies the client’s management system.
A firm cannot hold it on your behalf.
The body once called IEMA became the Institute of Sustainability and Environmental Professionals.
ISEP’s own membership page describes affiliate membership as an online sign-up.
Chartered Environmentalist status is awarded by the Society for the Environment.
None of these makes a firm accredited.
A firm cannot be “ISO 14001 certified” on a client’s behalf; the ISO 14001 guide explains who certifies what.
Module 01 / 04
Membership
Module 02 / 04
Assessment
Module 03 / 04
Certification
Module 04 / 04
Accreditation
ESG consultancy · assurance
Your adviser is usually not your assurer
Management: Own information and decisions. Preparer: Support calculations and drafting.
Explore the detailed guidance and tools
The FCA’s rules do not require assurance.
If you obtain it, PS26/19 ¶2.45 asks you to name the provider.
Decide early, choose the provider, then brief the advisory work around it.
Which do you choose first?
Choose the assurer
Decide whether you will seek assurance, and who provides it.
Brief the adviser
Advisory work is scoped around the assurer’s independence.
Assurance proceeds
No self-review.
The assurer can act.
ISSA (UK) 5000
Periods from 15 Dec 2026
Issued by the FRC on 12 November 2025, for voluntary use.
Earlier application is permitted.
FRC interim register
Not yet announced open
A firm claiming to be on it is making a checkable claim.
IESBA
No self-review
For public interest entities, generally prohibited.
The FRC issued ISSA (UK) 5000 for voluntary use, and the government’s response on assurance oversight set out an interim register to be run by the FRC.
The IESBA standards bar an assurance practitioner from assuming management responsibility for a client.
The sustainability assurance guide covers the standards in full.
Module 01 / 04
Management
Module 02 / 04
Preparer
Module 03 / 04
Assurer
Module 04 / 04
Reader
ESG consultancy · deliver
What the work hands you
Calculation: Boundary, methods and source records. Report: Required disclosures or explanations.
Explore the detailed guidance and tools
Each obligation has its own deliverable.
Name it in the brief.
“A roadmap” is not one.
- 01UK energy use, in kWh
- 02Scope 1 and 2 emissions
- 03An intensity ratio
- 04The methodology
- 05Energy efficiency action
Signed by · The board, in the directors’ report
Module 01 / 04
Calculation
Module 02 / 04
Report
Module 03 / 04
Action plan
Module 04 / 04
Handover
ESG consultancy · cost
What ESG consultancy costs: the scope, not the day rate
Work: Name stages, outputs and exclusions. Effort: Days and grades for each stage.
Explore the detailed guidance and tools
No firm named here publishes a day rate. This site does not estimate one.
What decides the invoice is how many days the scope contains, and at which grades.
Stage 01
Scope
Cheap, and decides everything after it.
Ask for days by grade, in writing.
Module 01 / 04
Work
Module 02 / 04
Effort
Module 03 / 04
Inputs
Module 04 / 04
Year two
Free · 15 minutes · video or phone
Fifteen minutes, free.
Bring the obligation and the scope you have been sent.
ESG consultancy · sme
What an SME usually needs
Customer: Is a questionnaire or data request driving this? Procurement: Does a bid require a specified plan?
Explore the detailed guidance and tools
Most SMEs asking for an ESG consultant are outside all four obligations.
A customer is asking, not a regulator.
Answer the questionnaire, not the framework behind it.
01
A defensible carbon number
Enough to answer the customer who asked.
02
A short policy set
Not a programme.
03
The ability to answer a questionnaire
A customer asking for Scope 3 is exercising a contract, not a regulation.
Software is often enough.
See the carbon reporting software guide and the ESG software comparison.
A consultant can help prepare a science-based target.
Only the SBTi can validate it.
Module 01 / 04
Customer
Module 02 / 04
Procurement
Module 03 / 04
Reporting
Module 04 / 04
Proportion
ESG consultancy · reporting
Building the report, or fixing the machine that makes it
Record: Keep the source input. Calculate: Document method, factors and assumptions.
Explore the detailed guidance and tools
“ESG reporting consultancy” usually means one of two jobs.
Say which in the first line of the brief.
A proposal for the wrong one can still look competent.
Build this year’s report
Gathering data, calculating metrics and drafting disclosure against a named standard.
- Data gathering
- Metric calculation
- Draft disclosures
- A named standard
Ratings preparation is disclosure work too.
Most weak scores reflect what is not published, not what is not done.
There is more on building this year’s report in its own guide.
What UK ESG reporting requires is on ESG reporting, the frameworks on UK ESG frameworks, and a working structure on the ESG reporting template.
Module 01 / 04
Record
Module 02 / 04
Calculate
Module 03 / 04
Review
Module 04 / 04
Disclose
ESG consultancy · brief
Write the brief a capability deck cannot answer
Purpose: One clearly stated reporting or business need. Boundary: Entities, activities and the reporting period.
Explore the detailed guidance and tools
A vague brief gets a capability deck in return, and decks cannot be compared.
“We qualify for ESOS Phase 4 on headcount” is a brief.
“We need ESG support” is not.
A starting draft, not advice.
Names no provider.
Nothing is stored or sent.
Your draft, ready to copy
Brief
Why we are buying: SECR (directors’ report, every year).
Date the work must support: [add the date].
Deliverable: A gap analysis against the named standard, then drafting support for the disclosures we decide to make.
We will own every calculation file, methodology note and draft at the end.
Please price year two in the same proposal, and give the days by grade.
Questions · please answer in writing
1. Which of our obligations is in force, which is comply or explain, and which is voluntary?
Cite the provision for each.
2. Which parts will you draft, and which should we write because they describe our own governance?
3. Can you show a redacted example against the same standard, in our sector?
4. How many days, at which grades, does your proposal assume?
Module 01 / 04
Purpose
Module 02 / 04
Boundary
Module 03 / 04
Output
Module 04 / 04
Handover
ESG consultancy · firms
ESG consultancies in the UK, listed alphabetically
Experience: Ask for relevant, permitted examples. Method: Test the approach against your brief.
Explore the detailed guidance and tools
Each described only from its own site, read on 1 October 2026.
This site has assessed, vetted and endorsed none of them, and takes no fee for listing.
15
firms
- Big Four4
- Pure-play4
- Engineering6
- Assurance1
The same label covers audit firms, engineers and a testing group.
Grouping is ours, not a ranking.
15 of 15 firms
Alphabetical; the order means nothing.
Verdantix’s Green Quadrant and Environment Analyst rank firms on their own criteria; not reproduced here.
The carbon cut is on carbon footprint consultants.
Module 01 / 04
Experience
Module 02 / 04
Method
Module 03 / 04
People
Module 04 / 04
Terms
ESG consultancy · hire
Buy what ends, hire what repeats
Scope: Can your team establish applicability? Method: Can it calculate and document the working?
Explore the detailed guidance and tools
The test is whether the work ends.
For many first-time reporters the answer is both, in sequence.
Ends · buy consultancy
A consultant builds it
- A gap analysis
- A baseline
- An ESOS audit
- A first report
Recruiters are compared in the sustainability recruitment assessment.
The menu of work is on ESG consulting services, and you can book a free 15-minute call to talk through which kind of help fits.
Module 01 / 04
Scope
Module 02 / 04
Method
Module 03 / 04
Capacity
Module 04 / 04
Review
ESG consultancy · quiz
Six claims you will hear, true or false
Who: Which entity or regulated activity? What: Which output or claim?
Explore the detailed guidance and tools
The false ones borrow urgency from a rule that does not apply.
The ESOS register question is the one with a penalty attached.
0
of 6
0 of 6 answered
01Under the FCA’s final rules, UK SRS S2 is mandatory for listed companies from 2027.
02An unquoted company with £40m turnover, £15m balance sheet and 200 employees is exempt from SECR.
03Any member of a professional body can sign off an ESOS assessment.
04Assurance of UK SRS disclosures is required by the FCA’s rules.
05FCA SDR applies to every UK company that publishes an ESG report.
06CSRD now reaches EU undertakings with more than 1,000 employees and more than €450m turnover.
Module 01 / 04
Who
Module 02 / 04
What
Module 03 / 04
When
Module 04 / 04
Source
Illustrative brief · no consultancy assessed
A worked brief: a board asks for reporting support
Identify which reporting rule or voluntary framework the board means. Ask for a scope note and a source-to-disclosure demonstration before comparing proposals.
For the detailed requirements, see ESG consulting services.
- 1
Scope
Entity, reporting period and applicable provision.
- 2
Preparation
Named calculations, disclosures and explanations.
- 3
Review
Management approval and any separate assurance.
Each date has a different meaning
The relevant dates, in order
Check who the date applies to and whether it is publication, application, submission or a planned milestone.
- 25 February 202601
UK SRS published
Available for voluntary use; publication alone does not create a universal company duty. - 30 September 202602
- Periods from 1 January 202703
Listed-company application
UKLR 6, 14, 15, 16 and 22 report against the standards or explain. - 2028 / for calendar-year companies04
First reports under the new rule
Other year ends have their own annual-report timetable.
A suggested delivery sequence
From the brief to the handover
This is an editorial buying and preparation sequence, not a statutory timetable or a promise about how long the engagement takes.
- 01 / Brief01
Brief
Name the duty or decision and the required output. - 02 / Evidence02
Evidence
Collect records, methods and assumptions. - 03 / Preparation03
Preparation
Draft the calculations, disclosures or action plan. - 04 / Review04
Review
Resolve gaps and assign the relevant approvals. - 05 / Handover05
Handover
Keep editable working, ownership and update guidance.
20 / Frequently asked
ESG consultancy questions, answered
What does an ESG consultant do?
An ESG consultant helps an organisation measure, disclose and manage environmental, social and governance matters: carbon accounting, materiality, governance, disclosure against named standards, ratings questionnaires and readiness for assurance.
Under one job title the market sells four different purchases (statutory carbon reporting, registered energy assessment, disclosure readiness and assurance), and they rarely come from the same firm.
Which ESG consultant do I need?
Start with the obligation, not the firm.
SECR needs carbon accounting attached to the annual report; ESOS Phase 4 needs a lead assessor on an approved register; UK SRS under the FCA’s rules needs disclosure readiness for a listed company; CSRD needs a team that can report in the European standards’ shape; FCA SDR is for regulated asset managers only.
Is UK SRS mandatory now?
Not mandatory.
Since the FCA’s final rules of 30 September 2026, listed companies in UKLR 6, 14, 15, 16 and 22 must report against UK SRS on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027, with first reports in 2028.
For everyone else UK SRS remains voluntary.
Does an ESG consultant need to be accredited?
Usually not, because most ESG work has no legal credential.
The exceptions are ESOS, where the assessment must be reviewed by a lead assessor on one of the approved registers, and verification under the UK ETS, where the verifier must be accredited by UKAS.
Professional grades such as ISEP membership or Chartered Environmentalist status describe individuals, not firms.
Can the firm that writes our disclosure also assure it?
Assurance is not required by the FCA’s rules, but if you obtain it the report names the provider.
For sustainability assurance the IESBA standards bar a practitioner from assuming management responsibility for a client and generally prohibit self-review services for public interest entities.
Choose the assurance provider first, then brief the advisory work around it.
What does ESG consultancy cost in the UK?
No firm listed here publishes a price, and this site does not estimate one.
Ask each shortlisted firm for a written scope with the days by grade, and year two priced in the same proposal.
For SECR alone, the government measured a mean ongoing compliance cost of £7,100 a year, internal and external together.
What are the top ESG consulting firms in the UK?
This site does not rank firms and has assessed none.
Commercial studies rank consultancies against their own criteria, and those rankings measure breadth, size or reputation rather than fit for your obligation.
The firms in the directory here are listed alphabetically and described only from their own sites.
Does CSRD apply to UK companies?
Some.
Since Directive (EU) 2026/470 entered into force on 18 March 2026, CSRD scope requires more than 1,000 employees and more than €450 million turnover, cumulatively.
Third-country groups are caught through Article 40a, with a €450 million EU turnover test and a €200 million subsidiary or branch threshold.
Who needs an ESG consultant for FCA SDR?
Only FCA-regulated firms, chiefly asset managers.
The anti-greenwashing rule in ESG 4.3.1R applies to authorised firms’ communications about their products and services, and the entity-level SDR report applies to in-scope managers whether or not they use a label.
A company that is not FCA-regulated is outside SDR.
Is ESG still relevant in 2026?
The rules say so.
In 2026 the government published UK SRS, the FCA finalised comply-or-explain reporting for listed companies from 2027, ESOS Phase 4 guidance was published, and the EU revised ESRS.
What changed is the shape: fewer EU datapoints, and comply or explain rather than mandatory rules in the UK.
Should we hire an ESG manager instead of a consultant?
Buy consultancy for work that ends (a gap analysis, a baseline, a first report) and hire for work that repeats every year.
Many first-time reporters do both in sequence: a consultant to build the process, then an in-house lead to run it.
ESG software or ESG consultancy?
Software produces the numbers; a consultancy makes the choices behind them.
For an SME answering a customer questionnaire, software is often enough.
An ESOS assessment needs a lead assessor, and a first UK SRS gap analysis needs judgement, so those are consultancy purchases.
Do we need an ESG consultant in London?
No UK obligation turns on where a consultant is based.
The tests that matter are the obligation, the ESOS register for energy assessment and UKAS accreditation for UK ETS verification.
Who provides ESG assurance and audit services?
Audit firms and testing, inspection and certification groups both offer sustainability assurance.
Whoever you choose must be independent of whoever prepared the information, and the FCA asks a company that obtains assurance to name the provider.
Can an ESG consultant improve our ESG rating?
Ratings preparation is disclosure work.
Most weak scores reflect what is not published rather than what is not done, so ask which rating methodologies a firm has worked against.
Free · video or phone
A short call on your obligations.
Fifteen minutes, video or phone. Which kind of ESG help fits, before you brief anyone.
- 0115 minutes, video or phone
- 02Which obligations apply
- 03Which kind of help fits
- 04A plain next step
Pick a time on the calendar
Book a free 15-minute call →Opens the booking calendar to choose a live slot.
Continue reading
Read next
How to choose a sustainability consultant
The brief, the shortlist and the questions to send.
ESG reporting requirements in the UK
Every UK duty, with its test and provision.
Sustainability assurance
Standards, levels and independence.
ESG consulting services
Each service itemised, from materiality to assurance.
Sustainability reporting consultancy
Which framework applies, then data, drafting and assurance readiness.
Sustainability strategy consultancy
Materiality, targets, transition plans and governance, phase by phase.
Sustainability consulting firms
Selection criteria tied to the law, and an unranked A–Z directory.
Sources
Primary sources
Every figure traces to the instrument’s owner.
Last verified 10 October 2026.
- legislation.gov.ukSI 2008/410 Schedule 7 paragraph 20B
SECR’s exemption: two or more of turnover not more than £36m, balance sheet not more than £18m, not more than 250 employees.
- legislation.gov.ukThe Companies (Directors’ Report) and LLP (Energy and Carbon Report) Regulations 2018 (SI 2018/1155)
The instrument that inserted SECR, from 1 April 2019.
- Department for Energy Security and Net ZeroIndependent evaluation of SECR (2026)
19,900 organisations in scope; a mean ongoing cost of £7,100 a year.
- Department for Energy Security and Net Zero2026 greenhouse gas conversion factors: methodology paper, Table 9
UK electricity generated 0.13096 kgCO2e/kWh (Scope 2); transmission and distribution losses 0.01299 (Scope 3).
- Environment AgencyHow to comply with ESOS Phase 4, §7.2
The lead assessor duty, the dates and the routes.
- GOV.UK (Environment Agency)ESOS: approved lead assessor registers
The seven professional bodies that keep approved registers.
- legislation.gov.ukThe ESOS (Amendment) Regulations 2026 (SI 2026/701)
The lead assessor’s seven-day notice, from 22 July 2026.
- Financial Conduct AuthorityPS26/19: Aligning listed issuers’ sustainability disclosures with international standards
Comply or explain across UK SRS from 2027; reliefs; assurance transparency.
- Financial Conduct AuthorityPS26/19 (PDF), ¶¶1.2, 2.45, 3.6–3.7, 3.14
The categories, the reliefs and the assurance statement.
- Financial Conduct AuthorityCP26/5, the consultation PS26/19 finalised
Proposed mandatory S2; not adopted.
- Financial Conduct AuthorityDraft Technical Note 803.1 (September 2026)
Proposed comply-or-explain guidance; comments by 28 October 2026.
- Department for Business and TradeUK SRS S1 and UK SRS S2
Published 25 February 2026, available for voluntary use.
- EUR-LexDirective (EU) 2026/470 (Omnibus I)
In force 18 March 2026: 1,000 employees and €450 million, cumulative; Article 40a.
- European CommissionCommission adopts revised European Sustainability Reporting Standards
Adopted 3 July 2026; over 60% fewer mandatory datapoints.
- Financial Conduct AuthorityFCA Handbook, ESG 4.3: the anti-greenwashing rule
ESG 4.3.1R applies to authorised firms’ communications about products and services.
- FRCISSA (UK) 5000 (PDF)
For periods beginning on or after 15 December 2026, or as at that date; earlier application permitted; voluntary.
- FRCFRC takes steps to support quality in sustainability assurance (12 November 2025)
Issue of ISSA (UK) 5000.
- Department for Business and TradeDeveloping an oversight regime for assurance of sustainability-related financial disclosures
A voluntary oversight regime and an interim register to be run by the FRC.
- IESBAIESSA Technical Overview (January 2025)
Management responsibility and self-review.
- PCAFThe Global GHG Accounting and Reporting Standard for the Financial Industry
Financed emissions methodology.
- Greenhouse Gas ProtocolCorporate Value Chain (Scope 3) Standard
Category 15, investments.