UK SRSThe UK Sustainability Reporting Standards, ESOS, SECR and TCFD, read against the published text.HUBYOU ARE HEREUK SRS GuideAn independent reference guide to UK SRS, ESG, TCFD, SECR, ESOS and the global standards.Global Reporting StandardsSustainability reporting standards worldwide: ISSB, the EU CSRD after Omnibus I, California SB 253 and SB 261, and UK SRS.UK SRS StandardsUK SRS S1 and S2 at the provision: reliefs, comply or explain, and the FCA statements.ESOS QuestESOS Phase 4 in depth: qualification, the audit, sign-off, action plans and penalties, read against the Regulations.SRS EngineeringThe data build behind a UK SRS report: metrics, owners, controls and timing.SRS ReportWhat a UK SRS report contains, how it is assembled, and how to read one.UK SRS ReportAnalysis and commentary: CDP, the DESNZ emission factors, SECR and ESOS, with every figure cited.UK SRS NewsThe cluster's news publication, and what a UK SRS report contains.UK SRS DeliveryTemplates, costs, ESOS delivery guides and readiness assessment.UK SRS FinanceFinanced emissions, PCAF and IFRS S1/S2 for banks, insurers and asset managers.SECRStreamlined Energy and Carbon Reporting: deadlines, thresholds, eligibility and guidance.Carbon CreditsCarbon credit ratings, risk analysis, valuation and market structure.Environmental RegimesThe eight UK environmental reporting regimes, their thresholds, deadlines and regulators.UK SRS ServicesThe services arm: ESOS, SECR, net zero and sustainability consultancy.

ESG software · match the outputs you need

ESG software comparison

Compare the outputs your organisation needs, then ask each vendor to demonstrate the workflow. A long framework list does not establish that a product fits your duties.

This guide links the requirements to their primary sources. The vendor register records dated, published claims; UK SRS has assessed no product.

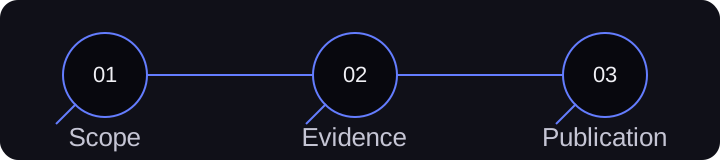
ESG software comparison diagram: scope, records and publication
A workflow overview; products have not been assessed by UK SRS

Compare ESG software against the duties you carry, not the frameworks the tables score.

  • SECRin the directors’ reportevery year
  • CA 2006climate disclosures, s.414CB, strategic reportevery year
  • FCAPS26/19 final rules30 Sep 2026
  • FCATN 803.1 draft: comments close28 Oct 2026
  • FRCISSA (UK) 5000 effective for periods from15 Dec 2026
  • ESOSPhase 4 qualification date31 Dec 2026
  • UK SRSlisted-company periods begin1 Jan 2027
  • EUrevised ESRS apply to financial years beginning from1 Jan 2027
  • ESOSPhase 4 notification due5 Dec 2027
  • FCAESG ratings regulation commences29 Jun 2028

The misregistration

The comparison tables score the wrong regulations

This is not a complaint about quality.

The published comparisons are often careful documents: Pulsora’s table of twenty-four platforms carries primary focus, Scope 3 support and framework coverage as real columns, and Plan A’s list breaks out a UK region.

Read the detailed requirements and references
What the comparisons score
Most published tables score CSRD and ESRS, GRI, SASB and CDP.
What a UK company files
A UK company files SECR, ESOS, UK SRS if listed and a Carbon Reduction Plan if bidding for central government work; CDP, where a customer asks, is the one overlap.

ESRS: EFRAG; UK duties: Sch 7 · ESOS · PS26/19 · PPN 006.

What they share is the scorecard: framework coverage means ESRS, GRI, SASB and CDP, because those are the frameworks on which the largest platforms look most complete.

Slide that scorecard over what a UK company is obliged to produce, and the two shapes do not line up.

ESRS binds a UK group only through an EU entity or EU listing in scope of CSRD as narrowed in 2026; GRI and SASB bind nobody by law; CDP is a voluntary questionnaire, answered because a customer or investor asks.

Who pays CDP’s fee and which questionnaire applies are on CDP reporting.

If you do have an EU footprint, which of the two regimes reaches you is a real question with its own page — CSRD compared with UK SRS — and the UK ESG reporting requirements hub sets out the whole obligation stack.

The guide below maps the comparison to UK outputs and explains what to ask vendors to demonstrate.

Two scorecards, one overlap

  • ESRS and CSRDscored by comparisons

    Reaches a UK group only through an EU entity or listing in scope of CSRD as narrowed in 2026: above €450 million turnover and 1,000 employees, for financial years from 1 January 2027. Directive (EU) 2026/470

  • GRIscored by comparisons

    A voluntary standard-setter’s framework; no UK law requires it. GRI Standards

  • SASBscored by comparisons

    A voluntary set of industry standards, now held by the IFRS Foundation; no UK law requires it. SASB Standards

  • CDPscored by comparisonsa UK company files it

    Voluntary, answered when a customer or investor asks. The one framework that is both scored and filed. CDP, how to disclose

  • SECRa UK company files it

    In force every year: the directors’ report of a quoted company, or a large unquoted company or LLP. SI 2008/410 Sch 7

  • ESOS Phase 4a UK company files it

    In force, four-yearly: qualification on 31 December 2026, notification by 5 December 2027. Environment Agency ESOS

  • UK SRS, listed companya UK company files it

    Comply or explain for periods from 1 January 2027 under the FCA’s final rules. FCA PS26/19

  • UK SRS, voluntarya UK company files it

    Voluntary for any entity that chooses it; published by DBT on 25 February 2026. DBT guidance

  • PPN 006 plana UK company files it

    A condition of bidding for in-scope central government contracts above £5 million a year. PPN 006 Technical Standard

“Scored by comparisons” is our reading of the columns in published vendor and directory tables; “a UK company files it” is the status of the instrument cited.

Nothing is stored or sent.

ESRS: EFRAG; UK duties: Sch 7 · ESOS · PS26/19 · PPN 006
What the comparisons scoreWhat a UK company files
CSRD and ESRSSECR, every year, in the directors’ report
GRIESOS Phase 4, an energy audit every four years
SASBUK SRS, comply or explain, if listed in UKLR 6, 14, 15, 16 or 22
CDPA PPN 006 Carbon Reduction Plan, if bidding for in-scope contracts
“Framework coverage”CDP too, where a customer asks — the one overlap
Compare the right outputsExplore

Compare the right outputs

UK duties

Start with the regimes that apply to the entity.

Definitions

What ESG software is, and what it is not

ESG software is the category name for systems that collect environmental, social and governance data, turn it into the figures a framework asks for, and produce a report with an evidence trail behind each number.

In practice the category is dominated by the environmental pillar: most products sold as ESG reporting software began as carbon accounting tools and grew outwards into social and governance indicators.

ESG compliance software usually means the same products pointed at a legal duty — a directors’-report section, a listing-rule statement, a CSRD sustainability statement — rather than at a voluntary report.

ESG disclosure software and ESG disclosure management software stress the last mile: drafting, tagging, review and sign-off of the disclosure, often inside the same system as the annual report.

ESG data management software stresses the first mile: collection, validation and ownership of the data before anyone calculates with it, and ESG data management covers that layer.

Three neighbouring products are often caught by the same search and are not reporting software at all.

ESG screening software is an investor tool for filtering portfolios against ESG criteria; ESG ratings platforms form an opinion about you for investors; and supplier-assessment platforms score a company’s suppliers for procurement.

None of those produces your SECR section or your UK SRS disclosures, and buying one for that purpose is a category error.

The rest of this page treats ESG software as reporting software, and measures it against what a UK company has to file.

The obligation set

What a UK company may have to produce, and on what clock

Software is bought to produce an output, so the first question is which outputs you are on the hook for; they are not the same document and they are not on the same clock.

Four are in force as law or listing rules, one is procurement policy, and two are voluntary.

That distinction matters when a salesperson says a platform is “UK SRS ready”: for a listed company it is a claim about a comply-or-explain duty from 2027, and for everyone else it is a claim about a standard nobody requires them to use.

Read the detailed requirements and references
Your companywhich duties apply?
Select a node
Tap or focus any regime to stop the orbit and read what it asks of the company at the centre.
Sources: Sch 7 · Environment Agency · FCA PS26/19 · DBT · PPN 006 · CDP
ObligationStatusWhoThe output
SECRIn force, annualQuoted companies of any size; unquoted companies and LLPs exceeding two of £36m turnover, £18m balance sheet, 250 employeesEnergy and carbon lines in the directors’ report (LLPs: an energy and carbon report)
Companies Act climate dutyIn force, annualTraded companies, banks, insurers, AIM companies and companies with turnover over £500m, above a 500-employee floorEight climate-related disclosures in the strategic report; UK SRS S2 is a national reporting framework for s.414CB(6)
ESOS Phase 4In force, four-yearlyUK undertakings with 250+ employees, or turnover over £44m and balance sheet over £38m, on 31 December 2026, and their groupsAn energy audit and a notification by 5 December 2027, then an action plan
UK SRS via the listing rulesFinal rules, comply or explainListed companies in UKLR 6, 14, 15, 16 and 22UK SRS disclosures or an explanation, for periods from 1 January 2027
UK SRS, voluntaryVoluntaryAny entity that chooses to apply itUK SRS S1 and S2 disclosures
PPN 006Procurement policyBidders for in-scope central government contracts above £5m a yearA Carbon Reduction Plan: Scope 1, 2 and five Scope 3 categories
CDPVoluntaryOrganisations asked by customers or investorsA scored questionnaire response

The listing rule replaced the TCFD-aligned climate statement listed companies used to make, and the FCA’s PS26/19 says so; the obligations reaching a listed company are on UK SRS thresholds.

Which of these reach your company, and how the size tests interact, is the UK ESG reporting requirements guide’s subject.

Different outputsExplore

Different outputs

Annual disclosure

SECR and relevant climate or sustainability disclosures have annual reporting routes.

The S and the G

Social and governance reporting in UK law

UK law asks for social and governance information in narrow, separate duties, and none of them is an ESG framework.

1 / 5

Each of these is a separate document, on a separate clock, owned by a different part of the business.

So ESG software with a long list of social and governance indicators is answering to customers, investors and voluntary frameworks, not to one UK statute.

The ESG criteria page sets out what each pillar is measured on.

Climate disclosure

The Companies Act climate duty software tends to forget

Most comparison tables list SECR and UK SRS and omit the duty that already applies to the largest companies, in the strategic report.

500
employees: the floor most companies in scope sit above
£500m
turnover that makes a company a high turnover company
8
climate-related disclosures in the strategic report

Sections 414CA and 414CB of the Companies Act 2006 reach traded companies, banks, insurers, AIM companies and companies with turnover over £500 million, in each case above a 500-employee floor and outside the small and medium-sized regimes.

The eight disclosures sit at section 414CB(2A)(a) to (h), starting with governance arrangements for climate-related risks and opportunities.

The Department for Business and Trade’s UK SRS material and its February 2026 consultation response confirm that UK SRS S2 is a national reporting framework for section 414CB(6), so a company reporting under S2 does not need to duplicate its disclosures.

The Government said it will consider the future of the section 414CB(2A) obligations when it considers the merits of reporting requirements against UK SRS.

For software, the test is whether the climate metrics are held once and mapped to whichever of the two the company reports under.

The TCFD guide covers the recommendations, and UK SRS S2 the standard.

Your own obligations

Answer six questions, read off the capabilities you need

The planner beside this does not rank platforms and never names one.

It takes your SECR position, your ESOS position, your listing, whether you apply UK SRS voluntarily, whether you bid for central government work and whether an EU entity is in scope of CSRD.

It returns the capabilities your obligations require, each tied to the provision that creates the need.

That output cannot be wrong about a vendor, because it says nothing about one.

It is the document to walk into a demo holding, instead of a shortlist somebody else wrote.

If you are unsure of an answer, the planner lists it at the end, because each unsettled obligation adds or removes a capability.

Obligations in, capabilities out

Are you a quoted company, or a large unquoted company or LLP within SECR?

A requirements list, not a recommendation: it names no product. Each line is tied to the provision that creates it.

Nothing is stored or sent.

The scorecard, rebuilt

Five capabilities a UK obligation demands

These are not features in a vendor’s sense; each is the thing that has to be true for a specific UK filing to come out of the software rather than out of a consultant.

SECR needs 01 and 02; ESOS needs 03; UK SRS needs 04 and 05 and leans on 01.

Read the detailed requirements and references
  1. Capability 01

    Conversion-factor currency

    Needed by SECR, PPN 006 and UK SRS where UK factors are used.

    The factor set and year sit on every figure, and the year matches the activity-data year.

    Ask Which year’s DESNZ set is loaded today, and where is the year stored? DESNZ conversion factors

  2. Capability 02

    SECR-format output

    Needed by SECR.

    kWh, emissions, an intensity ratio, the methodology, the efficiency narrative and comparatives come out as a directors’-report section.

    Ask Show a finished SECR section your platform produced for a company like ours. SI 2008/410 Sch 7

  3. Capability 03

    An ESOS evidence pack

    Needed by ESOS.

    Total energy in kWh by organisational purpose, the 95% coverage, audits and sign-off, exportable for a lead assessor.

    Ask Export twelve months of total energy for an assessor. Environment Agency Phase 4 guidance

  4. Capability 04

    Financial-statement alignment

    Needed by UK SRS, listed or voluntary.

    The same reporting entity, the same period and the same timetable as the accounts.

    Ask How do you handle a mid-year acquisition and a changed year end? UK SRS S1 ¶20

  5. Capability 05

    An assurance-ready trail

    Needed by all of them, if a figure has to survive a question.

    Source document, method, factor version, change log and sign-off per figure.

    Ask Show the audit trail behind one number. ISSA (UK) 5000, voluntary

Sources: DESNZ factors · Sch 7 · EA Phase 4 guidance · UK SRS S1 ¶20 · ISSA (UK) 5000
CapabilityWhat has to be trueWhich obligation needs it
01 · Conversion-factor currencyThe factor set and year on every figure, updated when DESNZ publishesSECR, PPN 006; UK SRS where UK factors are used
02 · SECR-format outputkWh, emissions, a ratio, the methodology, the efficiency narrative and comparatives, as a directors’-report sectionSECR
03 · An ESOS evidence packTotal energy in kWh by organisational purpose, the 95% coverage, audits and sign-off, exportableESOS
04 · Financial-statement alignmentSame reporting entity, same period, same timetable as the accountsUK SRS, listed or voluntary
05 · An assurance-ready trailSource, method, change log and sign-off per figureAll, if you want a figure to survive a question

A platform can be excellent on all five and still be wrong for you, because you may carry only two of them — which is why the planner returns a requirement set rather than a recommendation.

The per-regime register, output by output with each provision, is on carbon reporting software.

The reporting systemExplore

The reporting system

Evidence

Connect the output to records, methods and approvals.

Capability 01

Conversion-factor currency is a date, not a feature

The government publishes UK greenhouse gas conversion factors every year, and the set changes.

Grid electricity moves most, because the generation mix moves: the 2026 factor fell 26% from the 2025 set, and DESNZ attributes 6 to 7 percentage points of that to methodology changes.

Read the detailed requirements and references

A platform that calculated your electricity emissions on a set two years old produces a number that is wrong by whatever the grid and the method did in between, and produces it with complete confidence.

Every vendor will say it uses DESNZ factors, which is not the question.

Ask which year’s set is loaded today: the answer should be a year.

Ask how long an update takes, because the factors are usually published in the first half of June and a platform that ships them a quarter later has a season where the two disagree.

Ask what happens to last year’s figures, because restating a prior year on a new set changes your comparatives, and a good platform keeps the year and the factor set together on each figure.

Ask about Scope 2 methods: UK SRS S2 requires location-based Scope 2 and permits market-based information, and the GHG Protocol asks for both where contractual instruments exist.

The factor year matches the activity-data year: the 2026 set is for activity falling mostly within 2026, whenever the report is filed.

What the factors are and which applies to which activity is the GHG Protocol guide’s subject, and the calculation conventions sit on carbon accounting.

Data enters onceExplore

Data enters once

Sources

Import the source record and preserve its origin.

Capability 02

SECR output is a section of the directors’ report, not an emissions number

This is the capability most often assumed and least often demonstrated.

A compliant SECR disclosure is a piece of the annual report with named parts, set out in Schedule 7 of the accounts regulations as inserted by SI 2018/1155: UK energy use in kWh, the associated emissions, at least one intensity ratio, the methodology, a description of the principal energy-efficiency measures where any were taken, and last year’s figures.

Read the detailed requirements and references

Producing a tonnage figure is the easy part of that.

Energy in kWh is a different unit from the emissions figure, and many carbon tools discard it after converting.

The intensity ratio is your choice of denominator — turnover and full-time equivalents are common — and holding it steady year to year is what makes it comparable.

The methodology statement names the standard, the factor set and the boundary, and a platform that cannot export it in prose leaves it to whoever drafts the annual report.

No software writes the efficiency narrative for you, but a tool that tracks measures against savings makes it far cheaper to write.

A company using 40,000 kWh or less still owes a statement that the figures are not disclosed for that reason.

The government’s SECR guidance is the Environmental Reporting Guidelines, last updated on 29 March 2019, so anything a platform calls SECR best practice since then is the vendor’s view.

The practical test is simple: ask to see a finished SECR section produced by the platform for a company like yours, redacted if necessary; a dashboard screenshot is not that.

The full requirement, including the quoted-versus-unquoted split, is on SECR requirements, and the drafting on the SECR reporting guide.

A reproducible calculationExplore

A reproducible calculation

Method

Show which accounting approach was used.

Capability 03

ESOS is an audit, not a disclosure — and no global comparison mentions it

ESOS is the UK obligation the international software market has barely encountered.

It is not a report to investors; it is a mandatory assessment of total energy consumption, reviewed by a lead assessor, on a four-year cycle, run by the Environment Agency.

Read the detailed requirements and references

Phase 4 qualification is tested on 31 December 2026 and notification is due by 5 December 2027.

The Phase 4 guidance asks for total energy across buildings, transport, industrial processes and any other purpose, in energy units, so a tool that keeps only converted emissions has thrown away the input.

The reference period is twelve consecutive months including the qualification date, reconcilable to invoices and meter reads, with estimates labelled and their basis kept.

A lead assessor has to be able to follow the numbers back to source, so exportability matters more than presentation.

The same meter data serves SECR every year, and a platform that models the two obligations against one dataset is doing real work.

The scheme itself is on the ESOS Phase 4 compliance guide, and the post-assessment duty on the ESOS action plan.

Control the changesExplore

Control the changes

Review

Assign responsibility for checking and approving data.

Capability 04

Financial-statement alignment breaks standalone tools

UK SRS S1 and S2 follow the architecture of the ISSB’s standards, and that architecture asks for something most sustainability tools were not built to give.

UK SRS S1 paragraph 20 requires the sustainability disclosures to cover the same reporting entity as the financial statements, and the standard ties them to the same period and publication.

Read as a systems requirement, that becomes concrete.

The consolidation boundary has to match the accounts: which subsidiaries, which joint ventures, which mid-year acquisitions; if the carbon boundary and the group boundary differ, somebody reconciles them by hand every year.

The period has to match, including a short one: change the year end and the sustainability data must follow, which calendar-year tools find hard.

The report has to be ready when the accounts are, which is a close-process question and the one a finance director will care about.

This is where enterprise reporting suites earn their price, because they already live inside the financial close, and where a very good carbon tool can be exactly the wrong purchase.

For a listed company, PS26/19 adds a second record: where UK SRS S2 is not met in full, the statement says which requirements, why, and the steps planned, so the platform needs somewhere to hold that gap register.

What S1 and S2 require in full is on UK SRS S1 and UK SRS S2, and the comply-or-explain mechanics on UK SRS compliance.

Capability 05

The evidence trail is bought before you need it

Assurance over sustainability disclosures is not mandatory, under the FCA’s final rules or anywhere else in UK law.

What the final rules require of a listed company is a statement about assurance: whether it obtained any, from whom, over which disclosures and to which standards.

That kept the shape the CP26/5 proposal had, and commentary at the time, such as the Global Financial Regulatory Blog’s, read the proposal the same way.

ISSA (UK) 5000 is the FRC’s standard for the work, published for voluntary use and effective for engagements covering periods beginning on or after 15 December 2026.

The software question is narrower than the policy question: can somebody who was not in the room reconstruct how a figure was produced?

That needs a source document attached to each figure, the method and factor versioned so an old version still exists after a restatement, a change log with a name against each change, and a sign-off workflow with the approval kept.

The change log is the single most common gap when an assurance provider first walks a process, and it is cheap to configure early and expensive to reconstruct later.

The ICAEW’s sustainability hub and the FRC’s FAQs follow how assurance practice is developing, and UK sustainability assurance covers what a limited-assurance opinion covers.

Assurance, stated precisely

No UK regime requires sustainability assurance.

A listed company states whether it obtained assurance and, if so, the provider, the disclosures covered and the standards used (PS26/19).

ISSA (UK) 5000 was issued by the FRC on 12 November 2025 for voluntary use, effective for periods beginning on or after 15 December 2026.

The boundary

Measurement and disclosure are two purchases

Two jobs hide under the phrase ESG software.

The measurement layer turns activity data into an emissions number: meter reads, fuel, spend, supplier data, conversion factors and a calculation you can defend under the GHG Protocol.

Read the detailed requirements and references

The disclosure layer turns numbers into a filing: a framework-shaped report, tied to the entity and period of the accounts, with the evidence behind every figure.

Most of the market sells the first and calls it ESG software; the second is multi-framework mapping, alignment with the accounts, audit trail and sign-off.

Buying a disclosure platform when your problem is that nobody has the gas meter readings is an expensive way to discover you needed the other one.

Buying a measurement tool when your problem is that the auditor cannot trace a figure is the same mistake pointing the other way.

If your problem is the emissions number itself, go to carbon accounting software, which tests the measurement layer, and carbon reporting software, which carries the vendor-by-vendor profiles; if it is the data plumbing under both, ESG data management is the one you want.

Which layer is your problem?

Do you hold meter, fuel and travel data for every entity in your boundary, by site and month?

Three yes/no questions; the first “no” decides.

Nothing is stored or sent.

Inventory to disclosureExplore

Inventory to disclosure

Common data

Maintain the activity records and calculations once.

Where the cost sits

Scope 3 is why the price goes up, and fifteen is the wrong target

Scope 3 is where a reporting programme stops being an internal data exercise and becomes a supplier-engagement programme.

The GHG Protocol defines fifteen categories, set out in its Scope 3 calculation guidance, and vendors quote coverage of all fifteen as a headline.

What the UK regimes ask is narrower and more varied: SECR asks for almost no Scope 3, a PPN 006 plan asks for five named categories, and UK SRS S2 requires all fifteen to be considered and the included ones named.

For most companies a handful of categories carry most of the footprint, and the rest are small by comparison.

So the capability that matters is not fifteen-category coverage; it is whether the platform lets you move a material category from a spend-based estimate to supplier-specific data without rebuilding the model.

Everyone starts spend-based, and the test is whether purchased goods and services can be upgraded supplier by supplier while the rest stays as it was.

The workflow question is whether it can chase your suppliers: request templates, reminders, a portal, and somewhere to put an answer that is not an inbox.

The disclosure question is whether it can say what it did not measure: exclusions, estimation methods and their basis.

A listed company has one year’s Scope 3 relief under PS26/19, during which it states that it is using it.

Which categories apply and how to scope them is the Scope 3 emissions guide’s subject; what UK SRS asks for, including the relief, is on UK SRS Scope 3 reporting.

The framework modifiers

GRI software, ISSB software, net-zero software — same platforms, different question

A large share of software searches put a framework in front of the word, and they are not different product categories.

GRI reporting software is about breadth of social and governance indicators, not carbon depth.

What a GRI-capable tool must hold, and which vendors say they support GRI, is on GRI reporting software.

ISSB reporting software is about IFRS S1 and S2, which UK SRS is built from, so the differentiator is alignment with the financial statements.

What it must produce, requirement by requirement, is on IFRS sustainability reporting software.

Net-zero reporting software is target-setting, trajectory modelling and progress tracking against a baseline: adjacent to disclosure and often sold with it, but a separate job.

CDP reporting software is about populating a scored questionnaire from data you already hold, and CDP itself is voluntary, with its own scoring and no regulatory status.

Scenario analysis sits in the UK SRS S2 strategy disclosures, and platforms that offer it draw on physical-risk pathways from sources such as the IPCC Sixth Assessment Report.

If two frameworks are in play, the real question is whether one dataset serves both without being collected twice; that multi-framework mapping is the main reason a disclosure platform costs more than a carbon calculator.

“Sustainability reporting software” and “ESG reporting software” describe the same category from two angles: the first stresses structured disclosure against a named framework, the second breadth across environmental, social and governance topics.

Environmental reporting software usually means the environmental pillar only — energy, emissions, waste, water — which is the SECR and ESOS surface.

“Platform” tends to imply multi-entity consolidation and “tool” a single-purpose calculator, while ESG software is the least specific label of all, which is why it returns the least UK-relevant results.

Adding the country — ESG software UK, ESG reporting software UK — asks a genuinely narrower question, because the UK obligations are the part the global comparisons do not score.

How the frameworks relate is on ESG frameworks in the UK, ESG standards and the overview of the standards, and the wider standards landscape on sustainability reporting standards at our sister publication.

UK headquarters, EU operations

Meeting UK and EU expectations from one dataset

A UK-headquartered group with EU subsidiaries asks a harder question than either market alone: which software meets UK and EU expectations without collecting everything twice.

Start with whether CSRD reaches the group at all, because it was narrowed sharply in 2026.

Directive (EU) 2026/470, in force on 18 March 2026, limits CSRD to undertakings that exceed both €450 million net turnover and an average of 1,000 employees, for financial years beginning on or after 1 January 2027, with a separate test for third-country parents.

On 3 July 2026 the European Commission adopted revised ESRS and a voluntary standard for undertakings below the cap, based on the VSME recommendation, as the ESRS framework moved on.

The value-chain cap in the Accounting Directive, Article 19a(3), stops a CSRD reporter from requiring a value-chain undertaking with 1,000 employees or fewer to provide more than that voluntary standard asks, for the purposes of CSRD reporting.

So a UK supplier to an EU reporter may receive narrower requests than before, and software that can answer within the voluntary standard’s fields is doing useful work.

Where the group is in scope of both, the overlap is real but partial: UK SRS S2 requires location-based Scope 2 and permits market-based information, while ESRS E1 asks for both figures; UK SRS uses financial materiality, while ESRS uses double materiality.

The software question is the mapping one: can one dataset produce the UK SRS disclosures and the ESRS datapoints, with the differences held as configuration rather than as a second collection?

Which regime reaches you, and how the two differ, is on CSRD compared with UK SRS.

CSRD · which route are you in?

Which describes your position?

Pick the position that fits.

A UK group can stand in more than one: test each EU subsidiary on its own figures and the whole group under Article 40a.

Rules: Directive 2013/34/EU Arts 19a, 29a and 40a and Directive (EU) 2022/2464 Art 5, as amended by Directive (EU) 2026/470.

“Exceed” is strict and both limbs are needed.

Nothing you enter leaves your browser.

A provisional reading, not advice on your group perimeter.

CSRD and ESRS software

CSRD reporting software after the 2026 cut

ESRS coverage only matters to a UK company if CSRD reaches it, and since March 2026 it reaches far fewer.

€450m
net turnover: CSRD reaches only undertakings exceeding this and the employee limb
1,000
average employees, the second limb of the same test
2,027
financial years beginning on or after 1 January 2027: the narrowed scope and the revised ESRS
  1. 18 Mar 2026
    CSRD narrowed
    Directive (EU) 2026/470 enters into force.
    Directive (EU) 2026/470
  2. 3 Jul 2026
    Revised ESRS adopted
    The Commission adopts the revised ESRS and a voluntary standard for undertakings protected by the value-chain cap.
    C(2026) 5010 and 5011
  3. Scrutiny
    Entry into force is separate from application
    Article 3 provides for entry into force four months and a week after adoption, and for application to financial years beginning on or after 1 January 2027.
    C(2026) 5010 Article 3
  4. 1 Jan 2027
    First financial years
    For financial years beginning in 2026 an undertaking may apply the 2023 ESRS, the revised standards, or the 2023 ESRS with eight named reliefs, and must say which it applied.
    C(2026) 5010 Article 2

The Commission’s own announcement says the revised standards cut mandatory datapoints by more than 60%, a figure it gives for the adoption event and not for when the standards apply (DG FISMA, 3 July 2026).

The second act, C(2026) 5011, is a voluntary standard based on Commission Recommendation (EU) 2025/1710, for undertakings protected by the value-chain cap.

For a UK group the software question is therefore two questions: whether an EU entity or listing still exceeds the test, and whether suppliers can answer the voluntary standard’s fields.

The CSRD compared with UK SRS page covers which regime reaches you.

The vendors, in their own words

What vendors say, regime by regime

Pick a regime to see what each vendor’s own site says about it. This is self-description, linked and dated, not a score.

What vendors say about one regime · read 11 October 2026 and 30 September–1 October 2026

VendorWhat its own site saysPublished price
AltruistiqGet compliant with CSRD, SRS, California Climate Disclosures and more.Enterprise level · TBD
ASUENENo claim found on the pages we readEnterprise level · TBD
Benchmark GensuiteNo claim found on the pages we readEnterprise level · TBD
BriinkNo claim found on the pages we readEnterprise level · TBD
CarbonChainNo claim found on the pages we readEnterprise level · TBD
Clarity AINo claim found on the pages we readEnterprise level · TBD
ClimatiqNo claim found on the pages we readStarter: Free; Data Pro €3,000 / year (single-user, scope 1, 2 and 3 emission factors; €5,000 / year for client consulting use); PCF Pro from €4,900 / year
Climatise“One spine: SECR · ESOS · UK SRS” — the same client data “also serves SECR and UK SRS”Enterprise level · TBD
Compare Your FootprintGenerate UK SRS, VSME, and international framework reportsMeasure from £769 per year, billed annually (from £76/mo if billed monthly); Execute from £1,569 per year (from £156/mo monthly); Coordinate from £3,069 per year; 'Exact price depends on organisation size.' 14-day free trial, no credit card.
CoolsetNo claim found on the pages we readEnterprise level · TBD
CorityNo claim found on the pages we readEnterprise level · TBD
CozeroNo claim found on the pages we readEnterprise level · TBD
DatamaranNo claim found on the pages we readEnterprise level · TBD
DcycleNo claim found on the pages we readEnterprise level · TBD
DeepkiNo claim found on the pages we readEnterprise level · TBD
DiginexNo claim found on the pages we readEnterprise level · TBD
DiligentNo claim found on the pages we readEnterprise level · TBD
EcochainNo claim found on the pages we readFrom €290 a month (Professional) and €640 (Business) on its German pricing page; the English page shows “Custom”
EcologiNo claim found on the pages we readPPN 006 Carbon Reduction Plan: 'Pricing starts at £3,499 + VAT'. Other plans not priced on the pages read; SME page offers 'a free account' (an Ecologi profile).
EcoOnlineNo claim found on the pages we readEnterprise level · TBD
EcoVadisNo claim found on the pages we readEnterprise level · TBD
EmitwiseNo claim found on the pages we readNot sold standalone
EnablonNo claim found on the pages we readEnterprise level · TBD
EnvoriaNo claim found on the pages we readEnterprise level · TBD
EvotixNo claim found on the pages we readEnterprise level · TBD
Green Project TechnologiesNo claim found on the pages we readEnterprise level · TBD
Greenly“Connect your GHG Protocol data to UK SRS reporting”Enterprise level · TBD
GreenomyNo claim found on the pages we readEnterprise level · TBD
IBM Envizi ESG SuiteNo claim found on the pages we readEnterprise level · TBD
IdeagenNo claim found on the pages we readEnterprise level · TBD
IntegrityNextNo claim found on the pages we readEnterprise level · TBD
IntelexNo claim found on the pages we readEnterprise level · TBD
IsoMetrixNo claim found on the pages we readEnterprise level · TBD
MakersiteNo claim found on the pages we readEnterprise level · TBD
ManglaiNo claim found on the pages we readEnterprise level · TBD
MeasurablNo claim found on the pages we readFree solution 'at no cost, in perpetuity' (tracking incl. Scopes 1–3, benchmarking, secure sharing); premium/paid upgrades (Navigate, Optimize, Comply) have no published price.
Microsoft Sustainability ManagerNo claim found on the pages we readUS$4,000 (Essentials) or US$12,000 (Premium) per tenant, per month
MinimumNo claim found on the pages we readEnterprise level · TBD
Net Zero NowNo claim found on the pages we readEnterprise level · TBD
NormativeNo claim found on the pages we readEnterprise level · TBD
Nossa DataISSB and UK SRS disclosure, done right.Enterprise level · TBD
NovataNo claim found on the pages we readNovata for Companies: Manage 20K, Grow 50K, Lead 100K a year (currency not stated)
NovistoNo claim found on the pages we readEnterprise level · TBD
One Click LCANo claim found on the pages we readEnterprise level · TBD
OpteraNo claim found on the pages we readEnterprise level · TBD
Oracle Fusion Cloud SustainabilityNo claim found on the pages we readEnterprise level · TBD
osapiensCover CSRD/ESRS, VSME, GRI, ISSB, HKFRS SDS, UK SRS and more from a single source of truth your teams can always rely on.Enterprise level · TBD
PersefoniNo claim found on the pages we readPersefoni Pro “completely free”, single user; Advanced by quote
Plan ANo claim found on the pages we readEnterprise level · TBD
Planet MarkNo claim found on the pages we readEnterprise level · TBD
Position GreenNo claim found on the pages we readEnterprise level · TBD
PulsoraNo claim found on the pages we readEnterprise level · TBD
QuenticNo claim found on the pages we readEnterprise level · TBD
Salesforce Net Zero CloudNo claim found on the pages we readNet Zero Cloud Growth £168,000 per organisation per year, billed annually, including one full CRM licence
SamiNo claim found on the pages we readEnterprise level · TBD
SAP Sustainability Footprint ManagementNo claim found on the pages we readEnterprise level · TBD
SedexNo claim found on the pages we readSedex Supplier membership costs £224 or £374 per year, depending on the level of membership you choose. (Per site, billed annually; buyer membership not priced.)
SeedlingNo claim found on the pages we readTBC
ServiceNow Operational Sustainability ManagementNo claim found on the pages we readEnterprise level · TBD
SimaProNo claim found on the pages we readEnterprise level · TBD
SINAI TechnologiesNo claim found on the pages we readEnterprise level · TBD
Small99No claim found on the pages we readSmall99 Hero is free for all small businesses to get started to take climate action.
SpheraNo claim found on the pages we readEnterprise level · TBD
Sweep“Pre-mapped to UK SRS S1 and UK SRS S2”Enterprise level · TBD
TansoNo claim found on the pages we readEnterprise level · TBD
TerrascopeNo claim found on the pages we readEnterprise level · TBD
TraceGenerate audit-ready ASRS, ISSB, and UK SRS-aligned disclosures with guided workflows, templates, and expert support.Enterprise level · TBD
Unravel CarbonNo claim found on the pages we readEnterprise level · TBD
WatershedNo claim found on the pages we readEnterprise level · TBD
Workday (supplier sustainability)No claim found on the pages we readEnterprise level · TBD
Workiva CarbonNo claim found on the pages we readEnterprise level · TBD
WorldfavorNo claim found on the pages we readA free plan for suppliers responding to data requests; buyer plans by quote
ZeveroNo claim found on the pages we readZevero Lite (Scope 1 & 2) starts from £1,500 / year; main plans (Essential, Leading, Premium) by quote; add-ons: Product Carbon Footprint starts at £500 / product; EPD from £10,000 / product; AI-powered ESG Reporting starting at £1,000; Decarbonisation Strategy from £2,000; B Corp Audit from £750. One-year minimum.

Each cell is the vendor’s own description of itself, linked to the page it is on.

A missing claim is a question to put to the vendor in writing, not evidence that the product lacks the capability.

Compare two vendors by what they publish · read 11 October 2026 and 30 September–1 October 2026

Published factAltruistiqASUENE
SECR outputAltruistiq gives you one calculation foundation for everything. Measure once and export to CSRD, CDP, SECR, California laws.Not found on the pages read
UK SRSGet compliant with CSRD, SRS, California Climate Disclosures and more.Not found on the pages read
ISSB / IFRS S2Not found on the pages readISSB(国際サステナビリティ基準審議会)が策定した国際的な開示基準(IFRS S1・S2)に準拠した、ESG関連データの集計・報告を行います。
CSRD / ESRSMeet CSRD, CDP, SECR, and California climate laws from one platform.Trained on 500+ company engagements, generates audit-ready disclosure responses for CDP, SBTi, CSRD, CBAM, IFRS S2, and TNFD.
ESOSNot found on the pages readNot found on the pages read
PPN 006Not found on the pages readNot found on the pages read
CBAMNot found on the pages readGenerate CBAM-ready reports and streamline LCA across complex, multi-tier material flows and Scope 1–3 process emissions
LCA / product footprintUpload ingredient data as you have it - no LCA expertise needed. Automated mapping handles the complexity, so you get product footprints without needing specialists.Calculates ISO 14067-compliant PCF and performs LCA across multi-level BOMs, aligned with CBAM, CSRD, and customer-specific requirements.
Scope 3Upload activity data once. Get GHG Protocol-aligned Scope 3 calculations across all categories.Processes multiple data formats and delivers accurate Scope 1–3 calculations automatically, including emission factor mapping.
Published priceEnterprise level · TBDEnterprise level · TBD
Ownership note——

Each cell is the vendor’s own description, linked to the page it is on.

No totals, no ranking: a missing claim is a question to put in writing.

Nothing is stored or sent.

61 vendors · esg reporting, ehs, supply chain

Show vendors by category

Alphabetical, which ranks nothing. Each description is the vendor’s own words from its own site, read 11 October 2026 and 30 September–1 October 2026; prices appear only where the vendor publishes one. No product here has been tested by this site.

Enterprise vendors publish their own product material: Workiva on carbon management, Salesforce on Net Zero Cloud and Microsoft on carbon accounting.

Read them for what each product does, and put the UK capability questions to each in writing; each profile on carbon reporting software sets a vendor’s own claims against the requirements.

Who writes the comparisons

Who publishes the comparisons, and what they score

This is stated as a fact, not an accusation, and it is easy to check.

Several of the comparisons that rank for these terms are published by a vendor that appears in its own table.

The neutral supply is mostly directories, and a directory is a feature grid rather than an argument.

Vendor-authored comparisons are still worth reading, because the underlying research is often good and the tables are real.

Read them for the raw material and supply your own scorecard, which is the method of this page.

Watch who wrote it, which frameworks form the columns — a table scored on ESRS datapoint coverage suits the platforms with the widest ESRS coverage — and whether any UK obligation appears at all.

The one paid, independent evaluation in wide circulation is Verdantix’s 2026 Green Quadrant for enterprise carbon management software, which evaluated 21 vendors; the press release carries its results, and this page repeats none of them.

What circulates is mostly each named vendor’s own announcement — one and another among them — which is a filtered view by construction.

Two things matter for a UK buyer: it evaluates enterprise carbon management, the measurement layer, and its criteria are global, so nothing in it is scored against SECR, ESOS or UK SRS.

Use it to shorten a longlist on capability and vendor viability, not to answer whether a platform can produce your directors’ report section.

Our sister publication covers the same market from the measurement side as carbon management software, disclosed here as a related property.

Authorship read from each page’s own domain. Stated as a fact about who wrote each list, not as a judgement of its research.
ComparisonPublished byIts own product in the table?
Best ESG reporting softwareSeedlingYes
ESG reporting software comparedPulsoraYes
Top carbon accounting softwareSweepYes
Best carbon accounting softwarePlan AYes
UK software listingDcycleA vendor-authored UK list

When software becomes necessary

Four triggers, and one that is not

UK companies usually move from spreadsheets to dedicated software when one of a few things happens, and it is worth knowing which one you are at.

The first is Scope 3 becoming material: supplier engagement across the fifteen GHG Protocol categories stops being a spreadsheet activity at any real scale.

The second is consolidation: several entities with a moving boundary is where manual reporting starts producing errors nobody catches.

The third is a reporting duty tied to the accounts: a listed company reporting against UK SRS from 2027 needs its sustainability figures on the same entity, period and timetable as the financial statements.

The fourth is the first assurance engagement, which usually ends the spreadsheet, because the evidence trail cannot be reconstructed after the fact.

What is not a trigger is a vendor saying the deadline is close: for most companies UK SRS is voluntary, and for listed companies the duty is comply or explain, so the work that cannot wait is data collection, not a licence.

The trigger is the data, not the turnover.

Software or consultancy

ESG software or consultancy: where the people stay

Software holds the data and the trail; the duties put particular people, not products, at the points that carry liability.

Neither software nor a consultancy is required by SECR, ESOS or UK SRS, and a consultancy can help with a first inventory or a method review.

Software earns its place when entities, Scope 3 or regimes multiply, or when an assurer first walks the process.

Read the detailed requirements and references
What the duties fix
The duties fix the output, such as SECR lines, a strategic report statement or an ESOS notification, and say nothing about which tool produces it.
Where people stay
Directors approve the strategic report, and knowingly or recklessly approving a non-compliant one is an offence; ESOS needs a lead assessor’s review; assurance, if wanted, is a separate engagement.

Our reading of CA 2006 s.414CB, the Environment Agency’s ESOS page and PS26/19, not advice on which to buy.

The guide to choosing a sustainability consultant covers the consultancy side.

A clear division of workExplore

A clear division of work

Platform

Ask it to demonstrate collection, calculation and output workflows.

Small-business budgets

ESG reporting on a small-business budget: start from the duty

Answer four questions to see what, if anything, a small business must report.

What a small business must report
Is the company quoted, or does it exceed two of £36 million turnover, £18 million balance sheet total and 250 employees?
After the first year the test runs over two consecutive years.
SI 2008/410 Sch 7 ¶20B

This site states a price only where a vendor publishes it; the published prices and the free tier are listed on carbon reporting software.

Any comparison that prints a price the vendor does not publish has inferred it.

Price

Most vendors publish no price, so ask the right questions

Most platforms in this market quote individually, and the price moves with the number of entities, the boundary, the Scope 3 categories in play, the frameworks and the consulting bundled in.

This site states a price only where the vendor publishes one, linked and dated, and otherwise writes Enterprise level · TBD; the published prices and free tiers are listed on carbon reporting software.

Treat any comparison that prints a vendor price the vendor does not publish with suspicion, because it has almost always been inferred.

Ask for the three-year cost, not the licence: implementation, data migration, training and the annual uplift often exceed year one’s fee.

Ask what is consulting and what is software, because a compliant output produced by a person on the vendor’s side is a recurring cost.

Ask what happens when you add an entity, because acquisitions are the commonest cause of an unplanned uplift and the answer is usually in the contract rather than the proposal.

Ask who owns the data on exit, because your calculation history is your audit trail, and getting it out in a usable form is a term worth negotiating on day one.

The honest comparison is not platform against nothing but platform against the way you do it now: count the hours the current spreadsheet takes across entities, Scope 3 categories and frameworks, and price the platform against those.

Platform against the way you work now

Current process £0 a year · quote £0 a year

Fill in all three to see the break-even hours.

Arithmetic on your own inputs.

The quote’s implementation, uplift and exit terms are in the three-year worksheet on the carbon reporting software page.

Nothing is stored or sent.

The demo

Nine questions that turn a claim into an answer

Each of these has a short, checkable answer, and each is a question a capable vendor is happy to be asked.

Run them on your own data where you can: one month, one site, your invoices, because a demo on the vendor’s sample data tells you about the sample data.

The factor-year question and the SECR-section question cover capabilities 01 and 02; the ESOS export covers 03; the acquisition and close-timing questions cover 04; the audit-trail question covers 05.

The last question — what comes out if you leave — is the one that decides how much the others are worth.

Get every answer in writing before the shortlist closes.

Demo questions · tick the ones you need

The pass tests are our reading of the cited provisions.

Nothing you tick is stored or sent.

The output

Stop reading comparisons: write the requirements document

A requirements document is a page and a half, and it changes every conversation afterwards: it is the difference between being shown a demo and running one.

A good shortlist built from it is usually two or three names, occasionally one, because most of the market is solving a different problem from yours.

A single entity with SECR only needs capabilities 01 and 02, and an enterprise suite is money spent on problems it does not have.

A mid-market group with SECR, ESOS and material Scope 3 needs 01, 02 and 03, with real supplier-engagement workflow.

A listed company, or one adopting UK SRS voluntarily, is decided by 04 and 05, and alignment with the accounts is the deciding criterion.

A group with an EU footprint adds ESRS coverage, and only then do the published comparison tables become the right instrument.

Sometimes the right answer is not to buy anything yet: a spreadsheet is a perfectly good tool for a single entity with a handful of sites and one framework, until Scope 3 becomes material, several entities need consolidating or an assurer walks the process.

If you would rather start from a structure than a blank page, the UK SRS readiness assessment covers the capability side and the ESG reporting template the output side; finished disclosures are on ESG reporting examples.

Stage 1 of 7
Outputs
List the outputs you owe: SECR section, ESOS evidence pack, UK SRS disclosures or explanation, a CRP, only those that apply. Done when each output names its provision.

After the signature

ESG software implementation is a data project

The licence is the small decision; whether the platform works depends on whether the data reaching it is complete, and that is an internal problem no vendor can solve for you.

Somebody has to own it, with time in their week, because programmes that fail almost always fail at ownership first.

The first year is collection, not reporting: finding the meter list, the fuel cards, the travel data and the supplier spend takes longer than configuring anything.

Historic restatement is a choice: rebuilding two prior years to a new method costs money and is sometimes worth it, so decide it deliberately rather than by drift.

The finance close is the deadline: if the sustainability numbers are not ready when the accounts are, the alignment UK SRS asks for is not met, whatever the software can do.

Vendors publish their own onboarding estimates, and they are statements about their own products; ask what the estimate assumes about your data, and who on your side it assumes will do the work.

What finished disclosures look like in practice is on ESG reporting examples.

The adjacent market

ESG ratings platforms are a different purchase

Ratings providers are often caught in the same search, and they do not do the same job.

They rate you for investors: reporting software helps you produce a disclosure, while a ratings provider forms a view about you whether or not you engage.

The ESG Ratings Order 2025, SI 2025/1349, made on 15 December 2025, brings providing an ESG rating within the FCA’s perimeter from 29 June 2028; until then a rating is an unregulated private opinion.

The overlap with this page is narrow: some disclosure platforms pre-fill a ratings questionnaire from data you already hold, which saves time but is not a compliance capability.

What the pillars mean and what each is measured on is on ESG criteria, the board-level side on ESG strategy, and the whole UK picture on the ESG reporting hub.

How long you have

Days left to each date, as at 1 October 2026

The bars are counted from 1 October 2026 and fixed at that date, so they do not tick down.

FCA TN 803.1 draft: comments close, 28 October 2026
27 days
ISSA 5000 and ISSA (UK) 5000 effective, 15 December 2026
75 days
ESOS Phase 4 qualification date, 31 December 2026
91 days
UK SRS periods begin for listed companies, 1 January 2027
92 days
ESOS Phase 4 notification due, 5 December 2027
430 days

Sources: FCA TN 803.1 · FRC ISSA (UK) 5000 · Environment Agency · FCA PS26/19.

The nearest dates are consultation and qualification dates; the compliance dates are further out.

The work that serves every one of them is data collection, which is why the calendar below ends where it does.

The clock

The calendar you are buying against

Read across those dates and one conclusion falls out: the work that survives every outcome is data collection.

Everything downstream of it — which framework, which template, which platform module — can be decided later, and cheaply.

The listed-company side of the calendar is on the FCA sustainability disclosure requirements page.

This page is independent reference material about UK reporting obligations and the software market that serves them; it is not procurement advice, no vendor pays to appear on it, and our privacy policy and terms apply.

  1. Every year01

    SECR

    In the directors’ report, inside the accounts filing window.
  2. 25 Feb 202602

    UK SRS S1 and S2 published

    By DBT, for voluntary use.
  3. 30 Sep 202603

    FCA final rules, PS26/19

    Comply or explain for listed companies.
  4. 28 Oct 202604

    FCA TN 803.1 comments close

    Draft guidance on explanations.
  5. 31 Dec 202605

    ESOS Phase 4 qualification date

    Size tested on this date.
  6. 1 Jan 202706

    UK SRS periods begin for listed companies

    First reports in 2028; UK CBAM also commences, as a tax.
  7. 5 Dec 202707

    ESOS Phase 4 notification

    Through MESOS.
  8. 29 Jun 202808

    ESG ratings regulation bites

    SI 2025/1349 main commencement.

A practical demonstration

ESG software comparison: show the evidence

A sample demonstration can reveal more than a feature tick. Ask the vendor to use your reporting boundary and show the whole path.

This is a suggested procurement test, not a certification or a finding that a product complies.

Context: GHG Protocol Corporate Standard · UK reporting guidance. Continue with GHG reporting software.

  1. 1

    Source record

    Use one of your own sample records. Preserve its unit, entity and period.

  2. 2

    Calculation

    Show the selected factor, method and any assumption.

  3. 3

    Disclosure

    Find the result in the required output and trace it back.

  4. 4

    Export

    Export the working and evidence so another person can repeat the check.

A real import failure

A blank factor, not zero emissions

DESNZ corrected the July 2026 flat file because some unavailable values had appeared as zero. The full-set workbook had correctly left them blank and was not revised.

Ask the supplier to show how its import distinguishes a blank from a number and identifies the factor revision used. This is a proposed test, not a claim about any vendor.

DESNZ: 2026 factors and July correction · GHG conversion factors

  1. 1

    A reported zero

    A numerical value with a source; preserve its meaning and unit.

  2. 2

    No available factor

    A blank is missing information. Do not silently convert it to zero.

  3. 3

    A corrected source

    Identify the publisher revision and which calculations need review.

A suggested procurement sequence

From the brief to a repeatable reporting process

Suggested demonstration and implementation steps; not a statutory timetable or product assessment.
  1. 01 / Brief01

    Define the output

    Name the entity, reporting period and applicable requirements.
  2. 02 / Demonstrate02

    Follow one sample record

    Trace its data, calculation, evidence and final disclosure.
  3. 03 / Compare03

    Keep claims and proof separate

    Record what was stated, shown, excluded and still to be confirmed.
  4. 04 / Implement04

    Test before the first close

    Import a sample period, reconcile it and review the evidence with its owners.
  5. 05 / Publish05

    Retain the working

    Keep the version, approvals and supporting records for the next reporting cycle.

Frequently asked

ESG reporting software, answered

What is ESG reporting software?

Software that collects environmental, social and governance data, calculates the figures a framework asks for and produces the report, with an evidence trail behind each number.

In practice most products sold under the label are strongest on the environmental pillar, especially greenhouse gas emissions, and extend to social and governance indicators to different degrees.

What is the best ESG reporting software?

There is no single best platform, and any comparison that names one has chosen the scoring criteria that produce that answer.

For a UK company the deciding questions are which obligations it carries — SECR, ESOS, UK SRS if listed, PPN 006, CDP — and whether a platform produces the output each one requires.

This page gives a planner that turns your obligations into a capability list, and the vendors’ own claims to test against it.

Do I need ESG software?

Only when the outputs you owe have outgrown the way you produce them.

A single-entity company with a few sites, no Scope 3 obligation beyond travel and one framework can report from a spreadsheet.

Software earns its place when Scope 3 becomes material, when several entities need consolidating, when several regimes draw on one dataset, or when an assurer first walks the process.

What features matter for UK SRS?

Alignment with the financial statements — the same reporting entity, the same period, published at the same time — which is where standalone carbon tools struggle.

Then GHG Protocol measurement with current conversion factors, location-based Scope 2, Scope 3 by category with exclusions recorded, a split of Scope 1 and 2 between the consolidated group and other investees, and for listed companies a gap register the comply-or-explain statement can be written from.

Is UK SRS mandatory?

No. UK SRS S1 and S2 are voluntary standards published by the Department for Business and Trade on 25 February 2026.

Under the FCA’s final rules in PS26/19, listed companies in UKLR 6, 14, 15, 16 and 22 must report against them on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027.

Nothing in UK SRS is fully mandatory, and no private-company threshold is proposed.

How much does ESG reporting software cost?

Most vendors do not publish a price, and the price moves with the number of entities, the boundary, the Scope 3 categories in play, the frameworks and the consulting bundled in.

Where a vendor publishes a price this site states it with a link and date; otherwise it reads Enterprise level · TBD.

Ask for a three-year cost including implementation, the annual uplift, the cost of adding an entity and the cost of exit.

What is the difference between sustainability reporting software and ESG reporting software?

They describe the same category from two angles.

Sustainability reporting software stresses structured disclosure against a named framework, with evidence trails and alignment with the accounts.

ESG reporting software stresses breadth across environmental, social and governance topics, including supplier questionnaires and board dashboards. <Link href="/environmental-reporting-software">Environmental reporting software</Link> is narrower again, usually the energy, emissions, waste and water surface that SECR and ESOS cover.

Is carbon accounting software the same as ESG reporting software?

No. Carbon accounting software is the measurement layer: it turns activity data into an emissions number.

ESG reporting software is the disclosure layer: it turns numbers into a filing tied to the reporting entity and period of the accounts.

Some platforms do both.

Buying a disclosure platform when the problem is missing meter data, or a measurement tool when the problem is an untraceable figure, is the same mistake in opposite directions.

Are published ESG software comparisons independent?

Often not, and it is easy to check.

Several comparisons that rank for these terms are published by a vendor that appears in its own table, sometimes at number one.

That does not make their research worthless; the tables are useful raw material.

It does mean supplying your own scoring criteria, because the columns of a comparison decide its winner.

Does any ESG platform handle ESOS?

ESOS is a UK-only energy audit on a four-year cycle, so it rarely appears in global comparisons.

What a platform can usefully do is hold total energy consumption in kWh by organisational purpose, show the 95% coverage, keep audit records and export an evidence pack a lead assessor can follow.

Phase 4 qualification is tested on 31 December 2026 and notification is due by 5 December 2027.

What is ESG compliance software?

ESG reporting software pointed at a legal duty rather than a voluntary report.

For a UK company that means producing the SECR lines in the directors’ report, an ESOS evidence pack, UK SRS disclosures or a comply-or-explain statement if listed, and, for EU entities in scope, a CSRD sustainability statement.

The test is whether each output comes out of the software rather than out of a consultant.

What should teams evaluate when choosing ESG reporting software for CSRD and GHG compliance?

First whether CSRD reaches the group at all after Directive (EU) 2026/470 narrowed it to undertakings exceeding €450 million turnover and 1,000 employees.

Then whether one dataset can produce ESRS datapoints, including both Scope 2 methods, and the UK outputs the group also owes, with GHG Protocol measurement, current conversion factors, Scope 3 by category and an evidence trail behind every figure.

How long does ESG software implementation take?

Vendors publish their own onboarding estimates, and they are statements about their own products.

The variable they cannot control is your data: finding meter lists, fuel cards, travel and supplier spend, and naming an owner for each feed, usually takes longer than configuring the platform.

Plan the first year as collection, with the finance close as the real deadline.

Is ESG still relevant in 2026?

The reporting duties a UK company carries are in force and moving, not fading: SECR continues after DESNZ’s 2026 review, ESOS Phase 4 qualifies on 31 December 2026, and listed companies report against UK SRS or explain from periods beginning on 1 January 2027.

What has narrowed is the EU side, where Directive (EU) 2026/470 cut CSRD’s scope.

The label matters less than which of those duties you carry.

What are the most popular ESG reporting platforms?

This site does not rank or count popularity, and nobody here has tested any product.

The alphabetical register of 73 vendors, each described in its own published words and showing only the price it publishes, is on the carbon reporting software page.

Use it as a longlist source, then hold each vendor to your own written requirements.

Who are the biggest ESG data providers?

ESG data providers in the investor sense are ratings and data vendors, not reporting software, and in the UK providing an ESG rating comes within the FCA’s perimeter from 29 June 2028 under SI 2025/1349.

A company buying software to produce its own disclosures is making a different purchase from an investor buying data about it.

Does ESG software need to cover GRI and SASB?

Only if a customer, investor or your own board asks for them: neither GRI nor SASB is a UK legal requirement.

SASB’s industry standards are maintained by the ISSB and inform IFRS S2, and UK SRS S2 is built from that; GRI is a broad stakeholder framework.

Treat them as voluntary columns on a requirements list rather than as a measure of whether a platform fits your legal duties.

Does ESG software cover UK CBAM?

UK CBAM is a tax on imports of aluminium, cement, fertiliser, hydrogen and iron and steel from 1 January 2027, under Part 5 of the Finance Act 2026, so it is an importer’s liability rather than a sustainability disclosure.

Some platforms offer embodied-emissions calculations that feed a return; the duty and the rules are published by HMRC and the government’s CBAM collection.

What does the FCA’s draft TN 803.1 mean for ESG software?

It is draft guidance, open for comment until 28 October 2026, proposing that an explanation under comply or explain can be short and proportionate and need not give a timeframe or address each requirement separately.

For software, the practical point is the same as before: keep a record of what was met and what was not, from which the explanation is written.

Are ESG ratings providers regulated in the UK?

Not yet.

The ESG Ratings Order, SI 2025/1349, made on 15 December 2025, brings providing an ESG rating within the FCA’s perimeter from 29 June 2028.

Until then a rating from a ratings provider is an unregulated private opinion, and a ratings provider is a different purchase from reporting software.

Does UK law require social and governance reporting?

In narrow, separate duties rather than one framework.

Directors must have regard to the community and the environment under section 172 of the Companies Act, and the strategic report carries a section 172(1) statement.

A commercial organisation with turnover of £36 million or more publishes a modern slavery statement, and an employer with 250 or more employees publishes gender pay gap figures.

Broader social and governance indicator lists answer to customers, investors and voluntary frameworks, not to a single UK statute.

Is the UK Corporate Governance Code a sustainability reporting requirement?

No. The FRC’s 2024 Code deliberately contains no sustainability reporting requirement, because the listing rules and the Companies Act already require climate-related disclosures.

What it does contain is Provision 29, which asks the board to declare the effectiveness of material controls, including controls over narrative and ESG reporting, for financial years beginning on or after 1 January 2026.

Does ESG software cover the Companies Act climate disclosures?

Section 414CB of the Companies Act 2006 sets eight climate-related disclosures for the largest traded companies, banks, insurers, AIM companies and companies with turnover over £500 million, above a 500-employee floor.

The Department for Business and Trade confirmed in February 2026 that UK SRS S2 is a national reporting framework for section 414CB(6), so a company reporting under S2 does not need to duplicate its disclosures.

The test for software is whether it holds the climate metrics once and maps them to whichever applies.

What should ESG software security look like?

No UK reporting regime sets a security standard for ESG software, so the questions come from general standards.

ISO/IEC 27001:2022 is the best-known standard for an information security management system, and the NCSC’s Cyber Essentials is built on five technical controls.

Where the vendor processes personal data for you, Article 28(3) of the UK GDPR requires a contract covering instructions, confidentiality, security, sub-processors, data subjects’ rights, assistance, end-of-contract provisions and audits.

Which ESG reporting tool suits a small business budget?

This site names no product, and prices appear only where a vendor publishes them.

A business below the SECR and ESOS tests, not quoted and not bidding for in-scope central government contracts, has no statutory duty on size alone, and a spreadsheet with the DESNZ factors and a written method is enough to start.

A supplier to an EU company reporting under CSRD may be asked for data, and the value-chain cap limits what that reporter can require of an undertaking with 1,000 employees or fewer.
Sources

Primary sources

Every figure, date and status on this page traces to the instrument’s owner.

Secondary commentary is never the source for a number.

Checked against 47 sources fromDESNZGHG Protocol (WRI, WBCSD)Department for Energy Security and Net ZeroGOV.UK (DESNZ, Defra)legislation.gov.ukEnvironment Agency
  1. DESNZ
    2026 conversion factors — July flat-file correction

    Unavailable values were corrected from zero to blank. The full-set workbook was not revised.

  2. GHG Protocol (WRI, WBCSD)
    Corporate Accounting and Reporting Standard

    The measurement basis every platform claims.

  3. GHG Protocol (WRI, WBCSD)
    Scope 3 technical calculation guidance

    The fifteen categories and the calculation methods.

  4. Department for Energy Security and Net Zero
    Government conversion factors for company reporting

    Republished annually; capability 01.

  5. GOV.UK (DESNZ, Defra)
    Environmental Reporting Guidelines, including SECR requirements

    The SECR guidance; last updated 29 March 2019.

  6. legislation.gov.uk
    SI 2018/1155 — the SECR Regulations

    The instrument that inserted SECR into the accounts regulations.

  7. legislation.gov.uk
    SI 2008/410, Schedule 7

    The SECR lines themselves, paragraphs 15–20K.

  8. Environment Agency
    Energy Savings Opportunity Scheme (ESOS)

    Phase 4 qualification and compliance dates; capability 03.

  9. Environment Agency
    How to comply with ESOS Phase 4

    Total energy by organisational purpose, the 95% floor, the evidence pack.

  10. Department for Business and Trade
    UK Sustainability Reporting Standards — guidance

    Published 25 February 2026 for voluntary use.

  11. Department for Business and Trade
    UK SRS S1 (PDF)

    ¶20: the same reporting entity as the financial statements; capability 04.

  12. Financial Conduct Authority
    PS26/19 — final rules on listed issuers’ sustainability disclosures

    Comply or explain against UK SRS from 2027; the assurance and transition-plan statements.

  13. Financial Conduct Authority
    CP26/5 — the consultation PS26/19 finalises

    The proposal, for comparison.

  14. Financial Reporting Council
    ISSA (UK) 5000

    Issued 12 November 2025 for voluntary use; effective for periods from 15 December 2026.

  15. Financial Reporting Council
    Sustainability reporting developments — FAQs

    How the standards are being applied.

  16. IFRS Foundation
    International Sustainability Standards Board

    IFRS S1 and S2, the architecture UK SRS is built from.

  17. EUR-Lex
    Delegated Regulation (EU) 2023/2772 — ESRS

    The legal instrument behind the ESRS columns in most comparisons.

  18. EFRAG
    European Sustainability Reporting Standards

    The standard-setter’s own ESRS page.

  19. legislation.gov.uk
    The FSMA 2000 (Regulated Activities) (ESG Ratings) Order 2025 (SI 2025/1349)

    ESG ratings brought within the FCA perimeter from 29 June 2028.

  20. Cabinet Office
    PPN 006 Technical Standard

    The five Scope 3 categories a Carbon Reduction Plan covers.

  21. CDP
    CDP — the disclosure system

    A voluntary questionnaire with its own scoring.

  22. Verdantix
    Green Quadrant: Enterprise Carbon Management Software (2026) — press release

    21 vendors evaluated; eight named Leaders.

  23. GRI
    GRI Standards

    Voluntary; the framework most comparison tables score as a column.

  24. IFRS Foundation (SASB)
    SASB Standards

    Voluntary industry standards, now maintained by the ISSB.

  25. ISO
    ISO 14064-1: organisation-level GHG quantification

    The other inventory standard a verifier may check against.

  26. ISO
    ISO 50001: energy management

    An ESOS compliance route where certified.

  27. legislation.gov.uk
    SI 2026/701 — ESOS amendment regulations

    Phase 4 amendments, including regulations 27D and 27E.

  28. Financial Conduct Authority
    TN 803.1 (draft) — comply-or-explain explanations

    Draft technical note; comments close 28 October 2026.

  29. Department for Energy Security and Net Zero
    SECR evaluation report

    Counted 19,900 companies and LLPs in scope.

  30. HM Revenue and Customs
    UK CBAM policy summary

    A tax on imports from 1 January 2027, not a reporting duty.

  31. GOV.UK
    UK greenhouse gas emissions statistics

    The national inventory behind the grid-factor movement.

  32. Department for Business and Trade
    Modernising corporate reporting consultation

    The wider reporting reform context.

  33. IPCC
    Sixth Assessment Report, Working Group I

    The physical science behind scenario pathways.

  34. ICAEW
    Sustainability hub

    Professional-body material on adoption and assurance.

  35. legislation.gov.uk
    Companies Act 2006, section 414CB — climate-related financial information

    The eight disclosures at (2A)(a) to (h), and (6) on national reporting frameworks.

  36. legislation.gov.uk
    Companies Act 2006, section 414CA — which companies are in scope

    Traded companies, banks, insurers, AIM companies and high turnover companies, above the 500-employee floor.

  37. legislation.gov.uk
    Companies Act 2006, section 172 — duty to promote the success of the company

    Six listed matters, including the community and the environment.

  38. legislation.gov.uk
    Companies Act 2006, section 414CZA — section 172(1) statement

    The statement in the strategic report; not for medium-sized companies.

  39. legislation.gov.uk
    Modern Slavery Act 2015, section 54 — transparency in supply chains

    A slavery and human trafficking statement; enforced by injunction.

  40. legislation.gov.uk
    The Modern Slavery Act 2015 (Transparency in Supply Chains) Regulations 2015

    Regulation 2 sets the £36 million turnover figure; regulation 3 counts subsidiaries.

  41. legislation.gov.uk
    The Equality Act 2010 (Gender Pay Gap Information) Regulations 2017

    250 or more employees on 5 April; six metrics within twelve months.

  42. Financial Reporting Council
    UK Corporate Governance Code 2024

    Provision 29 applies from 1 January 2026 and covers controls over ESG reporting.

  43. European Commission (Council register)
    C(2026) 5010 final — revised ESRS, Delegated Regulation

    Article 3: applies to financial years beginning on or after 1 January 2027.

  44. European Commission (DG FISMA)
    Commission adopts revised sustainability reporting standards (3 July 2026)

    The adoption announcement; cited for the event, not for when the standards apply.

  45. ISO
    ISO/IEC 27001:2022 — information security management systems

    The standard a vendor’s security certificate refers to.

  46. NCSC
    Cyber Essentials

    Five technical controls; certification by self-assessment or with a certification body.

  47. Information Commissioner’s Office
    UK GDPR: what needs to be included in a processor contract

    Article 28(3): the minimum terms where a vendor processes personal data for you.

Book a free consultation