Reporting · framework, calendar, data, words
Sustainability reporting consultants UK
Choose the reporting framework before commissioning the report. Build a controlled evidence trail, clear responsibilities and a calendar tied to your actual reporting period.
UK SRS is an independent reference site. We have assessed no consultancy and publish no consultancy prices or rankings.
The job
What a sustainability reporting consultancy delivers
A sustainability reporting consultancy is bought for a deliverable with a date on it: a disclosure in a named document, by a deadline set in law or listing rules.
That makes it a narrower purchase than strategy work, and an easier one to judge.
Read the detailed guidance and references
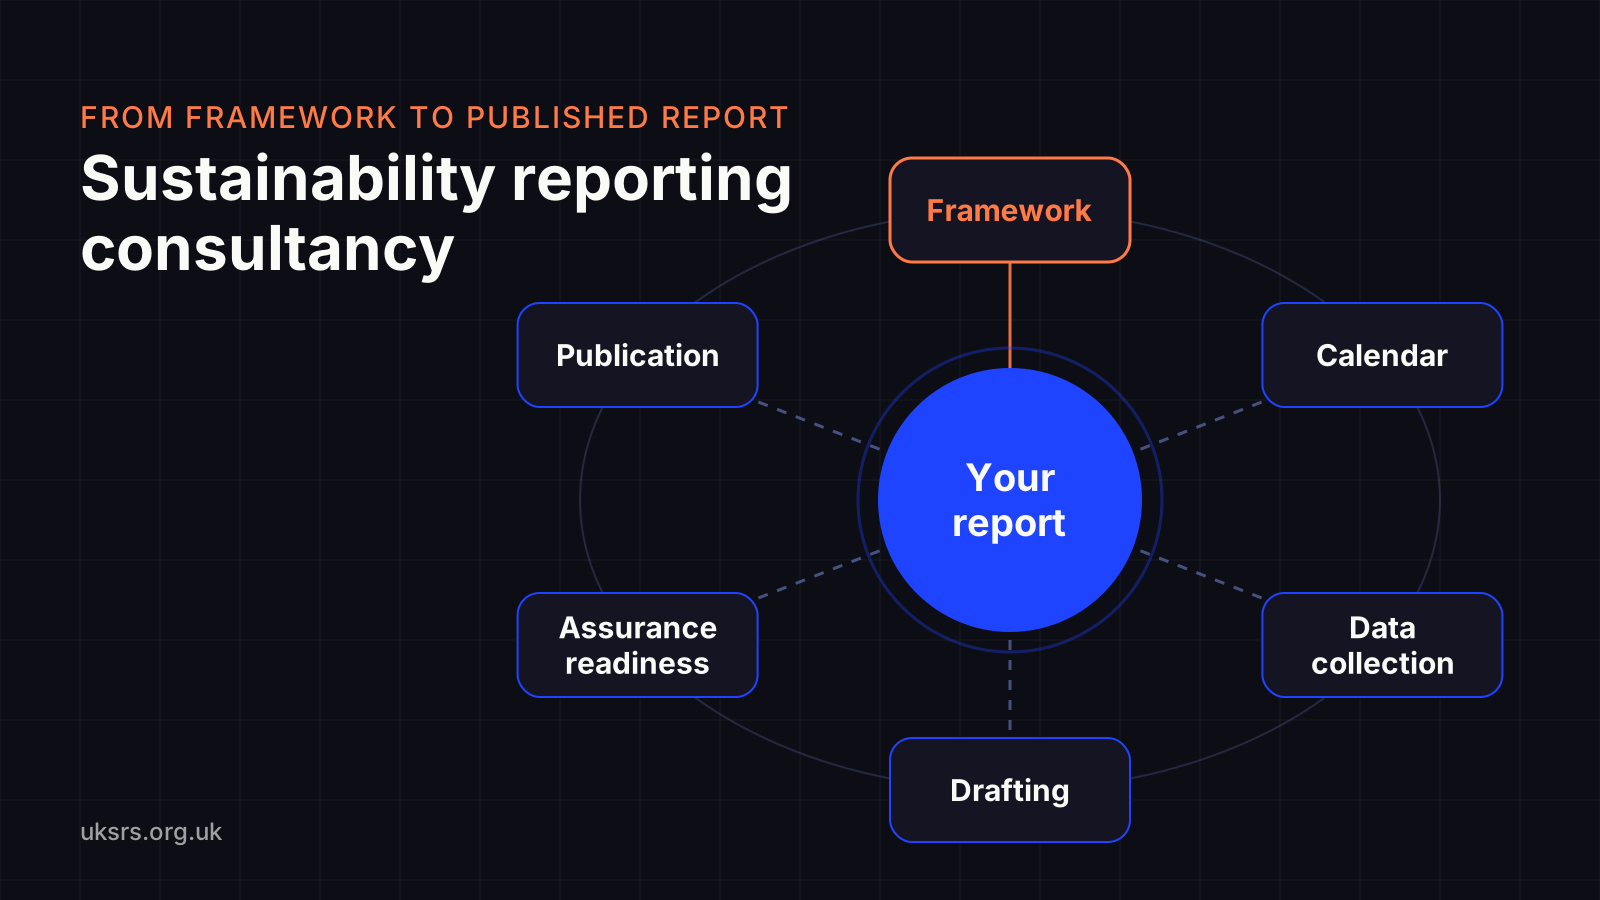
The work runs in six moves: framework, calendar, data, drafting, assurance readiness and publication.
A sustainability reporting consultancy that starts at drafting has skipped the two moves that decide whether the draft is right.
What the subject covers is on sustainability reporting, and the national picture on UK sustainability reporting.
- sets
- drives
- feeds
- is tested for
- goes into
Module 01 / 04
Scope
Module 02 / 04
Evidence
Module 03 / 04
Draft
Module 04 / 04
Approval
First move
Which framework applies to you
UK duties: Check existing SECR and climate disclosure rules. UK SRS: Check the listing category or voluntary adoption.
Read the detailed guidance and references
| Regime | Who it reaches | Status | Where it sits |
|---|---|---|---|
| UK SRS S1 and S2 | Listed companies in UKLR 6, 14, 15, 16 and 22; anyone else by choice | Comply or explain for periods from 1 January 2027; voluntary otherwise | Annual financial report |
| SECR | Quoted companies; unquoted companies and LLPs not meeting two of the “not more than” conditions | In force since 2019 | Directors’ report (energy and carbon report for LLPs) |
| Climate-related financial disclosure | Companies within s.414CA with more than 500 employees | In force; UK SRS S2 can discharge it | Strategic report |
| CSRD | EU undertakings over 1,000 employees and €450 million turnover; some third-country groups | In force in the EU, as amended | Management report under ESRS |
| IFRS S1 and S2 | Wherever a jurisdiction adopts them | Effective 1 January 2024 where adopted | General purpose financial reports |
The standards themselves are compared on the standards comparison.
A consultant who cannot say, for your company, which row applies and why, is not ready to quote.
The FCA listing rule does not create a general UK SRS duty for private companies. Separate reporting rules, overseas obligations and contractual requests need their own scope checks.
Each regime has its own test, status and home document, and most organisations meet more than one.
Module 01 / 04
UK duties
Module 02 / 04
UK SRS
Module 03 / 04
EU reporting
Module 04 / 04
Other requests
UK SRS
Comply or explain, and the explanation is work
The Department for Business and Trade published UK SRS S1 and S2 on 25 February 2026 for voluntary use.
On 30 September 2026 the FCA finalised PS26/19: listed companies in UKLR 6, 14, 15, 16 and 22 report against UK SRS, or explain, for accounting periods beginning on or after 1 January 2027, with first reports in 2028.
Read the detailed guidance and references
Two reliefs apply from initial application: Scope 3 for one year, and non-climate S1 matters for two years.
A company using a relief says so in its annual financial report, and the rules do not ask it to explain further during the relief period.
Companies in UKLR 6, 16 and 22 also state whether they have published a transition plan, where it is, or why not.
The FCA’s draft Technical Note 803.1, open for feedback until 28 October 2026, proposes guidance on what an explanation should contain.
The standards are on UK SRS S1 and S2, and the dates on when UK SRS reporting starts.
Module 01 / 04
Coverage
Module 02 / 04
Standards
Module 03 / 04
Explanation
Module 04 / 04
Location
Already in force
SECR and the climate disclosure do not wait for 2027
SECR is an exemption test: an unquoted company is exempt where it meets two or more of turnover not more than £36 million, balance sheet not more than £18 million and not more than 250 employees, under paragraph 20B.
A quoted company reports global Scope 1 and 2 emissions at any size, while an unquoted company reports its UK energy use and the emissions from it, including transport fuel, under Part 7A.
Read the detailed guidance and references
The government’s evaluation counted 19,900 organisations in scope.
The climate-related financial disclosure under s.414CA reaches traded, banking, insurance and AIM companies and those with turnover over £500 million, and in every case only with more than 500 employees.
It asks for the eight disclosures at s.414CB(2A), from governance to targets and key performance indicators.
The government has confirmed in its consultation response that UK SRS S2 is a national reporting framework under s.414CB(6), so reporting under S2 avoids duplicating those disclosures.
The detail is on SECR and climate-related financial disclosures, and SECR-only help on SECR consultancy.
Module 01 / 03
SECR
Module 02 / 03
CFD
Module 03 / 03
Report
Beyond the UK
CSRD after Omnibus I, and the ISSB baseline
Most UK groups meet CSRD through an EU subsidiary or EU turnover rather than as a direct reporter.
Directive (EU) 2026/470, in force since 18 March 2026, narrowed scope to undertakings exceeding both 1,000 employees and €450 million net turnover.
Read the detailed guidance and references
Third-country groups are caught through Article 40a at more than €450 million of EU turnover, with an EU subsidiary or branch threshold of €200 million.
CSRD reporting uses the ESRS and double materiality, which UK SRS does not, so the brief needs European reporting experience; the overlap is on the CSRD guide.
UK SRS is built on the ISSB’s standards, and IFRS S2 is effective for annual periods beginning on or after 1 January 2024 wherever a jurisdiction adopts it.
The UK removed that effective date from its own versions, so the UK timetable comes from the FCA, not the ISSB; the ISSB framework page explains the relationship.
Module 01 / 04
Entity
Module 02 / 04
Scope
Module 03 / 04
National law
Module 04 / 04
Standards
Second move
Work back from the deadline
Every report has one fixed date, and every other date is worked back from it.
A listed company makes its annual financial report public at the latest four months after year end, under DTR 4.1.3R.
Read the detailed guidance and references
Accounts and reports reach Companies House nine months after year end for a private company and six for a public one, under s.442, and SECR travels with them.
The panel builds those dates for your year end, including the first UK SRS period if you are listed in scope.
Ask any consultant for the last date data can arrive and still make the report, because that is where most timetables fail.
Build your reporting calendar
30 September 2028
Accounts and reports for the year ending 31 December 2027 due at Companies House, carrying the SECR disclosure.
CA 2006 s.442(2): nine months, private company
Assumes a twelve-month year ending on a month end; a first year, a shortened period or an extension changes the dates.
Module 01 / 04
Period end
Module 02 / 04
Review
Module 03 / 04
Approval
Module 04 / 04
Publication
On the wall
The dates that matter to 2029
Publication: A standard or rule is released. Application: The reporting period begins.
Read the detailed guidance and references
- 18 March 2026CSRD, as amended, in force in the EUMore than 1,000 employees and €450 million turnover, cumulatively.Directive (EU) 2026/470
- 30 September 2026FCA PS26/19 publishedComply or explain across UK SRS for the five listing categories.FCA
- 28 October 2026Feedback on draft TN 803.1 closesProposed guidance on what an explanation should contain.FCA
- 15 December 2026ISSA (UK) 5000 takes effectFor periods beginning on or after this date; voluntary use.FRC
- 1 January 2027First UK SRS periods beginFor listed companies in scope; Scope 3 relief for the first year, non-climate S1 relief for two.FCA PS26/19 ¶¶3.12, 3.14
- 30 April 2028First reports for 31 December year endsAnnual financial report public within four months.DTR 4.1.3R
- 1 January 2029Both reliefs gone for new periodsComply or explain applies in full; nothing becomes mandatory.FCA PS26/19 ¶3.24
When a relief expires nothing becomes mandatory: the disclosure moves from relief to comply or explain.
The 30 April 2028 date assumes a 31 December year end; the calendar above handles the others.
Module 01 / 04
Publication
Module 02 / 04
Application
Module 03 / 04
Submission
Module 04 / 04
Relief
Third move
Data collection is most of the job
The words take weeks, while the data takes the year, so the useful hours of a sustainability reporting consultancy are spent on collection and control.
UK SRS S2 ¶29(a) asks for absolute gross greenhouse gas emissions by scope, which means an inventory with a documented boundary and method.
Read the detailed guidance and references
Most UK inventories follow the GHG Protocol Corporate Standard and apply the government’s 2026 conversion factors to activity data.
The Scope 3 relief buys one year, not an exemption, so supplier data work should start in the first year rather than after it.
Name an owner for every data point, and keep the workings, not just the totals.
The method is on carbon accounting, value-chain data on UK SRS Scope 3 reporting, and the tools on carbon reporting software.
Module 01 / 04
Record
Module 02 / 04
Method
Module 03 / 04
Review
Module 04 / 04
Disclosure
Hand-overs
What a sustainability reporting consultant hands over
Judge a sustainability reporting consultant by what you keep at each stage, not by the capability deck.
Each step in the panel names a deliverable, the question to ask, and what should stay with you when the engagement ends.
Read the detailed guidance and references
The drafts are yours to approve, because the company, not the adviser, is responsible for the report.
If year two still needs the same firm for the same work, the hand-overs did not happen.
- 1
Brief
Agree framework, period and responsibilities.
- 2
Gather
Collect records and resolve missing inputs.
- 3
Draft
Prepare the statements and explanations.
- 4
Review
Challenge, approve and retain the working.
Assurance readiness
Ready for an assurer, chosen first
The FCA’s rules do not require assurance; where a company obtains it, the annual financial report names the provider, scope, level and standards.
The FRC issued ISSA (UK) 5000 on 12 November 2025 for voluntary use, and paragraph 15 makes it effective for periods beginning on or after 15 December 2026.
Read the detailed guidance and references
The government’s response on assurance oversight set out a voluntary regime with an interim register to be run by the FRC.
The IESBA standards bar an assurance practitioner from assuming management responsibility for a client, and generally prohibit self-review services for public interest entities.
So decide early whether you want assurance, choose the provider, and brief the drafting around it.
The standards are set out on sustainability assurance.
Module 01 / 04
Management
Module 02 / 04
Preparer
Module 03 / 04
Assurer
Module 04 / 04
Reader
Same work, other label
When the brief says ESG reporting consultancy
An ESG reporting consultancy usually sells the same service, often with ratings questionnaires added.
ESG is a description, not a standard, so ask which named framework the report will be prepared against.
Read the detailed guidance and references
The ESG side is covered on ESG reporting, the frameworks on UK ESG frameworks, and the wider service on ESG consulting services.
If the question is which kind of adviser you need at all, start with ESG consultancy.
Module 01 / 04
Measurement
Module 02 / 04
Strategy
Module 03 / 04
Reporting
Module 04 / 04
Ratings
Choosing a firm
Briefing the firm you shortlist
When you brief a sustainability reporting consultancy, name the framework and the document it lands in.
“UK SRS in the annual financial report for the year ending 31 December 2027” is a brief.
Read the detailed guidance and references
Give the figures the tests use, so nobody bills you for discovering them.
Ask for days by grade, the second year priced in the same proposal, and who owns the workings at the end.
Ask whether the firm, or anyone linked to it, would also be your assurance provider.
This site names no firm, ranks none and quotes no price; the selection process is in how to choose a sustainability consultant.
Ask the firm to tell you, in writing, which disclosures you could reasonably explain rather than make in your first year.
A firm that answers “none” is selling the most work, not the right amount.
Module 01 / 04
Output
Module 02 / 04
Inputs
Module 03 / 04
Review
Module 04 / 04
Handover
Illustrative brief · no consultancy assessed
A worked brief: a company prepares its first standards-based report
First establish the applicable reporting route and period. A sensible engagement separates the gap analysis, calculation working, draft disclosures and approval.
For the detailed requirements, see sustainability reporting.
View the workflow diagram
- 1
Framework
Document the scope decision and standard version.
- 2
Working
Reconcile source records to the draft disclosures.
- 3
Approval
Resolve omissions and retain the explanation.
Each date has a different meaning
The relevant dates, in order
Check who the date applies to and whether it is publication, application, submission or a planned milestone.
- 25 February 202601
UK SRS published
Available for voluntary use; publication alone does not create a universal company duty. - 30 September 202602
- Periods from 1 January 202703
Listed-company application
UKLR 6, 14, 15, 16 and 22 report against the standards or explain. - 2028 / for calendar-year companies04
First reports under the new rule
Other year ends have their own annual-report timetable.
A suggested delivery sequence
From the brief to the handover
This is an editorial buying and preparation sequence, not a statutory timetable or a promise about how long the engagement takes.
- 01 / Brief01
Brief
Name the duty or decision and the required output. - 02 / Evidence02
Evidence
Collect records, methods and assumptions. - 03 / Preparation03
Preparation
Draft the calculations, disclosures or action plan. - 04 / Review04
Review
Resolve gaps and assign the relevant approvals. - 05 / Handover05
Handover
Keep editable working, ownership and update guidance.
Frequently asked
Questions buyers ask
What does a sustainability reporting consultancy do?
A sustainability reporting consultancy helps an organisation get a report out: it confirms which framework applies, builds the calendar back from the publication deadline, organises the data, drafts the disclosures and prepares the evidence an assurance provider would ask for.
The best ones also leave behind a process your own team can run next year.
Which sustainability reporting framework applies to my company?
It depends on what you are.
Listed companies in UKLR 6, 14, 15, 16 and 22 report against UK SRS on a comply-or-explain basis for periods beginning on or after 1 January 2027.
Larger unquoted companies and all quoted companies make a SECR disclosure.
Companies within s.414CA with more than 500 employees make a climate-related financial disclosure.
CSRD reaches some UK groups through EU subsidiaries or EU turnover.
For everyone else UK SRS is voluntary.
Is UK SRS mandatory?
No. Under the FCA’s final rules of 30 September 2026, listed companies in UKLR 6, 14, 15, 16 and 22 report against UK SRS on a comply-or-explain basis for periods beginning on or after 1 January 2027, with first reports in 2028.
For any other entity UK SRS remains available for voluntary use.
When is the first UK SRS report due?
For a listed company in scope with a 31 December year end, the first period runs through 2027 and the annual financial report must be public by 30 April 2028, four months after year end under DTR 4.1.3R.
Other year ends move the dates; the calendar builder on this page works them out.
Do we need assurance on our sustainability report?
Not under the FCA’s rules.
If you obtain assurance, the annual financial report states the provider, scope, level and standards used.
The FRC issued ISSA (UK) 5000 for voluntary use, effective for periods beginning on or after 15 December 2026.
Can the consultancy that drafts our report also assure it?
Usually not.
The IESBA ethics standards for sustainability assurance bar a practitioner from assuming management responsibility for a client and generally prohibit self-review services for public interest entities.
Choose the assurance provider first, then brief the drafting work around it.
What is an ESG reporting consultancy?
Usually the same service under a different label: a firm that helps with environmental, social and governance disclosures, often including ratings questionnaires.
Ask which named framework the report will be prepared against, because ESG is a description, not a standard.
How much does a sustainability reporting consultant cost?
This site quotes no prices and has assessed no firm’s fees.
Ask for a written scope naming each stage, the days by grade, what your team will supply, and the second year priced in the same proposal.
The one government cost measure in this field is for SECR alone: a mean ongoing compliance cost of £7,100 a year, internal and external together.
Does UK SRS replace the climate-related financial disclosure?
Not by repeal.
The government has confirmed that UK SRS S2 is a national reporting framework for s.414CB(6) of the Companies Act, so a company reporting in accordance with UK SRS S2 does not need to duplicate those disclosures, and it is considering the future of the s.414CB(2A) duty.
Sources
Primary sources
Every figure, date and status on this page traces to the instrument’s owner.
Secondary commentary is never the source for a number.
- Financial Conduct AuthorityPS26/19: Aligning listed issuers’ sustainability disclosures with international standards
Comply or explain across UK SRS for UKLR 6, 14, 15, 16 and 22, periods beginning on or after 1 January 2027.
- Financial Conduct AuthorityPS26/19 (PDF), ¶¶1.2, 3.6, 3.12, 3.14, 3.20 and Appendix 1
Scope, timing, the reliefs, the relief statement and the assurance statement.
- Financial Conduct AuthorityDraft Technical Note 803.1 (September 2026)
Proposed guidance on comply or explain; feedback by 28 October 2026.
- FCA HandbookDTR 4.1 — annual financial report
DTR 4.1.3R: public at the latest four months after year end.
- Department for Business and TradeUK SRS S1 and UK SRS S2
Published 25 February 2026, available for voluntary use.
- Department for Business and TradeUK SRS S2 (PDF), ¶29(a)
Absolute gross greenhouse gas emissions by scope.
- Department for Business and TradeUK SRS consultation response (PDF), Chapter 3
UK SRS S2 is a national reporting framework for s.414CB(6).
- legislation.gov.ukSI 2008/410 Schedule 7 paragraph 20B
SECR’s exemption: two or more “not more than” conditions.
- legislation.gov.ukSI 2008/410 Schedule 7 Part 7A
What an unquoted company’s energy and carbon report contains.
- Department for Energy Security and Net ZeroIndependent evaluation of SECR (2026)
19,900 organisations in scope.
- legislation.gov.ukCompanies Act 2006 s.414CA
Who must make a climate-related financial disclosure, and the 500-employee floor.
- legislation.gov.ukCompanies Act 2006 s.414CB
The eight disclosures at (2A)(a)–(h) and national reporting frameworks at (6).
- legislation.gov.ukCompanies Act 2006 s.442
Filing periods: nine months for a private company, six for a public one.
- EUR-LexDirective (EU) 2026/470 (Omnibus I)
CSRD scope: more than 1,000 employees and more than €450 million turnover; Article 40a.
- IFRS FoundationIFRS S2 Climate-related Disclosures
Effective for annual periods beginning on or after 1 January 2024 where adopted.
- FRCISSA (UK) 5000 (PDF), paragraph 15
Effective for periods beginning on or after 15 December 2026; for voluntary use.
- FRCFRC takes steps to support quality in sustainability assurance (12 November 2025)
Issue of ISSA (UK) 5000.
- Department for Business and TradeDeveloping an oversight regime for assurance of sustainability-related financial disclosures
A voluntary oversight regime and an interim register run by the FRC.
- IESBAIESSA Technical Overview (January 2025)
Management responsibility and self-review.
- Greenhouse Gas ProtocolCorporate Standard
The inventory method behind most UK carbon figures.
- Department for Energy Security and Net ZeroGreenhouse gas reporting: conversion factors 2026
The factors a UK inventory applies to activity data.
Continue reading
Read next
UK SRS S1 and S2
The two standards, side by side.
Assurance, explained
Standards, levels and independence.
Which ESG consultant you need
Start from the obligation, not the firm.
ESG consulting services
Each service itemised, from materiality to assurance.
Sustainability strategy consultancy
Materiality, targets, transition plans and governance, phase by phase.
Sustainability consulting firms
Selection criteria tied to the law, and an unranked A–Z directory.